Prudential Clears A Lowered Bar, But A Longer Japan Suspension Breaks Its Earnings Growth Streak
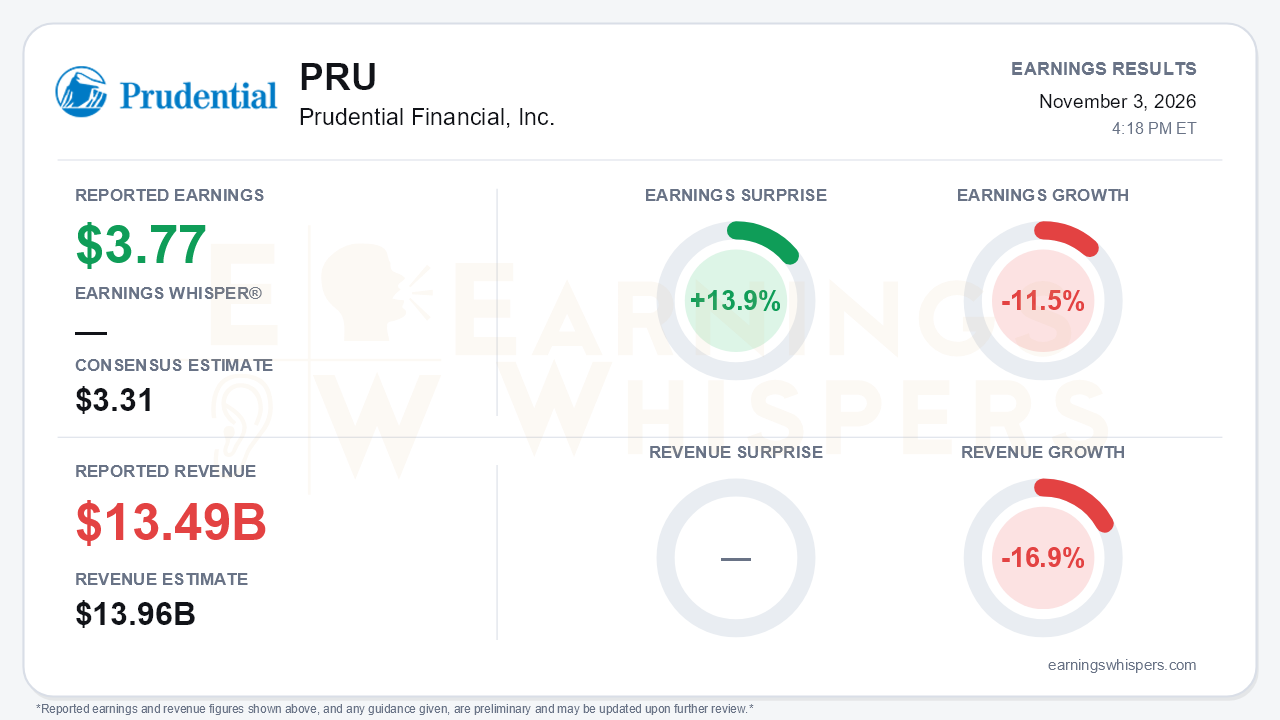
Prudential Financial reported third-quarter adjusted operating earnings of $3.77 per share, beating the $3.31 consensus by 13.9%. The beat was against a bar that had already been lowered for Japan, and the quarter's more important development was that the Prudential of Japan problem got bigger and longer. On Earnings Whispers' normalized basis, earnings fell 11.5% year over year. The company's own comparison is $3.77 versus $4.05, roughly a 7% decline. Either way, the quarter ended a run of year-over-year growth that included double-digit gains in the first and second quarters. Revenue of $13.493 billion missed the $13.96 billion consensus by 3.3% and fell 16.9% year over year. That is the central tension: Prudential beat estimates while showing that its largest overseas earnings engine is still shrinking.
The quality of the beat deserves scrutiny. Japan Businesses' pre-tax adjusted operating income fell to $559 million from $750 million, a 25% decline. The release attributed the drop to higher expenses and weaker underwriting tied to the suspension, plus lower spread income. Japan constant-dollar sales fell 36% to $291 million. Elsewhere, two segment gains came with asterisks:
- **Individual Life** jumped to $199 million from $153 million, but roughly $30 million came from a reserve refinement.
- **PGIM's** improvement to $263 million from $244 million partly reflected the absence of a prior-year reorganization charge.
U.S. Businesses slipped to $1.173 billion. Inside that segment:
- **Legacy Products** fell to $253 million from $308 million as the variable annuity block ran off; legacy account values dropped 12%.
- **Retirement** declined to $620 million on pension risk transfer runoff and less favorable mortality.
GAAP results told a similar story. Net income was $3.96 per share versus $4.01. That figure was helped by $295 million of pre-tax earnings from divested and run-off businesses and $104 million of market experience gains, while credit-related losses rose to $184 million from $114 million.
The call preserved a credible growth story outside Japan. Retail annuity sales reached $3.9 billion, the highest since 2013, up from $3.6 billion in the second quarter and $3.3 billion in the first, with a record quarter for registered index-linked annuities. PGIM's third-party net flows reached $9.0 billion, the best in 10 quarters and nearly double the second quarter's $4.6 billion. The active ETF platform has topped $40 billion, and PGIM's 26.5% quarterly margin puts it ahead of its 200-basis-point expansion target. Group Insurance earnings rose 12% to $101 million, and year-to-date sales grew 23%. Management also lowered its effective tax rate guidance to 20-21% and said its expense program is running ahead of the $150 million 2027 run-rate target.
Japan is where expectations were cut, and the details matter:
- **Restart pushed back.** The suspension is now FSA-ordered. The Prudential of Japan restart slipped from early November to a phased return beginning February 1.
- **Broader scope.** Gibraltar has been added to the suspension.
- **Larger cost.** Full-year impact guidance is now about $500 million for Prudential of Japan plus a new roughly $100 million for Gibraltar's parent unit, up from a prior $525-575 million range.
- **Lasting damage.** Management still expects roughly a 15% reduction in Prudential of Japan's in-force earnings power.
Other risks emerged as well. Group disability incidence and severity are elevated, driven by behavioral health claims and high-wage earners, and management struck a cautious tone. Retirement gross sales fell to $8.2 billion from $9.7 billion, and net flows turned negative at $976 million. Pension risk transfer activity did reopen in October, with about $1.6 billion across three deals.
The offset is a faster portfolio overhaul. Prudential agreed to sell its Brazil and Mexico businesses for $4.025 billion gross, about $3.1 billion net, with closing expected in the second half of next year. That is more than its earlier framing of "well north of $3 billion." The company also closed its Indonesia and Kenya sales and announced a South Africa sale. Japan's solvency ratio near 200%, above the prior 170-190% estimate, shows the balance sheet can absorb the disruption. Adjusted book value rose to $102.39 per share, even as GAAP book value fell to $84.88 on AOCI. However, proceeds are earmarked for targeted acquisitions in a competitive market, and execution risk now sits squarely in the investment case.
Investors were not leaning bullish going in. Earnings Whispers sentiment edged from -0.30 to -0.34, a modest move further into negative territory rather than a capitulation. Shares at $118.81 are down 4.2% since the open following the August report. They remain 9.3% above their 200-day moving average of $108.67, so the longer-term trend has not broken despite the post-summer drift. Internal trend readings are mixed, with momentum positive while AVWAP remains negative, consistent with a stock lacking a near-term catalyst.
The bottom line is that Prudential beat lowered estimates with real strength in U.S. annuities, PGIM flows and margins, but the headline masks a weaker trajectory. Japan's suspension is deeper, longer and now regulator-ordered, and earnings are declining year over year for the first time in several quarters. Until the February restart shows whether the Japan franchise can recover, bears have legitimate ammunition. Bulls are left relying on divestiture capital and redeployment execution.
Read our earnings preview for Prudential Financial, Inc.: https://www.earningswhispers.com/article/PRU/21613
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| 7 hours | |
| Nov-04 | |
| Nov-02 | |
| Oct-28 |
PGIM Expands Private Credit Push, Backing $680 Million Tree Line Continuation Vehicle
PRU
Benzinga Private Markets
|
| Oct-26 | |
| Oct-21 | |
| Oct-20 |
Prudential Financial Sells Prudential of Brazil, Prudential of Mexico for $4 Billion
PRU
The Wall Street Journal
|
| Oct-20 | |
| Oct-15 | |
| Oct-15 | |
| Oct-14 | |
| Oct-13 | |
| Oct-09 |
Prudential Financial's Japanese Businesses Get Suspension, Improvement Orders from Regulator
PRU
The Wall Street Journal
|
| Oct-09 |
