Grainger Beats And Raises A Third Time As Organic Growth Accelerates, But A Softer Q4 Margin Setup Tempers The Story
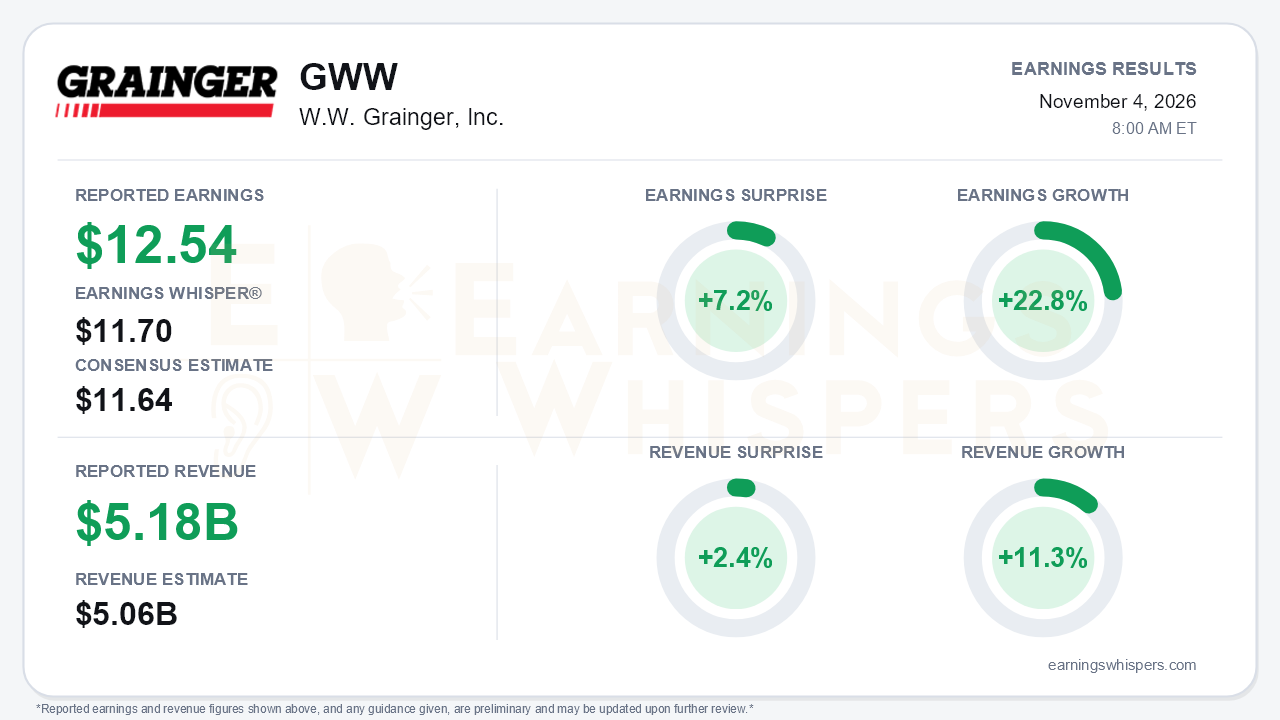
W.W. Grainger delivered the kind of quarter that is hard to argue with on the surface. Adjusted EPS of $12.54 beat the $11.64 consensus by 7.2% and cleared the $11.70 Earnings Whisper number. Revenue of $5.181 billion topped the $5.06 billion estimate by 2.4%. Earnings grew 22.8% year over year on 11.3% revenue growth. More important than the beat is the trajectory. Daily, organic constant-currency sales rose 14.9%, up from 13.7% in the second quarter and 12.2% in the first. Management also raised full-year adjusted EPS guidance for the third consecutive time, to $47.00-$48.00. That is the central takeaway: an MRO distributor of Grainger's scale is accelerating, not merely compounding.
The quality of the beat holds up well, though not every dollar came from operations. Reported diluted EPS of $12.42 rose 102.9%, but that comparison is flattered by last year's $196 million loss on the U.K. exit, so the adjusted 22.8% is the better gauge. Even within that figure, some help came from below the operating line. Diluted shares fell to 47.1 million from 47.9 million, and the adjusted tax rate dipped to 24.3% from 24.8% on additional tax credits. Part of the 90-basis-point improvement in adjusted operating margin, to 16.1%, came from shedding the lower-margin U.K. business rather than from core leverage alone. Cash generation was strong. Operating cash flow was $661 million, up from $444 million in the second quarter, and free cash flow reached $546 million, helped by capital spending falling to $115 million from $258 million a year earlier.
Beneath the headline, the two segments told different stories. High-Touch Solutions growth stepped up from 10% in the first quarter to 11.7% and then 13.8%, on double-digit volume, with every end market up and contractor and data center-linked demand standing out. Yet High-Touch gross margin slipped 30 basis points to 40.8%. Management attributed roughly 20 basis points to diesel and freight inflation tied to the Middle East conflict and about 10 basis points to project mix. In Endless Assortment, Zoro U.S. growth jumped to 25.2%, driven almost entirely by existing customers buying more. Segment operating margin reached 11.7%, with Zoro at 8.4%, up 260 basis points year over year. MonotaRO was the soft spot. Its growth decelerated to 13.6% from about 24% as earlier pre-buying reversed.
The forward picture is where the quarter becomes more nuanced. October sales are tracking around 18%, or roughly 16% excluding the government-shutdown comparison, which supports the higher 13%-14.5% full-year organic growth guide. However, the implied fourth-quarter operating margin is only about 15.5%, reflecting seasonal deleverage and elevated incentive compensation. The expected roughly 80-basis-point sequential gross margin lift to about 39.6% leans partly on supplier rebates that management said will reset in 2027, along with tariff refunds. Other margin pressures are layering in:
- The August acquisition of AI and computer-vision inventory technology from Adroit Worldwide Media, a $215 million cash outlay, adds a 10-15-basis-point operating margin drag in the fourth quarter that continues into 2027.
- January pricing remains undecided amid diesel volatility.
- A Louisville distribution center fire forced an inventory write-off, roughly offset by an IEEPA refund.
- Grainger is still operating with an interim CFO.
Management framed the incentive comp reset as a 2027 tailwind, but bears have legitimate ammunition in the rebate and refund normalization that will offset it.
Investor sentiment moved in the opposite direction from the fundamentals, slipping from essentially neutral at 0.0077 to a modestly negative -0.1063. That is a noticeable cooling, not a collapse. Price action helps explain it. Shares rose 9.2% from the open after the August report to $1,397.98 heading into the release, sitting just 0.8% below the inter-earnings high of $1,409 set on November 3. The stock is also 12.8% above its 200-day moving average and has rallied 13.1% off the late-September low. Momentum and AVWAP trend readings are positive, while the broader price trend is neutral. The stock entered earnings near the top of its range with much of the acceleration story already reflected, which raises the bar for incremental upside.
The bottom line is that Grainger delivered a clean beat, accelerating organic growth, and another guidance raise, and the call preserved a credible demand story anchored by High-Touch volume and Zoro's reacceleration. The tension lies in margins. High-Touch gross margin is under freight pressure, the fourth quarter implies a step down in profitability, and 2027 faces resets in rebates and refunds alongside new acquisition costs. With shares near their highs and sentiment cooling, the market setup is more complicated than the surprise implies.
Read our earnings preview for W.W. Grainger, Inc.: https://www.earningswhispers.com/article/GWW/21707
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Oct-28 | |
| Oct-27 | |
| Sep-23 | |
| Aug-26 | |
| Aug-19 | |
| Aug-04 | |
| Aug-04 | |
| Aug-04 | |
| Aug-03 | |
| Jul-29 | |
| Jul-21 | |
| Jul-17 |
