BillionToOne Doubles The EPS Consensus And Raises Guidance Again, But A $7.6 Million True-Up And Slowing Growth Complicate The Beat
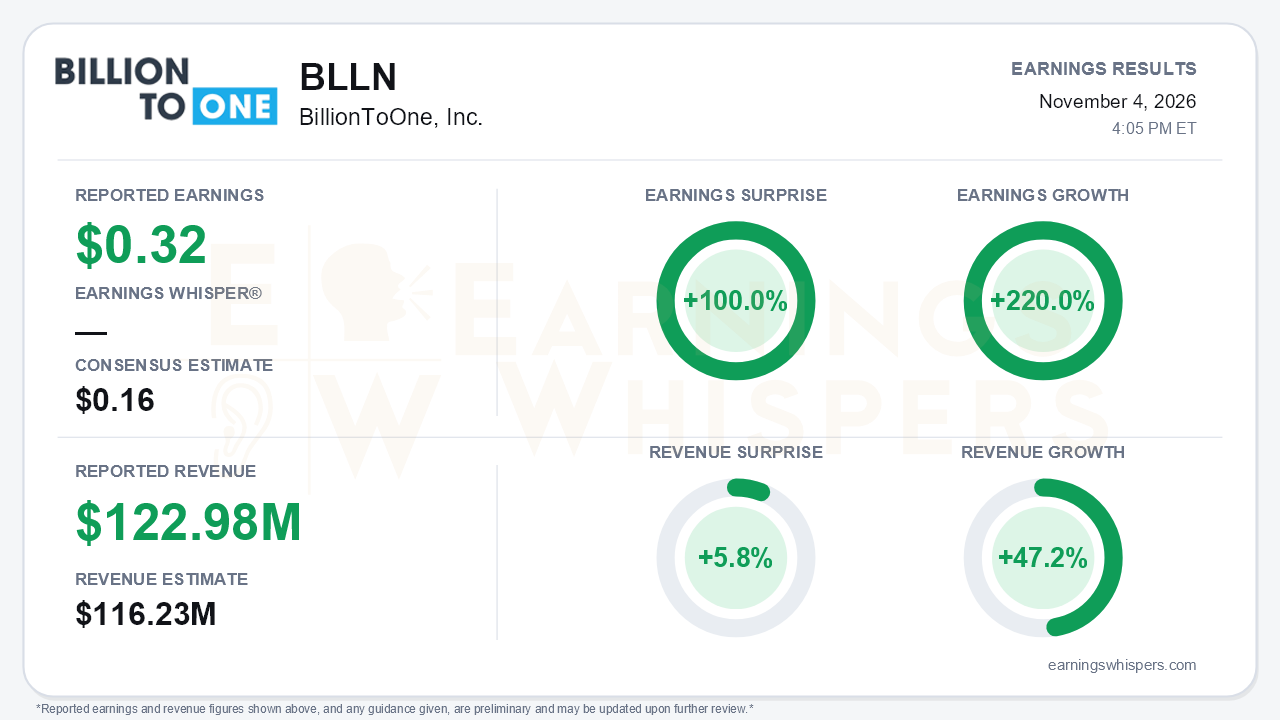
BillionToOne delivered a decisive third-quarter beat. GAAP earnings of $0.32 per share topped the $0.16 consensus by 100.0% and rose 220.0% year over year. Revenue of $122.98 million beat the $116.23 million estimate by 5.8% and grew 47.2%. Management also raised full-year 2026 revenue guidance for the third straight time, to $460 million to $470 million from $450 million to $465 million. That implies 51% to 54% growth. The central tension is that the guidance keeps ratcheting higher while the growth rate keeps stepping lower. The trajectory now depends on catalysts that have not yet shown up in reported numbers.
The quality of the beat deserves scrutiny.
- **True-up and pricing.** Revenue included a $7.6 million true-up from resolving held claims with one payer, up from $2.8 million in Q2. Average selling price rose to $589 from $551, but excluding the true-up it was $552, essentially flat sequentially. Ex-true-up revenue grew 8% quarter over quarter, matching Q2's pace rather than improving on it.
- **Below-the-line help.** Income from operations was $11.0 million. Net income of $17.4 million was lifted by $4.9 million of interest income on a cash pile that now stands at $562 million, plus a $1.5 million favorable change in the fair value of the term loan.
- **Distorted comparison.** The year-ago diluted EPS was calculated on a much smaller pre-IPO share base of roughly 15.6 million diluted shares, versus 53.7 million now. That flatters the 220% growth figure.
None of this makes the profit illusory. Operating margin recovered to 9% from 5% in Q2, adjusted EBITDA margin rose to 18% from 15%, and free cash flow improved to $8.6 million from $5.1 million. But the headline EPS overstates the step-change in core earnings power.
The call made the deceleration plain:
- **Revenue growth:** 84% in Q1, 64% in Q2, 47% in Q3.
- **Test volume growth:** 44%, 35%, 25% over the same quarters.
- **Oncology:** 96%, down from 176% in Q2.
- **Prenatal:** about 42%, down from 56%.
Some of this is simply tougher comparisons. Management did not lean on that explanation alone, however. It acknowledged that independent-clinic prenatal growth is maturing, so re-acceleration depends on health system wins with 12- to 24-month sales cycles that sit outside guidance.
Margins tell a similar story. Gross margin held near 71% but is below Q1's 73%. Cost per test climbed from $152 to $161 to $169 on oncology mix and launch costs. A bright spot is oncology economics: segment gross margin reached 45%, and Northstar Response is at gross-margin breakeven before any Medicare coverage.
The forward story is richer than the trend lines:
- **Northstar Clear.** The company's tissue-free, pan-cancer MRD test launches December 15. Management said it will not throttle volume and expects it to be gross-margin positive at scale.
- **Clinical evidence.** A peer-reviewed head-to-head study showed Northstar Response agreeing with the leading tumor-informed assay in 94% of sequential pairs. A prospective Green Journal study validated Unity Fetal Risk Screen with 94.4% sensitivity and 99.5% specificity.
- **Pricing.** Proposed lab fee schedule rates would lift carrier screening roughly 112% and Response about 30%.
- **Health system pipeline.** More than 20 systems are now sized at 2,000 to 5,000 tests per quarter each, up from 1,000 to 3,000 in Q2.
Bears have legitimate ammunition, though:
- **Medicare timing.** MolDX coverage for Response has slipped from 'possibly earlier than anticipated' in Q1 to 'timing uncertain.'
- **Unreimbursed MRD.** MRD will carry low prices until reimbursed, which threatens further gross-margin dilution.
- **Pricing and competition.** A proposed aneuploidy rate cut partly offsets the favorable codes. A LabCorp-owned competitor is also entering fetal recessive testing.
- **Working capital.** Accounts receivable have more than doubled since December to $88.3 million.
Guidance excludes Q4 true-ups. It implies fourth-quarter revenue of roughly $119 million to $129 million, which brackets Q3's ex-true-up base of about $115 million.
Investor sentiment swung sharply heading into the report, from -0.39 after the August release to +0.38. That is a genuine reversal from skepticism to optimism, which raises the bar for this print. The stock's path has been volatile:
- **Since the last report:** Shares ended the pre-report snapshot at $110.45, up 5.0% from the open after the last report.
- **Range:** That is 25.6% above the August 18 low of $87.96 but 13.5% below the September 24 high of $127.72. Much of the late-summer rally has already been given back.
- **Trend:** Shares sit 14.4% above the 200-day moving average, and the AVWAP trend remains positive. The broader trend is intact even if momentum has cooled.
The bottom line is that BillionToOne delivered a clean headline beat, another guidance raise, and real progress on profitability and clinical evidence. Underneath, a one-time true-up, interest income, and a reshaped share count flatter the quarter, and growth continues to decelerate across volume, prenatal, and oncology. The investment case is shifting from the momentum of the existing franchise to execution on Northstar Clear, health system adoption, and Medicare coverage whose timing management can no longer pin down. With sentiment now firmly positive and shares well off their highs, the next leg depends on those catalysts converting into revenue rather than on another raise.
Read our earnings preview for BillionToOne, Inc.: https://www.earningswhispers.com/article/BLLN/21990
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Oct-29 | |
| Oct-27 | |
| Oct-27 | |
| Oct-21 | |
| Oct-14 | |
| Oct-07 | |
| Sep-23 | |
| Sep-02 | |
| Sep-01 | |
| Aug-18 | |
| Aug-06 | |
| Aug-06 |
