Arcutis Misses Badly On Earnings As A Spending Surge Overshadows A ZORYVE Revenue Beat And Higher Guidance
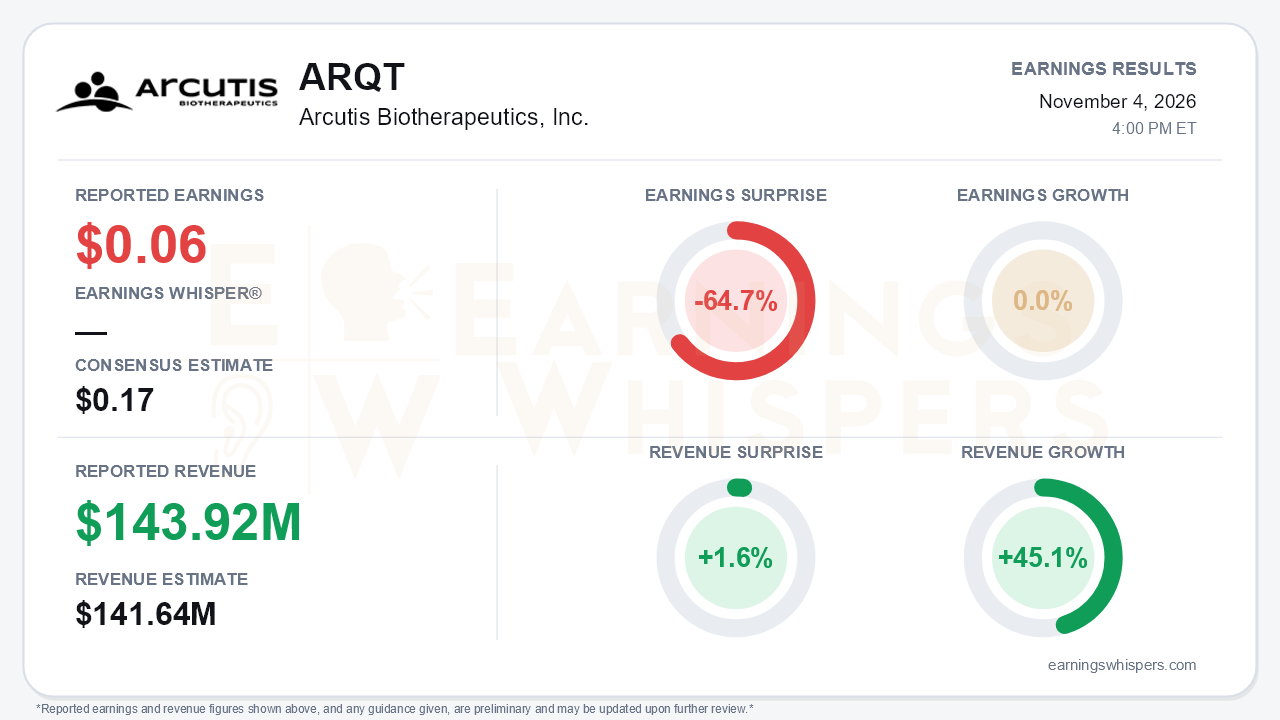
Arcutis Biotherapeutics delivered two different stories in its third quarter. ZORYVE kept growing: revenue of $143.92 million beat consensus by 1.6% and rose 45.1% from a year ago, and management raised full-year guidance for the second straight quarter. Earnings went the other way. Diluted EPS of $0.06 missed the $0.17 consensus by 64.7% and was flat year over year, because the company sharply increased commercial spending. That is the central tension. Arcutis is deliberately giving up near-term profit to set up growth in 2027, and it asked investors to accept that trade without saying how large the 2027 payoff should be.
The miss came from spending decisions, not from weak sales. SG&A climbed to $99.6 million from $62.4 million a year ago and $82.1 million in the second quarter. The increase paid for the Simone Biles "Skin to Believe In" awareness campaign, an expanded dermatology sales force and a new primary-care and pediatric sales team. As a result, net income fell to $8.8 million from $15.0 million in the second quarter and $17.4 million in the fourth quarter of 2025. That happened even though revenue rose by about $14 million sequentially. Cost of sales stayed modest at $12.5 million, so gross economics are intact. The pressure sits entirely in operating expenses. Cash generation held up better than reported earnings. Operating cash flow reached $18.9 million, compared with $12.6 million in the second quarter and $2.2 million in the first. Cash and marketable securities rose to $259.8 million.
Beneath the top line, the growth picture is solid but changing in character. Year-over-year growth has slowed from 65% in the first quarter to 59% in the second and 45% now. Management attributed that largely to tougher comparisons. The more important shift involves gross-to-net deductions, which reduce list price to the net price the company actually collects. These deductions have stabilized in the low 50s, and the call indicated little further upside from that source. Future growth therefore depends on prescription volume. On that front the data were encouraging:
- Quarterly prescriptions topped 300,000, up from more than 280,000 in the second quarter.
- Every formulation grew, led by the foam at $75.1 million and the 0.3% cream at $37.8 million.
- Management said the expanded dermatology sales force began showing an effect in September demand, and that adherence and refills improved.
Analysts still pressed on a mid-year slowdown in prescriptions, and the primary-care and telehealth efforts remain largely unproven.
The guidance raise was meaningful in context but modest in scale. The new full-year range of $535 million to $545 million compares with $525 million to $540 million previously and $455 million to $470 million originally. The latest increase was characterized as in line with estimates. The more consequential forward signals were about expenses and 2027:
- SG&A is guided to stay near the third-quarter level in the fourth quarter.
- Operating leverage, meaning profit growing faster than revenue, has been pushed out to late 2027 or 2028.
- The CFO said 2027 growth will "inflect," but management declined to offer even a preliminary 2027 outlook.
Skeptics have legitimate ammunition here, because the spending is concrete while the payoff is a promise. The pipeline provides several near-term checkpoints:
- Phase 2 vitiligo results are due by year-end. This is a small, 20-patient open-label study, so the readout is binary.
- The FDA action date for the infant atopic dermatitis approval is February 23, 2027.
- Hidradenitis suppurativa data are expected in the first quarter of 2027.
- A new Phase 3 trial of the 0.3% cream in moderate-to-severe atopic dermatitis has started.
- ARQ-234 has moved into the multiple-ascending-dose portion of its Phase 1 trial.
The market setup heading into the report was stretched relative to the earnings outcome. Shares closed at $32.00 before the release. That was 9.6% above the opening price after the August report, 26.5% above the 200-day moving average and just 3.9% below the 52-week high of $33.30 set on October 20. The stock had rallied about 38.5% from its September 15 low of $23.10, so it entered earnings near the top of its range. Investor sentiment moved the other way. It went from -0.21 to -0.34, a moderate deterioration within already negative territory, suggesting skepticism was building even as the price climbed. The Earnings Whispers trend signals were uniformly positive going in, which reflects how strongly price and sequential growth had been running, not how the market will digest a large earnings miss.
The bottom line is that Arcutis' commercial engine is working: prescriptions, revenue, cash flow and guidance all moved higher. Meanwhile, the profit line is being sacrificed to an expensive bet on 2027 acceleration that management has not quantified. With growth now dependent on volume and margins deferred, the investment case rests on whether the Biles campaign and the sales-force expansion visibly lift prescriptions in the coming quarters. A stock trading near its highs with souring sentiment leaves little room for that evidence to arrive late.
Read our earnings preview for Arcutis Biotherapeutics, Inc.: https://www.earningswhispers.com/article/ARQT/21788
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 5 hours | |
| Oct-28 | |
| Oct-27 | |
| Oct-27 | |
| Oct-21 | |
| Oct-09 | |
| Oct-06 | |
| Oct-02 | |
| Sep-29 | |
| Sep-17 | |
| Sep-04 | |
| Sep-04 | |
| Sep-02 | |
| Aug-07 |
