Accuray's GAAP Profit Is An Accounting Artifact; Orders Halved And Backlog Kept Shrinking
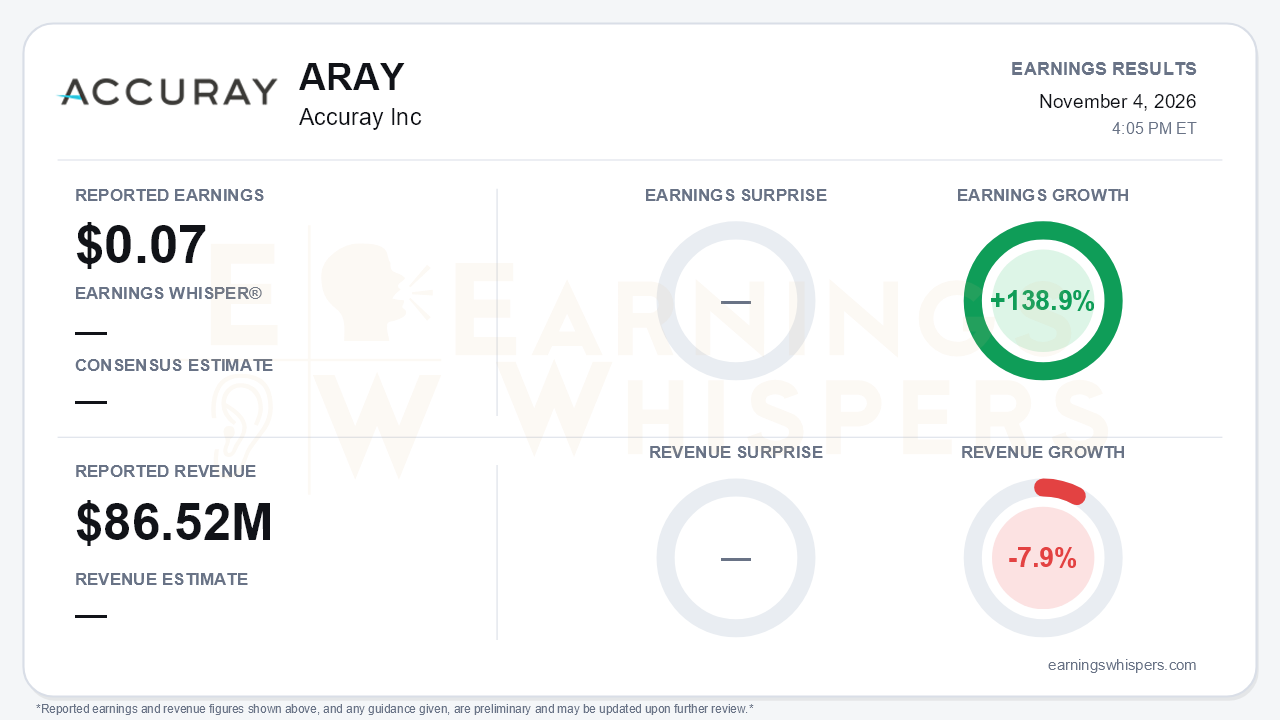
Accuray (NASDAQ: ARAY) reported fiscal first-quarter GAAP earnings of $0.07 per share, a 138.9% improvement from the prior year's loss. Revenue fell 7.9% to $86.52 million. Neither EPS nor revenue had a consensus estimate to measure against. The headline profit says very little about the operating business. It came from a $59.6 million non-cash gain on extinguishment of debt tied to the July TCW refinancing, partly offset by a $35.4 million non-cash goodwill impairment. Excluding both items, Accuray lost $14.0 million, or $0.10 per share, compared with a loss of $0.18 a year earlier. That is a real improvement, but it is still a loss. The central tension is that cost cutting and service pricing are working, while the product franchise that drives future revenue weakened sharply.
The cost side of the quarter was the strongest part. Operating expenses excluding the impairment fell 29% to $27.2 million, with declines in research and development, selling and marketing, and administrative spending. Management credited transformation initiatives with roughly $13 million of year-over-year cost and margin improvement. Adjusted EBITDA swung to a positive $2.5 million from negative $4.1 million.
Service was the other bright spot:
- Service revenue rose 4% to $59.2 million, or 5% in constant currency.
- Service gross margin reached 35.1%, up from 33.9% a year ago and well above the roughly 26% to 27% posted in the second and third quarters of fiscal 2026.
- Overall gross margin improved to 30.1% from 28.8%.
That mix gain partly reflects product weakness, not only service strength. Product revenue dropped 26% to $27.3 million on just 12 units. Product gross margin slipped to 19.4% from 20.8%, hurt by poor fixed-cost absorption and tariffs.
The order book is where bears have legitimate ammunition. Gross product orders fell to $19.8 million, about half the $39.6 million of a year ago. The sequential trend is just as clear:
- Book-to-bill was 0.7, against management's stated healthy level of 1.2.
- Gross orders have declined from $66 million two quarters ago, to $49 million, to $38 million, to $19.8 million now.
- Net orders were negative $13.2 million, meaning cancellations and other backlog reductions exceeded new bookings.
- Backlog fell to $272 million, down about 31% year over year and from $383 million, $356 million and $313 million at the prior three quarter-ends.
Management acknowledged that product orders and revenue "did not meet our expectations." It shifted its message to execution and converting pipeline activity from ASTRO into orders. It also flagged possible further goodwill impairments and continued China headwinds. Tariffs and inflation cost about 3.3 points of service margin. Notably, no analysts asked questions on the call.
Accuray still offers no formal revenue or adjusted EBITDA guidance. That has been the case since guidance was withdrawn after the fiscal 2026 second-quarter cut. Management effectively reaffirmed its qualitative outlook for service growth, service margin and spending discipline. It offered no quantitative path for product recovery.
The catalysts are real but longer-dated:
- The RaySearch letter of intent became a definitive agreement for online adaptive therapy, starting with Radixact and adding CyberKnife later.
- The Samsung NeuroLogica imaging collaboration advanced.
- Eight-year PACE-A data showed CyberKnife-heavy SBRT matching prostatectomy on biochemical control (94.8% vs. 94.1%) with better preservation of sexual function.
These strengthen the clinical and product story. None will rescue near-term orders on its own.
The balance sheet improved on paper. Long-term debt fell to $95.0 million from $146.4 million after the fair-value remeasurement. Stockholders approved the $40 million debt-for-preferred exchange after quarter end, and stockholders' equity rose to $53.1 million. Cash, including restricted cash, reached $50.4 million. However, that increase was only $1.6 million despite the $15 million TCW investment and a $17.4 million drop in receivables, which suggests underlying cash consumption remains meaningful. Interest expense also rose to $11.8 million from $8.1 million.
The market setup reflects a distressed equity. Shares opened at $0.31 after the August report, below the current 200-day moving average of $0.36. Completing the TCW exchange still required a reverse stock split. Investor sentiment and current price data were not available for this report.
The bottom line is that Accuray's positive GAAP EPS is a refinancing gain, not a turnaround in earnings power. The real progress is in cost structure, service margins and leverage, and it is credible. But orders have fallen for three straight quarters, net orders turned negative and backlog is shrinking, so the product business is eroding faster than cost savings can compensate. Until bookings recover toward management's 1.2 book-to-bill benchmark, the leaner model is supporting a smaller company, not a growing one.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Oct-30 | |
| Oct-21 | |
| Oct-06 | |
| Sep-28 | |
| Sep-27 | |
| Sep-11 | |
| Aug-20 | |
| Aug-19 | |
| Aug-19 | |
| Aug-12 | |
| Aug-05 |
