A.k.a. Brands' Sales Reaccelerate, But Freight And Relocation Costs Force An EBITDA Guidance Cut
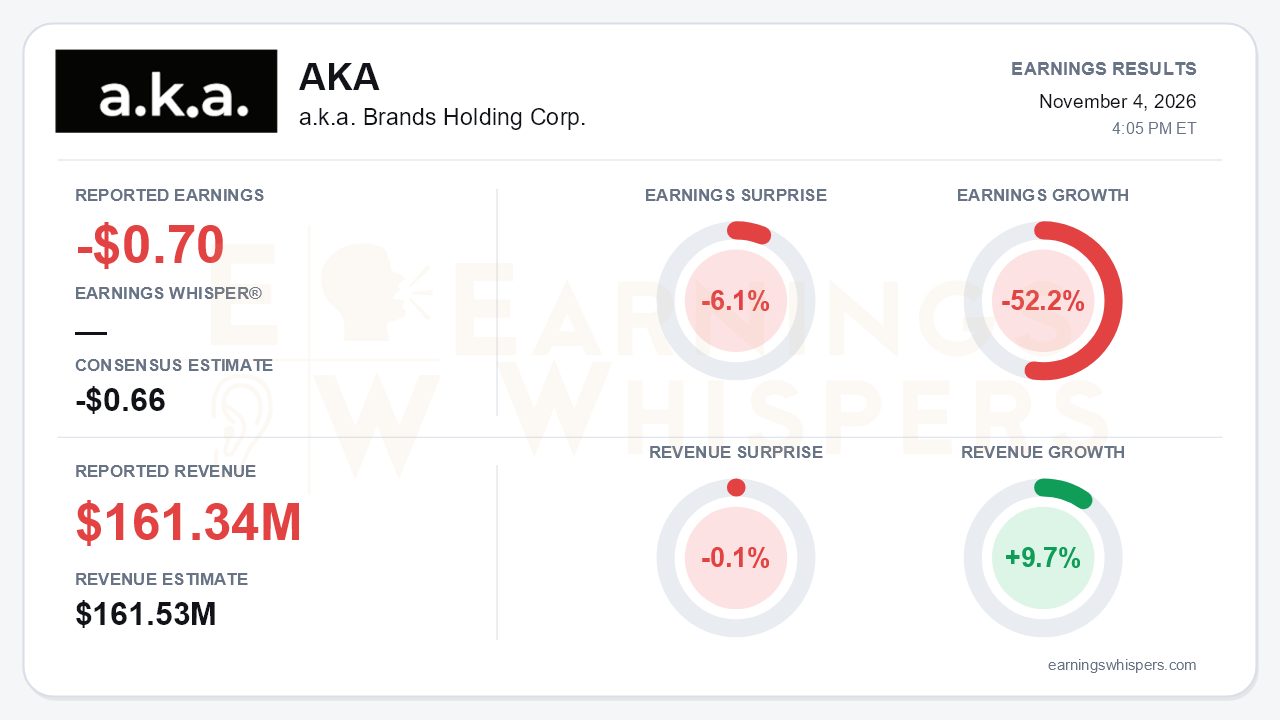
a.k.a. Brands delivered its strongest top-line quarter in some time, but profits did not keep pace, and that gap is the central tension. The company reported a third-quarter loss of $0.70 per share, missing the consensus estimate of a $0.66 loss by 6.1%. Earnings fell 52.2% year over year as the GAAP net loss widened to $7.7 million from $5.0 million. Revenue of $161.34 million rose 9.7%, a sharp acceleration from a flat second quarter and 3% growth in the first quarter, though it came in essentially on top of the $161.53 million consensus, a 0.1% shortfall. The demand story improved. The cost story got worse.
The quality of the miss deserves scrutiny because much of it came from items management treats as non-recurring. Gross margin expanded about 100 basis points to 60.1%, ahead of the roughly 59% level signaled on the second-quarter call. That gain came despite about 140 basis points of air freight pressure and was driven by full-price selling at the streetwear brands, particularly Culture Kings. Below gross profit, selling expenses jumped to 32.4% of sales from 29.4%, largely because of $5.3 million in one-time costs to relocate the distribution center to Ohio. Management had guided to roughly $3 million. Adjusted EBITDA, which excludes those charges, rose 16.6% to $8.2 million, a 5.1% margin and the third straight quarter of double-digit growth. Bulls can point to that figure. Bears can note that the relocation overrun, higher other expense and an absence of operating leverage at the GAAP line are real costs to shareholders, not accounting noise.
Beneath the headline, the operating metrics moved meaningfully in the right direction:
- **U.S.:** Sales grew 14%, compared with 2.1% in the second quarter and 3.2% in the first. Management called it the first double-digit U.S. quarter since the sourcing overhaul.
- **Orders and customers:** Orders rose 12.8%, versus a 0.5% decline last quarter, and trailing active customers grew 8.8%, double the prior quarter's pace.
- **International:** Rest of World sales climbed 79%, with Princess Polly's U.K. business roughly four times its year-ago size.
- **Australia and New Zealand:** The decline narrowed to 6.7% from 13%.
The soft spot was the basket. Average order value slipped to $76 from $78 as consumers avoided adding items, which means the growth is coming from more transactions rather than bigger ones.
The guidance is where the setup becomes more complicated than the revenue line implies. Management cut full-year adjusted EBITDA guidance to $29-$30 million from the $30-$32 million it had reiterated on the prior two calls. That reverses part of an earlier increase from $27-$29 million. Full-year sales guidance was tightened to $626-$632 million, a slightly lower midpoint, and the fourth-quarter outlook calls for $172-$178 million in sales and $7-$8 million in adjusted EBITDA. On the sales line, that outlook is broadly in line with prior expectations. On profitability, it is not. Freight is now expected to cost about $6 million of EBITDA in the second half and to shave an additional 80 basis points off fourth-quarter gross margin, which is guided to a 57% midpoint. Interest and other expense guidance rose to $23-$25 million from $16-$18 million. The fourth quarter also faces tougher U.S. comparisons.
The balance sheet adds another layer of caution. Total debt fell 8.5% year over year to $101.9 million. Even so, cash dropped to $15.6 million from $21.1 million last quarter, and net leverage edged up to 3.5x from 3.37x. Inventory is now roughly flat year over year after running 13.6% lower in the second quarter. Accounts payable has climbed to $50.9 million from $31.2 million at year-end, flattering operating cash flow. Trimmed capital spending guidance of $16-$17 million looks partly like cash preservation.
The catalyst list did broaden:
- **Princess Polly:** A dedicated German site launches this quarter as the start of a European push. The brand has 15 U.S. stores, two more planned in the fourth quarter and at least six signed leases for 2027.
- **Petal & Pup:** Wholesale distribution is expanding across Dillard's full fleet, plus Urban Outfitters, bloomingdales.com and international partners.
- **Culture Kings:** The Puerto Rico store, opening in late December, is its first new U.S. location since 2022.
- **Ohio distribution center:** Management expects faster delivery and lower shipping costs from 2027, which makes this year's overrun easier to look past if that payoff materializes.
Investor sentiment improved into the report, rising to 0.36 from 0.26. That is a moderate move that left expectations positive but not euphoric. The stock has not reflected that optimism. Shares at $10.04 were down 1.8% from the open after the August report and about 14% below the inter-earnings high of $11.68 set on August 20. They sat just 4% above the October 30 low of $9.65. The Earnings Whispers trend readings are mixed: sequential growth is positive, while price and AVWAP remain negative. The stock entered the print near the bottom of its range, which tempers how much disappointment was priced in for a guidance cut.
The bottom line is that a.k.a. Brands showed its turnaround is producing genuine demand, with U.S. growth, order counts and customer gains all accelerating. However, freight inflation, an over-budget relocation and rising financing costs are absorbing the benefit. The investment case now hinges on whether 2027 delivers the shipping savings and store and wholesale growth management is promising before thin cash and elevated leverage become a larger constraint.
Read our earnings preview for a.k.a. Brands Holding Corp.: https://www.earningswhispers.com/article/AKA/22011
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Oct-28 | |
| Oct-21 | |
| Aug-06 | |
| Aug-05 | |
| Aug-04 | |
| Jul-22 | |
| Jun-10 | |
| May-21 | |
| May-13 | |
| May-12 | |
| May-12 | |
| May-11 | |
| Apr-28 |
