Agilon Health Swings To A $1.97 Profit And Lifts EBITDA Guide Again, But One-Time Catch-Ups And A Softer 2027 Tailwind Temper The Beat
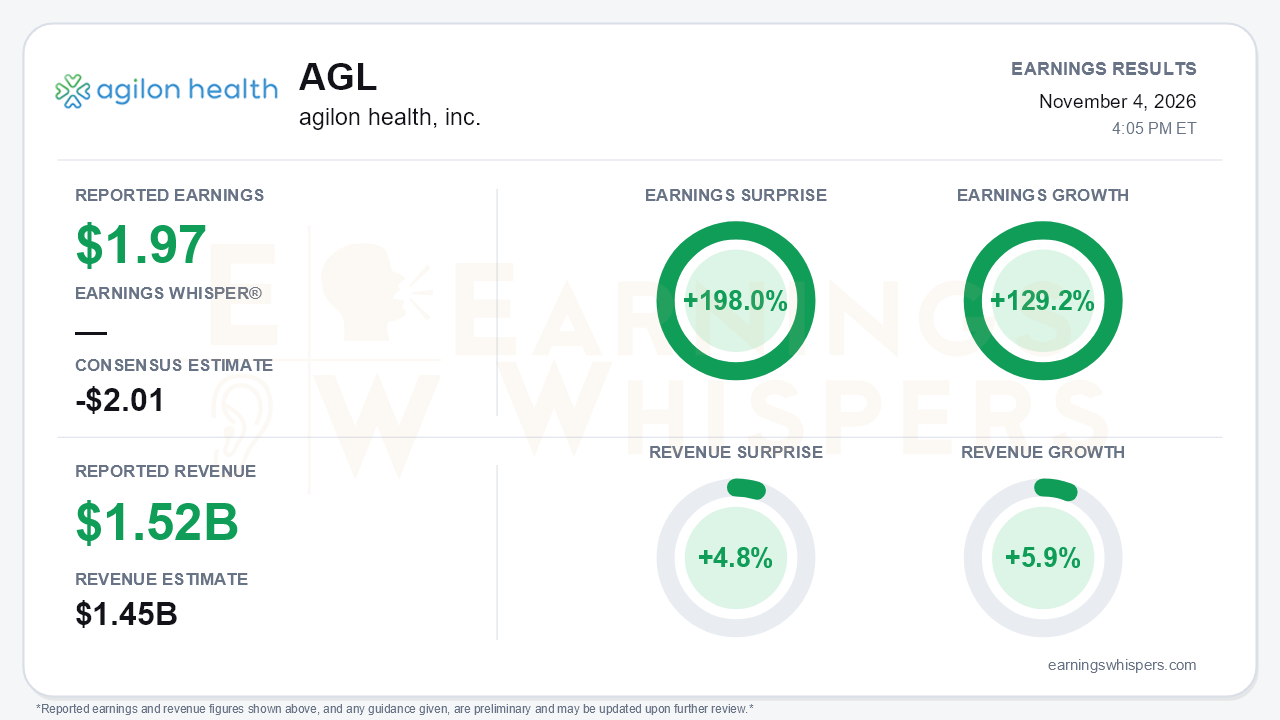
agilon health (NYSE: AGL) delivered its third consecutive beat-and-raise. The company earned $1.97 per share in the third quarter against a consensus estimate calling for a loss of $2.01, a 198.0% surprise. Revenue of $1.519 billion topped the $1.45 billion consensus by 4.8%. Earnings grew 129.2% year over year as the company swung from a $110 million net loss to $35 million of net income, while revenue rose 5.9% despite a shrinking member base. Adjusted EBITDA of $64 million compared with management's own guide of roughly breakeven and negative $91 million a year ago. Full-year adjusted EBITDA guidance jumped to $145 million to $155 million from $75 million to $95 million. That guide began the year at breakeven. The turnaround is no longer theoretical. The question is how much of this quarter's strength repeats.
The quality of the beat deserves scrutiny. The medical services expense ratio improved to 88.5% from 104.0%, but the release states that the figure includes favorable claims development from the first half of 2026. On the call, management itemized several prior-period or catch-up contributors:
- $14 million of prior-year development
- a $23 million year-to-date risk-adjustment true-up
- $12 million of first-half cost-trend favorability
- $7 million of prior-year ACO contribution
Together those items account for a large share of the gap between actual adjusted EBITDA and the breakeven guide. Roughly $4 million of expenses also simply slid into the fourth quarter. GAAP results drew help from $17.5 million of other income, while stock-based compensation more than doubled to $18.9 million. The balance sheet tells a similarly mixed story. Year-to-date operating cash flow turned positive at $16 million versus a $85 million outflow, but receivables swelled to $1.02 billion from $674 million at year-end.
Beneath the catch-ups, the operating trend still looks genuinely better. Revenue grew while Medicare Advantage membership fell 10% year over year, to 454,000, reflecting stronger burden-of-illness performance, payor contracting and pricing. Membership has also turned higher sequentially, up from 426,000 in the first quarter and 437,000 in the second. Management restated 2025 cost trend down to 5.8% and moved first-quarter 2026 trend from 7.4% to the low-6% range. Third-quarter trend is still booked conservatively in the low-7% range, leaving room for further favorable development. Guidance for ACO REACH EBITDA rose again, to $40 million to $45 million, and the year-end cash floor was lifted to at least $175 million from $125 million. Tone shifted accordingly, moving from turnaround framing to CEO Tim O'Rourke's message of performance at scale.
The forward picture is where bears have legitimate ammunition. The raised guide still implies a fourth-quarter adjusted EBITDA loss of roughly $32 million to $42 million after $187 million over nine months. That is a steeper seasonal drop than history. Management also said the 2027 payor-contracting benefit will be more modest than 2026's $127 million because about 80% of contracts have already been repriced, and it had earlier flagged a smaller risk-adjustment tailwind next year. Against that, management is planning for growth again:
- three MSSP expansions covering about 50,000 members with existing partners
- ACO membership expected to rise 40% to 50%, to about 160,000, in 2027
- a reopened new-market pipeline targeting 2028 full-risk starts
The shift from ACO REACH to MSSP and LEAD, however, introduces model-change risk.
The market setup is more complicated than the surprise implies. Shares closed at $87.79 ahead of the report, down 12.7% since the open following the second-quarter release. They had peaked at $103.88 in August before sliding to $72.16 in late September. The stock entered earnings roughly midway between those levels, 15.5% below the high, yet still 34.2% above its 200-day moving average. Investor sentiment edged up only slightly, from 0.041 to 0.064, and remains barely positive. That suggests the market has priced in recovery without much enthusiasm. The Earnings Whispers trend readings are mixed, with momentum positive while AVWAP remains negative.
The bottom line is that agilon proved again that its repricing and cost discipline can produce real profits, and the steady upward march in guidance is earned. But a meaningful portion of the third-quarter upside was backward-looking, the fourth-quarter guide implies a sharp step down, and management itself expects 2027's biggest tailwinds to fade. The next leg of the story depends less on additional catch-ups and more on whether ACO expansion and renewed market growth can replace them.
Read our earnings preview for agilon health, inc.: https://www.earningswhispers.com/article/AGL/21772
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 15 hours | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Oct-27 | |
| Oct-05 | |
| Sep-30 | |
| Sep-23 | |
| Sep-15 | |
| Sep-10 | |
| Aug-27 | |
| Aug-20 | |
| Aug-11 | |
| Aug-05 | |
| Aug-05 |
