Adaptive Biotechnologies Reaches Profitability Early As MRD Momentum Overshadows A Genentech-Distorted Revenue Decline
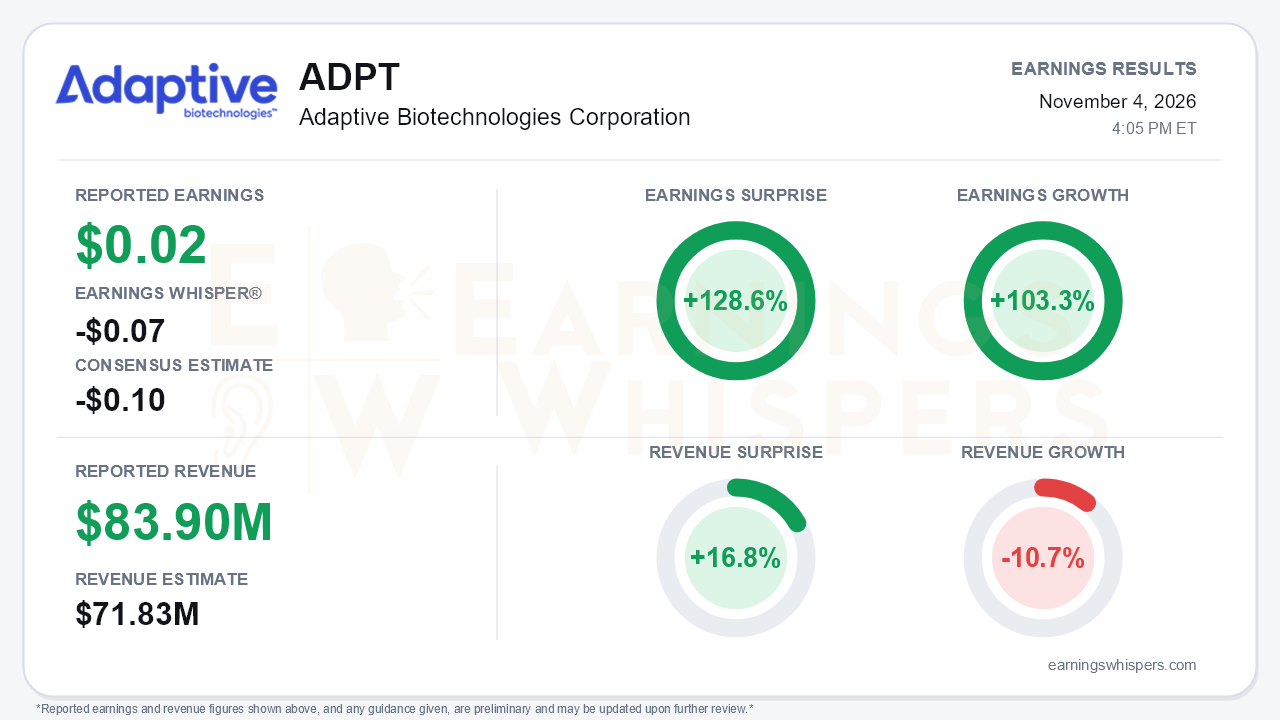
Adaptive Biotechnologies delivered a clean beat on the numbers that mattered most. The company reported third-quarter earnings of $0.02 per share, against a consensus estimate of -$0.10 and an Earnings Whisper number of -$0.07, a 128.6% surprise. Revenue of $83.9 million topped the $71.83 million consensus by 16.8%. Earnings grew 103.3% year over year, while revenue fell 10.7%. That revenue decline is mostly an artifact. The year-ago quarter included Genentech Agreement revenue that did not recur. Excluding it, revenue rose 39%. The central development is that Adaptive reached total-company profitability ahead of its exit-2026 target. Adjusted EBITDA was $14.3 million and free cash flow was $7.7 million, with the core MRD franchise carrying the result.
The quality of the beat still deserves scrutiny. GAAP results showed a $0.5 million operating loss. Net income of $2.8 million depended on $3.8 million of interest and other income and on interest expense falling to $0.5 million from $3.0 million. That decline followed the extinguishment of the revenue interest liability, which was replaced by roughly $335 million of convertible notes. The year-over-year GAAP comparison is also muddied by the prior-year Genentech revenue. The year-ago period posted $9.5 million of net income and $0.06 per share. Excluding Genentech, it would have been a $24.2 million net loss. Immune Medicine's positive $3.2 million adjusted EBITDA rested on a Pfizer rheumatoid arthritis target-discovery milestone, which is lumpy by nature. Management does not expect GAAP profitability in the fourth quarter or for the full year, and it has no visibility into fourth-quarter milestones. Investors should treat the third quarter as proof that the model can be profitable, not as a new run rate.
The MRD business is where the story is unambiguously strong:
- **Revenue:** MRD revenue rose 28% to $72.6 million, or 44% excluding milestones.
- **Profitability:** Segment adjusted EBITDA more than doubled to $15.1 million from $7.0 million.
- **Volume:** clonoSEQ tests rose 46% to 39,587, up roughly 10% sequentially, with DLBCL up about 20% quarter over quarter.
- **Guidance:** Full-year MRD revenue guidance was raised for the third straight time, to $276-$286 million from $268-$278 million. The range has climbed every quarter from an initial $255-$265 million. The clinical volume growth outlook rose to about 42% from 38-40%.
- **Margins:** Sequencing gross margin reached 73%, up from 70% in the first quarter and 66% for fiscal 2025, moving toward the 75% long-term target.
- **Pharma:** Backlog rose to about $270 million, up 34%. Pharma growth expectations jumped to roughly 25% from the 11-12% held earlier in the year.
- **Adoption:** Ordering clinicians climbed to about 5,600. Blood-based testing reached 51% of volume, and community share reached 37%.
One caveat on guidance: by Earnings Whispers' assessment, the raise moved the outlook closer to analyst estimates rather than clearly above them.
Pricing is the soft spot, and bears have legitimate ammunition here. Realized ASP of $1,380 was flat sequentially and up only 3% year over year. That is a sharp slowdown from 11% growth in the first quarter and 17% in fiscal 2025. Medicare testing beyond the four-test bundle is compressing realized price, putting the roughly $1,400 full-year target at timing risk. CMS's preliminary 2027 PLA rate also relied on what management calls erroneous data, and the company expects it to be corrected before final rates.
The offsets are meaningful:
- **Clinical tailwinds:** The NCCN established a dedicated myeloma MRD framework that names clonoSEQ, prefers 10^-6 sensitivity, and supports annual testing during maintenance. The International Myeloma Working Group's first definition of cure requires sustained MRD negativity at one-in-a-million sensitivity.
- **Reimbursement:** Adaptive submitted a MolDX technical assessment seeking an additional bundle of five maintenance tests. Management expressed growing confidence in its $1,700-$1,800 ASP target.
- **Corporate:** The Immune Medicine separation path, advised by Morgan Stanley, is due by year end.
A minor reconciliation note: the release cites $400.2 million in cash and securities, while the call referenced roughly $386 million. The difference appears to be the $13.8 million held by Digital Biotechnologies.
Investors had already moved ahead of the report. Earnings Whispers sentiment swung from -0.17 to +0.19, a meaningful shift from mildly negative to modestly positive. Shares were at $25.80 before the release, up 16.2% from the open after the July report and 31.2% above the 200-day moving average. However, the stock was also 16.1% below its October 6 52-week high of $30.74, having given back a substantial part of that run. The Earnings Whispers trend signals are largely positive, with sequential growth, momentum, and AVWAP favorable while price trend is neutral. The market setup is more complicated than the surprise implies: expectations have risen, and the pullback from the high suggests investors want more than a milestone-aided quarter.
The bottom line is that Adaptive's core MRD engine is accelerating on volume, margin, and guidance, and new myeloma guidelines strengthen the long-term case for clonoSEQ. The headline profit, however, leaned on interest income and a pharma milestone, and ASP has stalled. Reimbursement outcomes from MolDX and CMS, along with the Immune Medicine separation, will determine whether early profitability becomes durable.
Read our earnings preview for Adaptive Biotechnologies Corporation: https://www.earningswhispers.com/article/ADPT/21769
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Oct-27 | |
| Oct-14 | |
| Oct-09 | |
| Sep-25 | |
| Sep-17 | |
| Sep-01 | |
| Aug-24 | |
| Jul-30 | |
| Jul-29 | |
| Jul-29 | |
| Jul-09 | |
| Jun-30 |
