ADMA Biologics Beats On ASCENIV Acceleration And Margin Strength, But Floor-Level Revenue Guidance And Slower Cash Conversion Temper The Quarter
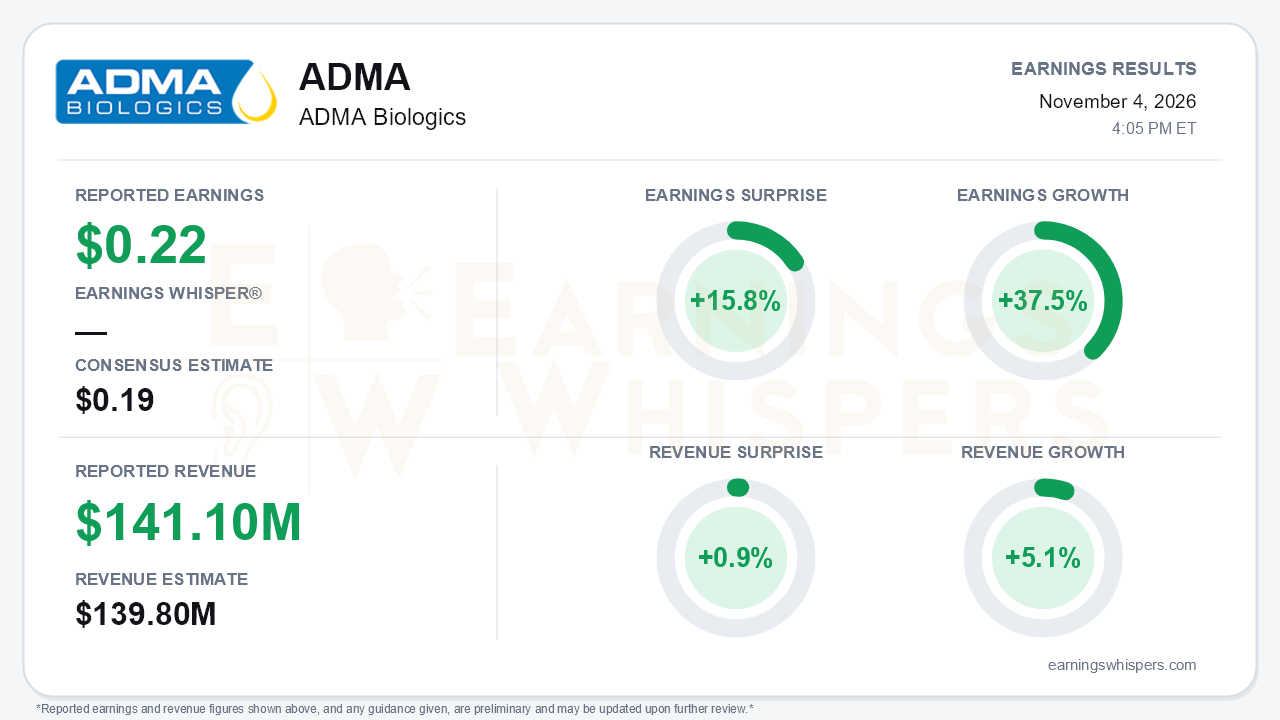
ADMA Biologics delivered the kind of earnings quarter its skeptics had stopped expecting. Third-quarter earnings of $0.22 per share beat the $0.19 consensus by 15.8% and grew 37.5% year over year, while revenue of $141.1 million edged past the $139.8 million estimate by 0.9% and rose 5.1%. That revenue growth is a clear acceleration from the 2.4% pace of the first nine months. The engine was ASCENIV, the company's specialty immune globulin, whose growth reaccelerated to 31% from 24% in the second quarter. The central tension is that management raised its earnings floors but held revenue guidance only at the bottom of its prior range. Earnings Whispers characterizes that as a guidance reduction in line with estimates, even as the profit outlook moved higher.
The headline revenue figure understates the shift in the business mix. ASCENIV revenue reached $124.7 million, up 21% sequentially. BIVIGAM fell 35% to $15.4 million, and intermediates and other products collapsed to $0.9 million from $15.0 million a year earlier. That mix shift is exactly why profitability looks so different. Gross margin reached 71%, compared with 69% in the second quarter and 56% a year ago, helped by ASCENIV mix and yield-enhanced manufacturing. Adjusted EBITDA rose 25% sequentially to $77.3 million, and adjusted EPS was $0.23. Per-share figures also benefited from aggressive buybacks. Basic share count fell to roughly 224 million from nearly 239 million a year ago, after ADMA repurchased 16.5 million shares, or about $181 million, year to date.
The call supported the demand story. Management cited a record prescriber count, broader new patient starts, stable payer access, and ASCENIV pull-through that continued into the fourth quarter. The company will present real-world data at ACAAI on 127 medically complex primary immunodeficiency patients. The analysis showed statistically significant reductions in infection-related hospitalizations and antibiotic use after patients started ASCENIV. That data should reinforce ASCENIV's positioning in later-line patients. However, the call also revealed some softening at the edges:
- Management now frames full-year ASCENIV growth at roughly 25% or more, down from "upper 20s to low 30%" on the second-quarter call.
- Uptake in secondary immunodeficiency is slower than hoped.
- Management again described BIVIGAM utilization as stabilizing. Yet revenue fell from $19.4 million, undercutting the same claim made last quarter, and management now points to a BIVIGAM recovery in 2027.
The quality of the beat deserves scrutiny on the balance sheet. Days sales outstanding rose to 110 from 101, above the company's 90-105 day target, and the expected McKesson-driven improvement has slipped beyond 2026. Third-quarter operating cash flow was only about $17 million, against $49.9 million of GAAP net income. Inventory has climbed nearly $60 million this year. Meanwhile, long-term debt rose to $191.6 million from $69.3 million, as $125 million of revolver borrowings helped fund repurchases. These are not crisis signals, but bears have legitimate ammunition on cash conversion. Fourth-quarter R&D is also set to step up to about $10 million for SG-001 conformance lots.
That SG-001 spending comes with the quarter's most important new catalyst. SG-001 is ADMA's investigational pneumococcal hyperimmune globulin. The company received constructive FDA pre-IND feedback on its clinical strategy, and the FDA indicated the proposed assay would be acceptable subject to validation. Management now sees a potentially abbreviated registrational Phase 3 and plans to prepare an IND submission. The company pegs the opportunity at $300-500 million annually if approved, but the program remains preclinical. The long-term targets withdrawn in the first quarter, more than $775 million in 2027 and more than $1.1 billion in 2029, have not been reinstated.
Investors did not enter the report optimistic. Earnings Whispers sentiment slipped from -0.42 to -0.50, a modest move further into negative territory. Price action was more constructive. Shares rose 14.5% from the open after the August report to $11.11, just 1.7% above the 200-day moving average. The stock rallied about 30% off its September 16 low of $8.54 before pulling back 6.6% from its October 30 high of $11.90. With sequential growth and AVWAP readings positive, the market had already begun pricing some recovery while sentiment stayed skeptical.
The bottom line is that ADMA's third quarter appears to confirm the first quarter as the trough. ASCENIV demand and margin expansion are driving genuine earnings leverage, and SG-001 gained real regulatory traction. The unresolved questions are the revenue ceiling, BIVIGAM's persistent erosion, rising receivables, and debt-funded buybacks. Those issues explain why a clear earnings beat-and-raise still left investors cautious.
Read our earnings preview for ADMA Biologics: https://www.earningswhispers.com/article/ADMA/22010
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Oct-28 | |
| Oct-28 | |
| Oct-15 | |
| Aug-21 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Aug-04 | |
| Jul-29 | |
| Jul-20 | |
| Jul-06 | |
| Jun-22 |
