Hamilton Beach Brands Doubles Q3 EPS On Tariff-Margin Recovery, But Retailer Caution Forces A Guidance Cut
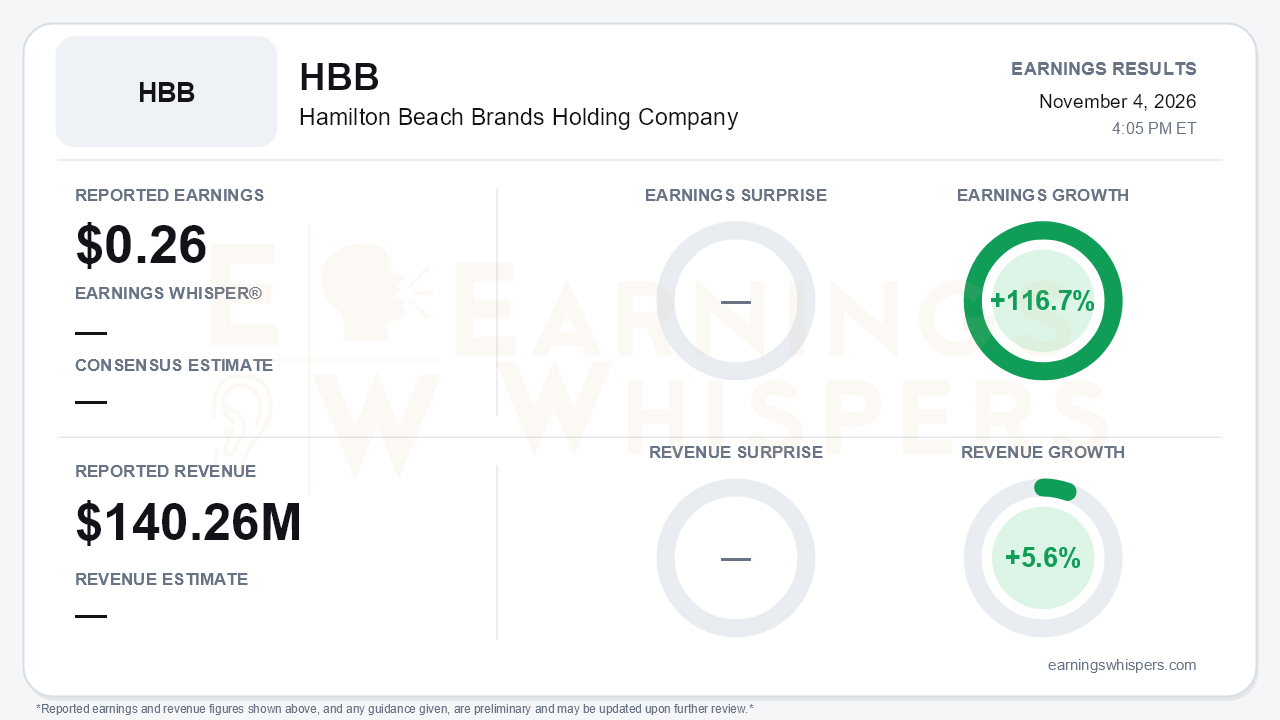
Hamilton Beach Brands delivered a third quarter that looks strong on paper and weaker in substance. Earnings of $0.26 per share grew 116.7% from $0.12 a year ago, and revenue rose 5.6% to $140.26 million. Management called the results "in line with our expectations." The more consequential news was the outlook. The company cut full-year revenue and operating profit guidance because retail partners have grown cautious about holiday inventory as consumer sentiment softens. That is the central tension: the quarter reflects a recovery from last year's tariff disruption, while the forward picture shows that recovery running into a weaker consumer.
The earnings growth was driven almost entirely by gross margin. Gross margin expanded 640 basis points to 27.5% from 21.1%. The main reason was continued sell-through of inventory no longer subject to IEEPA tariffs, compared with a year-ago period burdened by the temporary 125% tariff spike on Chinese imports. Most of that margin gain did not reach operating profit. SG&A jumped $9 million to $34.2 million. The increase included $4.0 million in higher incentive compensation tied to share-price appreciation, $1.6 million in added advertising, and $1.3 million in accelerated depreciation on the legacy ERP system. Operating profit still rose 52.6%, but only to $4.4 million. The bottom line also benefited from net interest income replacing interest expense, partly offset by a higher tax bill. The quality of the beat over last year deserves scrutiny. Much of it reflects a depressed comparison, and the year-ago revenue base was itself hurt by a large retailer delaying orders.
The top-line trajectory is decelerating. Revenue growth slowed to 5.6% from 11.6% in the second quarter as easy tariff-era comparisons fade. Full-year revenue is now guided flat, versus prior guidance of growth approaching mid-single digits. That earlier target had been reaffirmed on three consecutive calls, so this is a genuine break in the narrative. Excluding the expired Bartesian license, implied growth is now 3.4% for the year and just 1.3% for the fourth quarter. Operating profit is now expected to fall by a high-teens percentage. That compares with a high-single-digit decline guided in Q2 and a low-teens decline originally, the result of lower sales and heavier stock-driven compensation. Management's tone shifted noticeably. In Q2 it described the company as well positioned for back-half top-line growth; this quarter it cited a "softer consumer outlook." Management still maintains that sell-through remains solid, which places the problem in retailer ordering rather than end demand. Investors will need to judge whether that distinction holds through the holidays.
The cash and balance-sheet story is the clear bright spot. Nine-month operating cash flow reached $80.5 million, compared with a $14.6 million outflow a year earlier, helped by Q2 IEEPA refunds and lower inventory. Inventory fell to $138.7 million from $174.8 million. The company paid down $25 million of debt and ended the quarter with $67.5 million in net cash, versus $32.8 million of net debt a year ago. Free cash flow guidance was raised to $40 to $50 million from $35 to $45 million, and another roughly $4 million tariff refund is expected in Q4. Gross margin excluding refunds is still expected to finish modestly ahead of 2025's 25.7%. Management did flag that higher commodity and freight costs are offsetting the tariff-free inventory benefit in the second half.
Strategic catalysts also advanced:
- Two single-serve coffee platforms launched.
- Lotus Signature had a soft launch ahead of a broader rollout early next year.
- The Eclipse blender debuted at a national coffee chain.
- CHI expanded across a department-store chain.
- Hamilton Beach Health posted its fifth straight profitable quarter, passed 1.25 million tracked injections, and remains on track for roughly 50% sales growth.
These initiatives support the push toward higher-margin lines, but they are not yet large enough to offset softer core retail orders. Notably, the call drew no analyst questions, which leaves the fourth-quarter guidance cut largely unexamined.
Market context is limited. Shares opened at $24.83 after the August report, close to the current 200-day moving average of $24.03. Management's own attribution of higher incentive costs to share-price appreciation suggests the stock has been rewarded during the tariff recovery. That sets a higher bar now that the operating outlook has deteriorated.
The bottom line is that Hamilton Beach Brands showed it can rebuild margins and generate substantial cash once tariff distortions clear, and its net-cash balance sheet gives it real flexibility. The investment setup has still shifted. Growth is decelerating, operating profit guidance has now been cut repeatedly, and holiday orders depend on cautious retailers. Bears have legitimate ammunition until sell-through translates back into order commitments.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 4 hours | |
| 4 hours | |
| Oct-28 | |
| Aug-27 | |
| Aug-27 | |
| Aug-19 | |
| Aug-05 | |
| Aug-05 | |
| Jul-29 | |
| May-08 | |
| May-06 | |
| May-06 | |
| Apr-29 | |
| Mar-04 |
