Fastly Beats And Raises For A Third Straight Time, But Growth Is Narrowing Toward Its Largest Customers
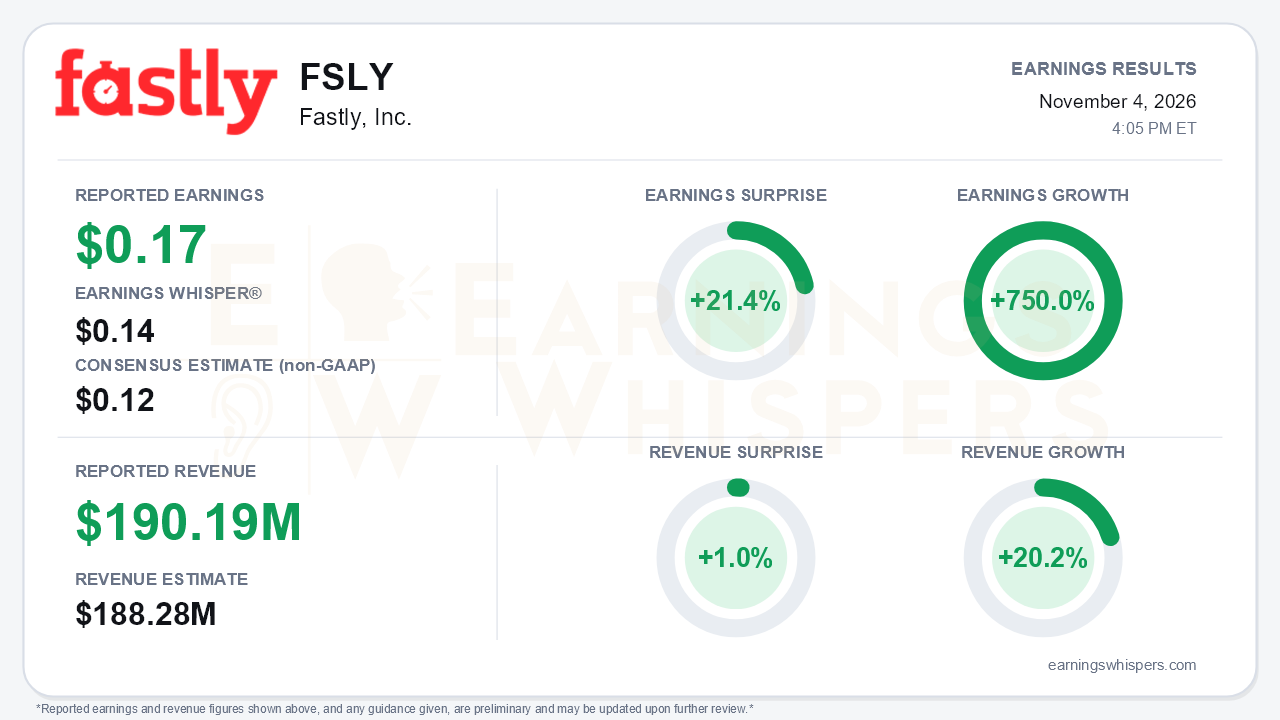
Fastly delivered another clean beat-and-raise in the third quarter. Non-GAAP earnings of $0.17 per share topped the $0.12 consensus by 21.4% and cleared the $0.14 Earnings Whisper number. Revenue of $190.19 million edged past the $188.28 million consensus by 1.0% and grew 20.2% year over year. Earnings grew 750.0% from $0.07 a year earlier, and management raised full-year revenue, profit and free-cash-flow guidance for the third consecutive quarter. The central tension is that the growth engine is becoming narrower. Revenue from customers outside the top ten grew just 8%, down from 12% in Q2, 17% in Q1 and 20% in Q4 2025. Meanwhile, the top ten grew 46% and rose to 39% of revenue.
The profitability story is real, though worth scrutinizing at the edges. Non-GAAP gross margin reached 65.8%, matching the prior record and up from 62.8% a year ago. Non-GAAP operating income nearly tripled to $31.2 million, a 16.4% margin, beating the company's own $20 million to $24 million guide. On a GAAP basis, Fastly is still losing money. The net loss narrowed to $0.07 per share from $0.20, but stock-based compensation of $34.9 million, roughly 18% of revenue, remains the main bridge between the two pictures. Three other details temper the earnings quality:
- Non-GAAP diluted shares rose to 181.9 million from 161.2 million.
- Q3 operating expenses benefited from a $1.5 million non-recurring tax item.
- Fastly began excluding stock-related payroll taxes from non-GAAP results this year.
Cash generation was stronger. Q3 free cash flow hit a record $25.2 million. However, nine-month free cash flow of $32.9 million still trails last year's $37.2 million because capital expenditures more than doubled.
The call preserved a credible growth story while exposing its dependence on a handful of accounts. Last-twelve-month net retention climbed to 119%, extending a steady rise from 110% in Q4 2025. Multiproduct adoption also improved: 34% of large customers now use four or more product suites, up from 30% in Q2. Below the headline, momentum cooled:
- Security growth slowed to 32% from 43% and 47% in the prior two quarters, against a tough comparison.
- Compute and other revenue growth slowed to 37% from 69%.
- Total remaining performance obligations fell sequentially for a second straight quarter, to $334 million from $341 million and $369 million. Year-over-year RPO growth slowed to 24% from 38%.
Current RPO grew 31% and represents 81% of the total, which suggests near-term visibility is healthier than the headline backlog implies. Management acknowledged it had over-focused on top accounts, a candid admission that the broader customer base has been under-served.
The forward setup carries both new catalysts and identifiable risks. On the positive side, Fastly announced:
- a seven-figure commitment from a leading AI company to secure agentic traffic, requiring no incremental capex;
- an industry-first deployment of the full Fastly platform inside Comcast's network;
- new AI Firewall and AI Runtime Control products.
Full-year guidance now calls for revenue of $744 million to $748 million, non-GAAP operating income of $107 million to $111 million (about a 15% margin, up from an initial 8%), and EPS of $0.61 to $0.63. The Q4 revenue guide of $198 million to $202 million, however, implies growth slows to roughly 16%. That guide also leans partly on episodic traffic from the GTA 6 launch. Bears have additional ammunition in the retirement of Scott Lovett, President of Go-to-Market. The resulting CRO search arrives just as management says it must broaden its sales motion beyond the largest customers.
The market had not been rewarding the improving fundamentals before the report. Shares closed at $21.07 on the day before results, down 7.3% from the $22.73 opening after the August report and about 2.1% below the $21.52 200-day moving average. The inter-earnings path was volatile. The stock ran from a $19.76 low on September 3 to $31.33 on September 23, then surrendered nearly all of that move and entered the print 32.7% below the high and only 6.6% above the low. Investor sentiment became modestly more positive, rising to 0.337 from 0.254. Momentum and sequential-growth trend readings are positive, while AVWAP remains negative, reflecting how much of the September spike holders have given back.
The bottom line is that Fastly's quarter strengthened the profitability and cash-flow case. The company produced record margins, a record quarterly free-cash-flow figure, and a third straight raise to full-year targets. The quality of the growth deserves closer scrutiny, though. The rest of the customer base has slowed to single-digit growth, backlog is contracting sequentially, and Q4 depends partly on a single blockbuster game launch. Meanwhile, the sales organization is changing leadership. Investors will likely judge the next few quarters on whether Fastly can re-broaden growth beyond its top ten customers, not on whether it can beat estimates.
Read our earnings preview for Fastly, Inc.: https://www.earningswhispers.com/article/FSLY/21840
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Nov-03 | |
| Oct-28 | |
| Oct-27 | |
| Oct-22 | |
| Oct-14 | |
| Oct-13 | |
| Oct-13 | |
| Oct-12 | |
| Oct-09 | |
| Oct-09 | |
| Oct-09 | |
| Oct-09 |
