Evolus Misses On EPS As Growth Cools From Q2, Leaving The Reaffirmed Outlook Dependent On A Steep Fourth-Quarter Ramp
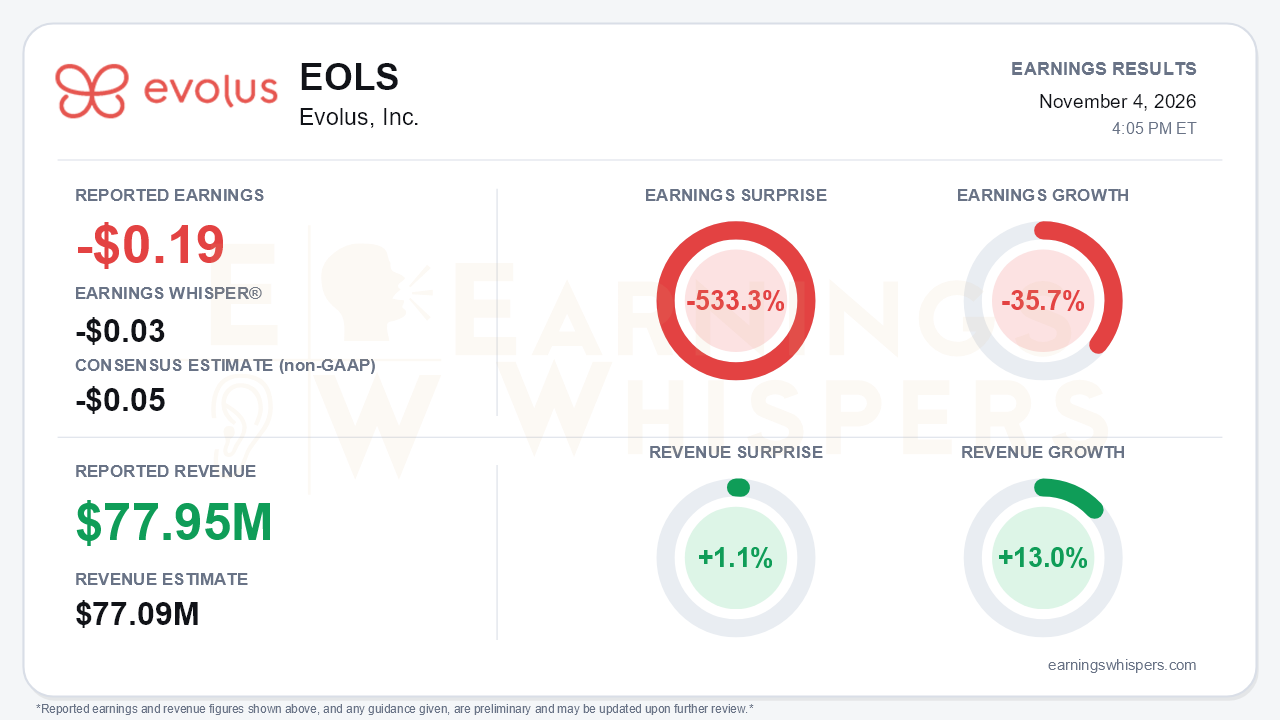
Evolus (NASDAQ: EOLS) delivered a quarter where the revenue line held up and the earnings line did not. The company reported a loss of $0.19 per share, well short of the -$0.05 consensus and the -$0.03 Earnings Whisper number, a 533.3% miss. Revenue of $77.95 million edged past the $77.09 million consensus by 1.1% and grew 13.0% year over year. The central tension is not the size of the EPS miss. It is that growth decelerated sharply from the second quarter while management reaffirmed a full-year revenue range that now requires a meaningful fourth-quarter acceleration to reach.
The quality of the miss deserves some context. The reported -$0.19 matches GAAP net loss per share, while the consensus was framed on a non-GAAP basis, so the comparison is not perfectly like-for-like. On Earnings Whispers' normalized basis, earnings fell 35.7% year over year. The GAAP income statement tells a different story: net loss narrowed to $12.5 million, or $0.19 per share, from $15.7 million, or $0.24, a year ago. GAAP operating loss improved to $8.4 million from $11.5 million. Adjusted EBITDA swung to a $1.2 million profit from a $3.1 million loss, the fourth straight positive quarter. Several items sit below that operating line and weigh on GAAP results: roughly $4.2 million of quarterly interest expense, a $1.6 million contingent royalty revaluation, and a $1.1 million IPR&D charge. The operating improvement is real. It is also thin: adjusted EBITDA margin was just 1.5%, and adjusted gross margin slipped to 66.1% from 67.6% a year earlier.
The sequential comparison is less flattering. Revenue growth slowed to 13% from 21% in Q2, as Evolus began lapping mid-teens comparisons from the second half of 2025. HA gel revenue fell sequentially to $7.9 million from $8.9 million. HA growth eased to roughly 40% from more than 50% year to date, and global toxin revenue grew about 11%. Adjusted gross margin dropped from about 69% in Q2, although that quarter included a roughly 120-basis-point tariff refund. Adjusted EBITDA fell to $1.2 million from $4.7 million. Management's tone also shifted. It cited softer consumer confidence and described the filler market as flat to single-digit growth, a notable retreat from Q2's framing that consumer demand continued to strengthen.
The customer funnel kept building even as dollars softened:
- Evolysse purchasing customers topped 4,500, versus about 3,500 at Q1.
- Cumulative accounts passed 19,400.
- Evolus Rewards membership exceeded 1.6 million.
- Reorder rates remain above 70%.
Management also trimmed full-year non-GAAP opex guidance to $210 million to $213 million, implying flat to 2% expense growth against 11% to 13% revenue growth. That cost discipline is the clearest support for the reaffirmed low- to mid-single-digit adjusted EBITDA margin. The problem is the top line. With $235.2 million booked through nine months, the $330 million to $337 million range implies a 25% to 30% sequential step-up in Q4, alongside higher fourth-quarter spending.
The catalyst calendar is fuller than the quarter itself:
- **Evolysse Sculpt:** FDA approval is still expected in Q4, with launch activity in Q1 2027.
- **Evolysse Lips:** a PMA filing is due by year-end.
- **Pipeline:** the Profhilo partnership and a new option on an injectable hair-growth asset broaden the portfolio. The option payment is expected to be expensed as IPR&D in Q4.
- **Tariffs:** risk eased, since Commerce Department guidance indicates Jeuveau should not face tariffs.
The balance sheet has a few features worth tracking:
- Inventory jumped to $82.8 million from $27.0 million at year-end after Evolus pulled forward about 12 months of Jeuveau stock.
- Payables and accruals roughly doubled to $122.8 million. Deferred payment terms with Daewoong mean the inventory build does not hit cash yet, but it will eventually unwind.
- Cash fell to $41.7 million, with about $120 million of non-dilutive capacity behind it.
- Stockholders' deficit widened to $37.8 million.
- An FDA untitled letter over a Jeuveau Instagram post is minor by management's account but adds regulatory noise.
Investors were not leaning bullish going in. Earnings Whispers sentiment stayed negative and weakened modestly, from -0.18 to -0.28. Shares were $7.37 heading into the report, up 5.4% since the open after the August release and about 17% above the 200-day moving average. They were also nearly 21% below the September 52-week high of $9.31, meaning a good portion of the post-Q2 enthusiasm had already been surrendered before this print.
The bottom line is that Evolus produced a steady but decelerating quarter. The modest revenue beat and positive adjusted EBITDA are overshadowed by an EPS miss, slowing HA momentum, softer consumer commentary, and a reaffirmed guide that leans heavily on Q4. Cost control and the Sculpt approval give bulls something tangible. Still, bears have legitimate ammunition until the fourth quarter shows the reacceleration that the outlook assumes.
Read our earnings preview for Evolus, Inc.: https://www.earningswhispers.com/article/EOLS/21832
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| Oct-28 | |
| Oct-27 | |
| Oct-21 | |
| Oct-14 | |
| Oct-02 | |
| Oct-01 | |
| Sep-01 | |
| Aug-06 | |
| Aug-05 | |
| Aug-04 | |
| Jul-22 | |
| Jul-10 | |
| Jul-09 | |
| Jul-08 |
