Cytokinetics Beats As MYQORZO Sales Jump 76%, But A Flat Operating Loss And Slumping Shares Keep The Bar High
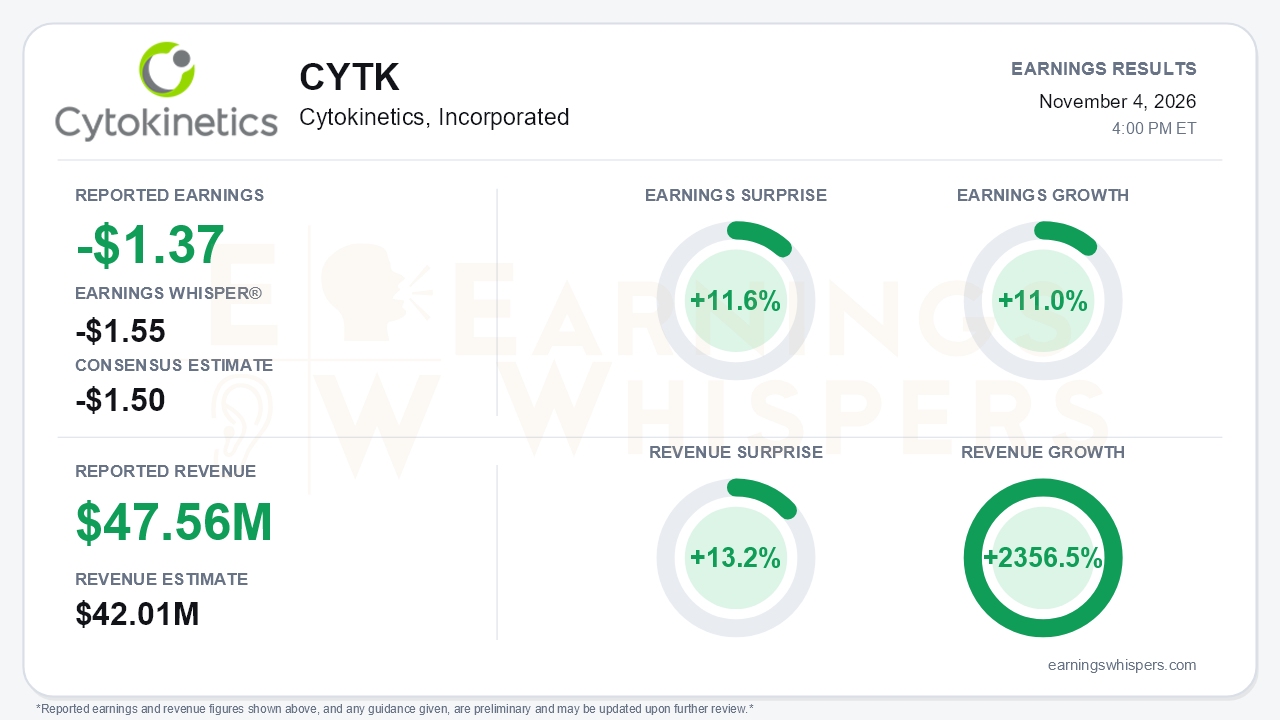
Cytokinetics delivered a clean beat on the metrics that matter most for a launch-stage company. The third-quarter loss of $1.37 per share topped the -$1.50 consensus and the more cautious -$1.55 Earnings Whisper number, an 11.6% surprise. Revenue of $47.56 million beat the $42.01 million consensus by 13.2%. The real story is MYQORZO. Net product revenue reached $44.5 million, up 76% from $25.3 million in the second quarter and from just $4.8 million in the first, so the launch is still accelerating in dollar terms. The central tension is that the stock has moved the other way. Shares fell 23.3% between the opening after the August report and the eve of this one.
The quality of the earnings beat deserves scrutiny. Earnings grew 11.0% year over year as the loss narrowed from $2.55 per share. That comparison is flattered, however, by two factors. The year-ago quarter carried a $121.2 million debt conversion charge, and the weighted share count has risen to roughly 139 million from 120 million. Strip those away and the operating loss was essentially unchanged at $167.1 million versus $166.8 million. Revenue growth was absorbed almost entirely by spending. SG&A jumped to $113.1 million from $69.5 million a year ago and $104.4 million in the second quarter as commercial build-out continued. Cost of goods sold was a $0.5 million credit tied to supply optimization, a one-time benefit rather than a durable margin signal. Non-cash interest on the revenue participation agreements also climbed to $23.6 million from $15.0 million. Those royalty-style obligations scale with product sales.
Beneath the revenue line, the launch metrics improved on nearly every front:
- U.S. revenue rose to $43.1 million from about $23 million in the second quarter.
- Prescribers expanded from roughly 275 in the first quarter to more than 700 in the second and about 1,100 in the third.
- Patients dispensed climbed past 2,800 from 1,500.
- Patients per prescriber deepened to about four, with high-volume writers at seven.
- New-to-brand share exited near 45%, around 50% among high-volume writers, and management reiterated its year-end goal above 50%.
- Commercial coverage widened to more than 60% of lives.
The cardiac myosin inhibitor category itself grew 56% year over year. About 70% of category growth since the second quarter came from prescribers new to the class. That suggests MYQORZO is expanding the market, not merely taking share. Europe was softer: revenue slipped to $1.4 million from $2.3 million of second-quarter stocking, and management does not expect meaningful EU revenue until 2028-2029.
The catalyst calendar is dense. The MAPLE-HCM PDUFA date is November 14. The ACACIA-HCM non-obstructive HCM data, presented at ESC and published in NEJM, support an sNDA filing this quarter and an EU submission in early 2027. A HFSA responder analysis showed 53% of patients responding versus 13% on the comparator. If the nHCM label comes through, aficamten could become the only cardiac myosin inhibitor approved across the full HCM spectrum. Other near-term events include:
- a UK launch this quarter, following Health Canada approval;
- CEDAR-HCM adolescent topline data in early 2027;
- the new ASPEN-HCM real-world study, intended in part to support potential REMS relaxation.
Bears still have legitimate ammunition. A competitor is pursuing an echo-free titration approach that could erode MYQORZO's REMS positioning. Heart failure events during titration in ACACIA-HCM will need to be managed in labeling. COMET-HF enrollment now runs into 2027. Management offered no revenue guidance and deferred 2027 targets, only reaffirming the $860-890 million operating expense range it raised last quarter. Cash slipped to about $1.6 billion from $1.7 billion. That is ample runway, but the balance sheet also carries heavy convertible, term-loan and royalty-linked liabilities.
The market setup is more complicated than the surprise implies. Shares entered the report at $62.31, 11% below the 200-day moving average of $70.03. They sat just 4.2% above the October 8 inter-earnings low of $59.79, having peaked at $81.50 the day after the prior report. Investor sentiment improved modestly, moving from slightly negative (-0.056) to slightly positive (0.031). That is a shift in tone, not a wave of enthusiasm. Earnings Whispers trend readings are split: sequential growth and momentum are positive, while price and AVWAP trends remain negative. That pattern mirrors the gap between improving fundamentals and a stock that has been sold.
The bottom line is that Cytokinetics produced an unambiguously strong launch quarter, with accelerating revenue, deeper prescriber adoption and a credible path to a much larger nHCM label. The per-share beat, though, owes more to dilution and an easy year-ago comparison than to operating leverage. With the operating loss flat, spending rising and no forward revenue framework, the shares remain hostage to the November 14 PDUFA, the nHCM filing and evidence that sales growth can eventually outrun costs.
Read our earnings preview for Cytokinetics, Incorporated: https://www.earningswhispers.com/article/CYTK/21819
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Nov-03 | |
| Nov-02 | |
| Oct-27 | |
| Oct-21 | |
| Oct-19 | |
| Oct-19 | |
| Oct-12 | |
| Oct-11 | |
| Oct-02 | |
| Sep-30 | |
| Sep-17 | |
| Sep-14 |
