Cytek Beats On A Gross Margin Surge, But Slowing Growth And A Fading EBITDA Outlook Leave A Rallied Stock Little Room For Error
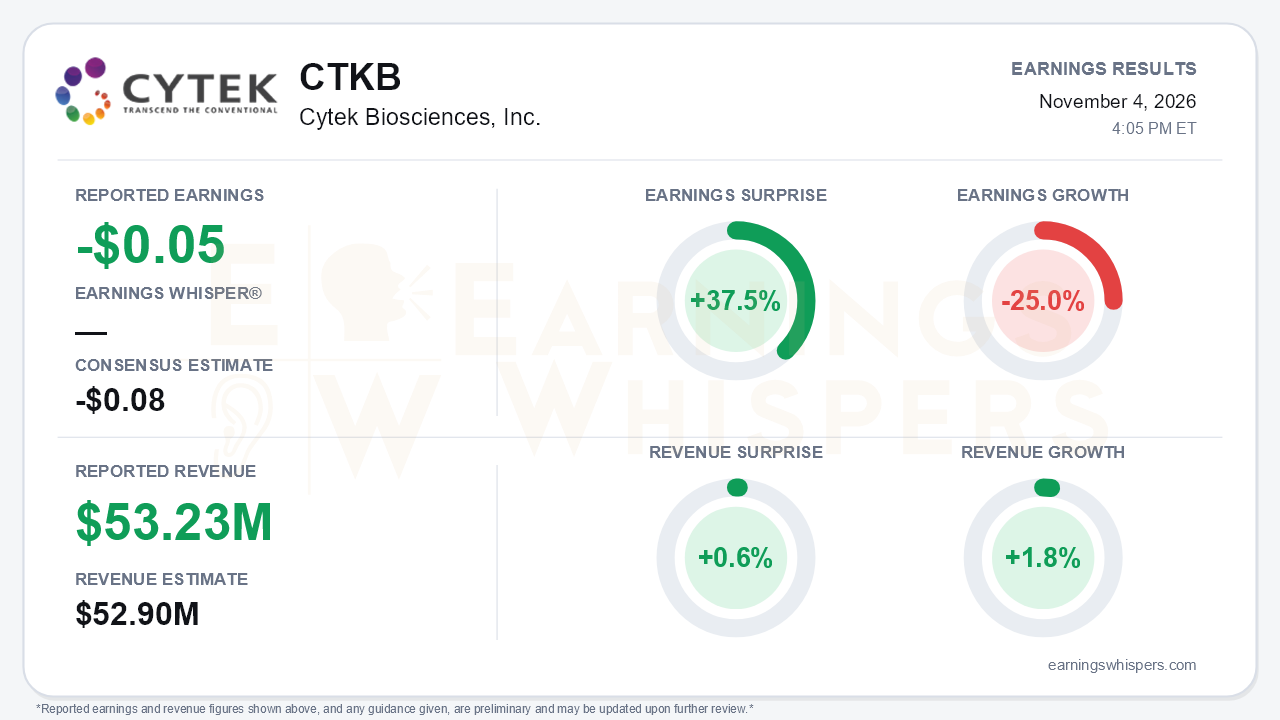
Cytek Biosciences delivered a third-quarter beat that was built almost entirely on the cost line. The company lost $0.05 per share against a consensus estimate of -$0.08, a 37.5% earnings surprise. Revenue of $53.23 million edged past the $52.9 million consensus by 0.6%. The year-over-year comparison is less flattering. The loss widened from $0.04 a year ago, so earnings fell 25.0%. Revenue grew just 1.8%, a clear deceleration from 6% growth in both the first and second quarters. That is the central tension: manufacturing execution is visibly improving, while top-line momentum has stalled.
The margin story is real. GAAP gross margin reached 59%, up 590 basis points from 53% a year earlier and well above the 48% posted in Q1. Gross profit rose 13% on essentially flat sales. The completed transfer of manufacturing from Seattle to Singapore drove much of the gain, along with lower material costs and lower tariffs. Product cost of sales fell to $14.4 million from $17.7 million despite only a modest revenue dip.
The quality of the beat still deserves scrutiny. Operating expenses rose 8%, led by a 14% jump in G&A tied to the patent litigation. As a result, the operating loss narrowed only modestly, to $8.4 million from $9.2 million. Net loss widened to $6.1 million largely because the tax benefit shrank to $0.8 million from $2.3 million. Adjusted EBITDA fell to $0.7 million from $2.5 million.
Beneath the headline, the revenue mix shifted sharply. U.S. revenue grew 12% to $30.4 million. Academic and government revenue swung to 38% growth, reaching $24.5 million after a 12% decline in Q2, and U.S. academic instrument revenue rose more than 60%. High-end analyzer revenue grew more than 30%, Aurora/Evo placements rose 23%, and Evo placements nearly doubled. Service revenue grew 13% with service gross margin improving to 53%. Recurring revenue rose to 36% of trailing-twelve-month sales.
Those gains were offset almost entirely by weakness elsewhere:
- APAC fell 25% on macro weakness in China and the broader region.
- Biopharma, distributor and CRO revenue dropped about 17%, a reversal from 22% growth in Q2.
- Total product revenue declined 3% as imaging and mid/low-end instruments weakened.
EMEA returning to 1% growth after two quarters of declines was a modest positive. The customer base driving growth flipped in a single quarter, which argues against extrapolating either segment's swing.
Guidance trimmed rather than raised conviction. Management narrowed full-year revenue guidance to $208–$211 million, holding the $209.5 million midpoint. The high end has now been cut from $212 million, while the low end has crept up from $205 million earlier in the year. With $145.5 million booked through nine months, the range implies a Q4 of roughly $62.5–$65.5 million. That backs the CEO's call for a "strong finish," but it also concentrates execution risk in one quarter. The adjusted EBITDA outlook has drifted from "positive" earlier in the year to "around break-even," against a nine-month adjusted EBITDA loss of $9.9 million. Management also pushed its business-unit reorganization into 2027 and declined to endorse a second-half-based growth framework for next year. Bears have legitimate ammunition here.
The catalysts are tangible:
- **Patent case:** the August jury verdict went Cytek's way on three of four claims, and legal spending is expected to fall by $3–4 million after the trial. The fourth claim, infringement under the doctrine of equivalents affecting U.S. instruments, leaves damages and remedies unresolved, and Cytek has filed post-verdict motions.
- **New products:** the Borealis early-access program doubled ahead of a broader 2027 launch, and SciTech Cloud users are approaching 30,000.
- **2027 outlook:** management expects to outgrow the market and peers with improving profitability.
One inconsistency is worth noting. The release calls 59% the best third-quarter gross margin since 2023, while call commentary framed it as the best since 2020.
The market had already moved ahead of the report. Shares closed at $5.96 before the release, up 36.4% from the $4.37 open after the August report. That leaves the stock about 28% above its 200-day moving average and within 6% of the $6.34 52-week high set October 29. Investor sentiment shifted from mildly negative (-0.11) to mildly positive (+0.18), a meaningful but not euphoric change. Most Earnings Whispers trend signals, including price, sequential growth and AVWAP, are positive, with momentum neutral. The stock entered earnings near the top of its inter-earnings range. A margin-driven beat paired with decelerating sales and a flat outlook is not obviously the catalyst for a further leg higher.
The bottom line is that Cytek proved it can structurally lift gross margin, and its U.S. academic franchise and high-end instruments are gaining share. Revenue growth, however, slowed to roughly 2%, the EBITDA outlook continues to erode, and full-year guidance now hinges on a large fourth quarter. Investors who bid the stock up 36% are betting on a 2027 reacceleration that management has only partly underwritten.
Read our earnings preview for Cytek Biosciences, Inc.: https://www.earningswhispers.com/article/CTKB/21815
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-04 | |
| Nov-04 | |
| Oct-29 | |
| Oct-27 | |
| Oct-21 | |
| Sep-23 | |
| Sep-09 | |
| Sep-03 | |
| Sep-01 | |
| Aug-21 | |
| Aug-06 | |
| Aug-05 | |
| Jul-22 | |
| Jul-15 |
