Klaviyo Beats And Raises Again, But A 21% Q4 Guide, Slipping NRR And A Missing 2027 Outlook Keep The Deceleration Story Front And Center
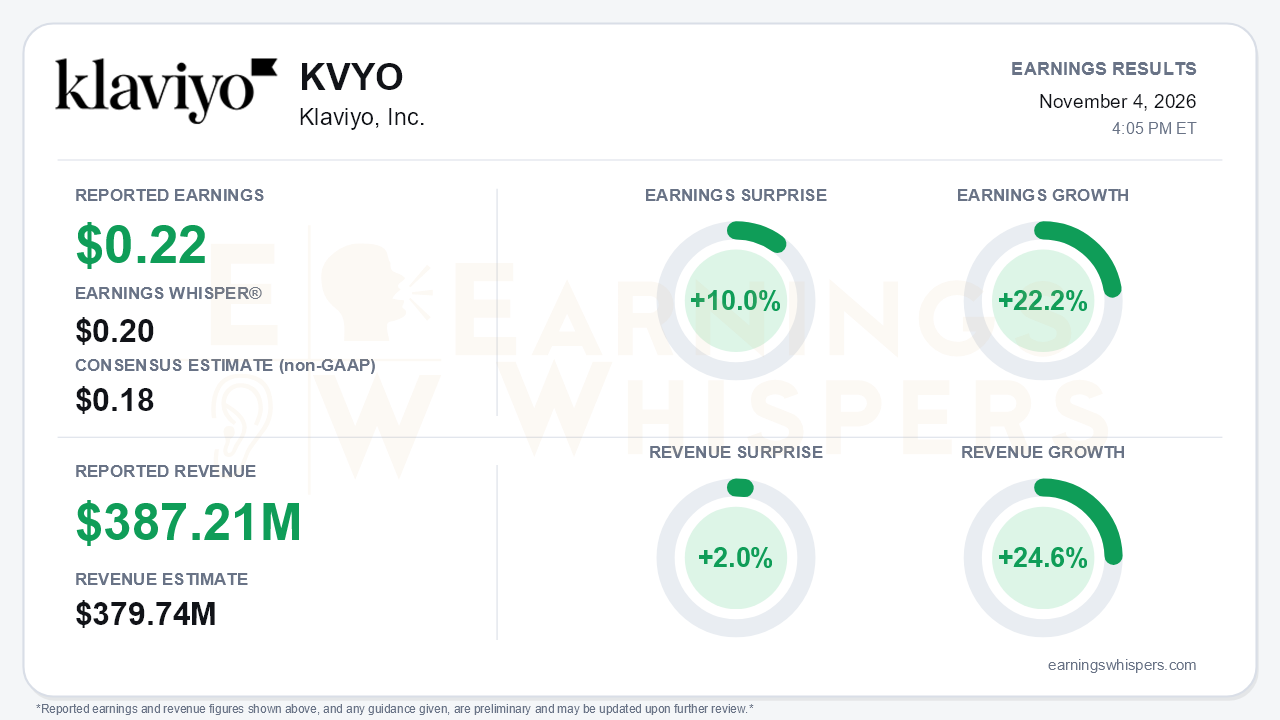
Klaviyo delivered another clean beat-and-raise in the third quarter. Non-GAAP earnings of $0.22 per share topped the $0.18 consensus and the $0.20 Earnings Whisper number, a 10.0% surprise. Revenue of $387.21 million beat the $379.74 million consensus by 2.0%. Earnings grew 22.2% year over year and revenue rose 24.6%. Profitability was the standout: non-GAAP operating income of $56.9 million crushed management's own $40-43 million guide. The central tension is that the profit upside is arriving just as top-line growth keeps grinding lower. Revenue growth has slid from 30% in Q4 FY25 to 28%, 26% and now 25%. The fourth-quarter guide of $421-425 million implies roughly 21%.
The quality of the beat deserves some scrutiny. On a GAAP basis, Klaviyo swung to a $704,000 net profit from a $426,000 loss, and the operating loss narrowed to $4.5 million from $10.8 million. That is real progress. Per-share growth, however, got meaningful help from capital return. Non-GAAP net income rose to $62.1 million from $55.4 million, while diluted share count fell to roughly 286.5 million from 306.8 million. That shrinkage followed $150.9 million of repurchases in the quarter and $484 million year to date. The buybacks also drained cash to $705 million from $1.06 billion at year-end, and interest income fell accordingly. Free cash flow was $24.8 million versus $47.1 million a year ago. A $15.3 million intangible asset purchase weighed on that figure, and adjusted free cash flow was a still-softer $40.1 million. Non-GAAP gross margin of 74.9% was down from 76.3% a year ago. It did recover from 73.4% in Q2 on cloud cost optimization, though management flagged that a heavier text-messaging mix will pressure gross margin in Q4.
Beneath the headline, the call preserved a credible upmarket and platform story. Customers above $500,000 in ARR rose 57% to 105, and those above $250,000 grew 49% to 390. Customers using three or more products now account for 22% of ARR, up from about 20% in Q2 and 15%-plus at the end of FY25. Multi-product deals made up 43% of new ARR. Frasers Group became Klaviyo's largest-ever EMEA new logo, consolidating 13 brands, and a Fortune 500 company replaced a legacy marketing tool. The weaker side of the ledger is just as clear:
- Net revenue retention slipped to 108% from 109% in Q2 and 110% in Q1. Management is now reframing NRR as understating the business's health and steering investors toward cohort growth instead.
- Growth outside the Americas decelerated to 32% from 35%, 39% and 41% in the prior three quarters.
- The $50,000-plus customer count was disclosed in the release (4,725, up 33%), but the call analysis notes it was not updated from Q2's 4,477 on the call.
The AI roadmap supplies the most important new catalysts. Within three weeks of its relaunch, Composer more than doubled daily active accounts to over 10,000 and tripled weekly credits to 18 million. The MCP server is used by more than 70,000 accounts, and new embedded apps inside Shopify and Wix put Composer directly in the merchant workflow. Still, Composer sits at only about 5% of daily active accounts, and free credits are delaying monetization. The more telling risk is what management did not say. Under new CFO Erica Smith, the company broke with prior practice and withheld an early 2027 outlook, deferring it to the year-end call. Combined with full-year raises that have shrunk from $13 million to $12 million to $9 million, that leaves bears with legitimate ammunition. The full-year non-GAAP operating income guide, by contrast, rose to $233-236 million, above the original range.
The market setup is more complicated than the surprise implies. Shares have climbed 31.7% since the open after the August report and now trade 18.3% above the 200-day moving average. The stock entered the print just 3.7% below its inter-earnings high of $22.14, set on November 2, after rallying 44.4% off a late-September low of $14.77. Investor sentiment moved in the opposite direction, deteriorating sharply from -0.17 to -0.67. A stock running near its highs into a report while sentiment sours sets a high bar for a quarter that offered decelerating growth and no 2027 visibility. The Earnings Whispers trend signals are mostly positive, with sequential growth, momentum and AVWAP readings constructive, which helps explain the rally but does not resolve the growth question.
The bottom line is that Klaviyo is executing well on profitability, enterprise expansion and multi-product adoption. Even so, the core debate has shifted squarely to how far revenue growth decelerates from here. A roughly 21% Q4 guide, slipping NRR, cooling international growth and a deferred 2027 outlook mean the next call carries outsized weight. Until Composer monetization and enterprise momentum visibly stabilize the top line, margin beats and buybacks are unlikely to settle that debate on their own.
Read our earnings preview for Klaviyo, Inc.: https://www.earningswhispers.com/article/KVYO/21859
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Oct-27 | |
| Oct-21 | |
| Oct-20 | |
| Oct-20 | |
| Oct-20 | |
| Oct-20 | |
| Oct-16 | |
| Oct-14 | |
| Sep-24 | |
| Sep-10 | |
| Sep-09 | |
| Sep-09 | |
| Aug-25 |
