HubSpot's Margin-Driven Beat Masks A Deepening Demand Slowdown As Q4 Guide Implies Growth Sliding To 12%
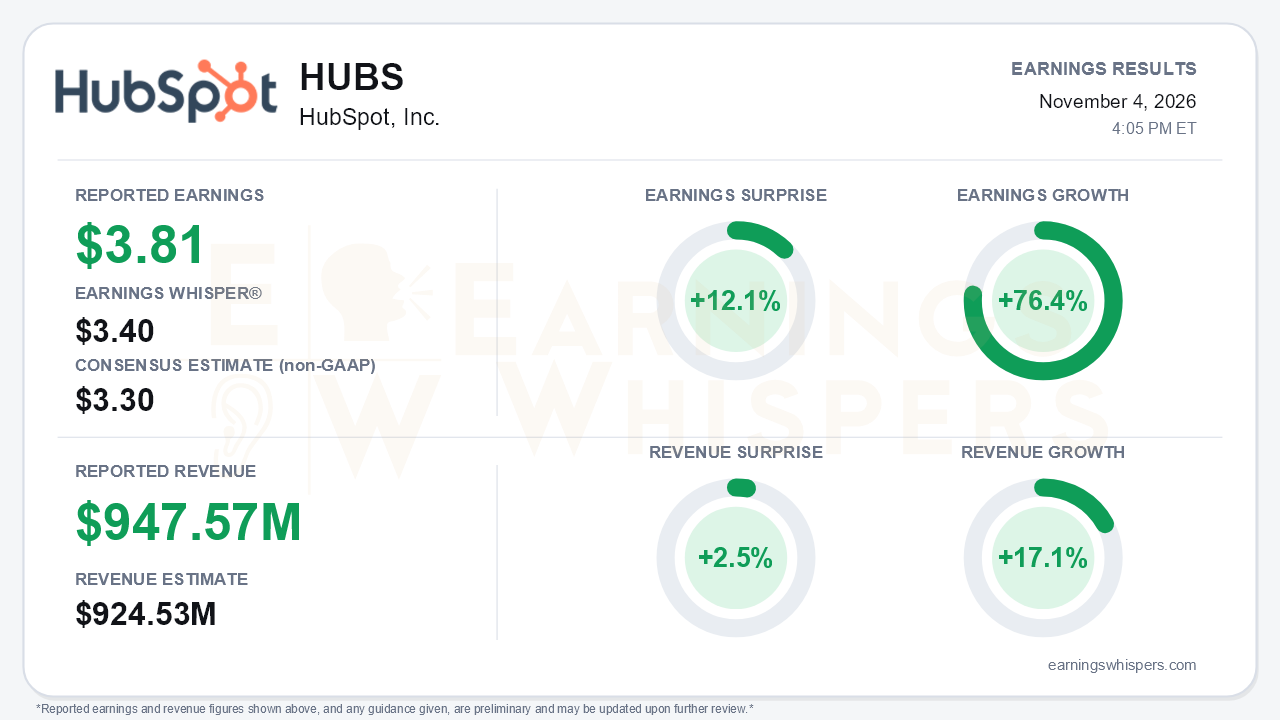
HubSpot delivered a clean third-quarter beat, but the forward picture got worse. Non-GAAP earnings of $3.81 per share topped the $3.30 consensus by 12.1% and cleared the $3.40 Earnings Whisper number. Revenue of $947.57 million beat by 2.5% and grew 17.1% year over year. Yet the company guided fourth-quarter revenue to $945 million to $947 million, roughly flat with Q3 and up only about 12%. Management also cut nearly every forward demand indicator it tracks. That is the central tension: profitability is improving quickly while growth decelerates faster than investors had been told to expect.
The quality of the beat deserves scrutiny. Non-GAAP operating margin reached 22.6%, up from 19.9% a year ago, and non-GAAP operating income rose 33% to $214.2 million. Expense discipline drove most of that, with non-GAAP R&D falling to 16.7% of revenue from 18.7%. Several other factors also lifted per-share results:
- **Buybacks:** $237.2 million in the quarter and roughly $1 billion year to date cut diluted shares to 49.5 million from 52.7 million.
- **Tax rate:** a lower 15% non-GAAP tax rate, down from 20%, flatters comparisons with 2025.
That helps explain why growth figures differ by basis. Earnings Whispers puts EPS growth at 76.4%, while HubSpot's own comparison with its originally reported $2.66 shows 43%. GAAP results improved sharply, to $1.67 per diluted share from $0.31, though a $10.6 million gain on strategic investments helped. Non-GAAP subscription gross margin slipped to 85.4% from 86.7%, a reminder that margin gains are coming from operating expenses rather than unit economics.
Beneath the headline, the operating trends deteriorated on almost every measure:
| Metric | Earlier trend | Latest |
|---|---|---|
| Constant-currency growth | 18.2% (Q1), 17.5% (Q2) | 17% (Q3), ~12% implied for Q4 |
| Net revenue retention | 105% (Q4 2025), 103% (Q1), 102% (Q2) | 101% (Q3) |
| Full-year NRR outlook | up 1-2 points (February), flat (August) | down about 2 points |
| Net new ARR | growing faster than revenue earlier in the year | now expected to decline year over year |
| Net customer additions | 10,800 (Q1), 7,000 (Q2) | 5,300 (Q3) |
| Growth in $120K+ deals | 64% (Q1), 38% (Q2) | 19% (Q3) |
Management withdrew its Q4 net-add guidance and now expects fewer than 5,000. Calculated billings grew 15%, trailing revenue. Management said headwinds worsened during the quarter: longer upmarket sales cycles, price sensitivity down-market and pressure on inbound demand. It expects these to persist into 2027, describing a multi-quarter transition. The tone was markedly more cautious than in August.
The bull case rests on AI adoption, and the usage data is genuinely strong:
- Credit consumption is up about 2.5x year to date, and agent actions are up 5x.
- 20% of ProPlus customers now use agents, and 61% use Breeze Assistant.
- Agent trials rose 64% sequentially.
- CRM objects created through LLM connectors jumped 157% sequentially.
- The seats-and-credits pricing pilot drove 2-3x higher credit usage and is expanding to all new EMEA customers in Q4.
The catch is that the new pricing lowers average selling prices in the near term. AI engagement is therefore not yet translating into revenue acceleration. An October reorganization will bring $60-70 million in Q4 severance, which pushes Q4 GAAP operating income to roughly breakeven. Management reaffirmed a 23-24% non-GAAP operating margin target for 2027, but recast it from the earlier '2-3 points of expansion' framing. Full-year non-GAAP EPS guidance rose to $13.59-$13.61. Free cash flow guidance fell to about $720 million from $750 million.
Investor sentiment remained negative but improved meaningfully into the report, rising from -0.49 to -0.36. The stock reflects that partial repair. Shares rose 17.1% from the open after the August report to $226.17 heading into this release, well off the $185.05 low set on August 6. However, the stock had already given back much of a late-October run, sitting 16.7% below its $271.60 high from October 26. It also entered earnings 2.2% below its 200-day moving average of $231.14. The Earnings Whispers trend readings are mixed, with momentum negative even as AVWAP holds positive. That fits a stock that recovered but lost conviction before the print.
The guidance math matters most. The full-year revenue range is essentially unchanged from August despite a Q3 beat, which means the outperformance was absorbed by a weaker fourth quarter. Bears have legitimate ammunition: retention, net new ARR, customer additions and large-deal growth are all moving the wrong way at the same time. Management, by its own account, does not expect a quick reversal.
The bottom line is that HubSpot is becoming a more profitable, more aggressively shareholder-friendly company while its growth engine stalls during a pricing and product transition. The EPS beat is real but leans on cost cuts, buybacks and a lower tax rate. The revenue outlook, sliding retention and falling net new ARR are the more important signals. Until AI usage shows up in billings and net new ARR, the margin story is likely to be weighed against a growth rate heading toward the low teens.
Read our earnings preview for HubSpot, Inc.: https://www.earningswhispers.com/article/HUBS/21852
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 4 hours | |
| 5 hours | |
| 5 hours | |
| Oct-29 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-21 | |
| Oct-16 | |
| Oct-13 | |
| Oct-12 | |
| Oct-12 | |
| Oct-12 | |
| Oct-12 |
