Western Union Beats On Cost Cuts, But A Shrinking Revenue Outlook And At-Risk Intermex Deal Cloud The Margin Recovery
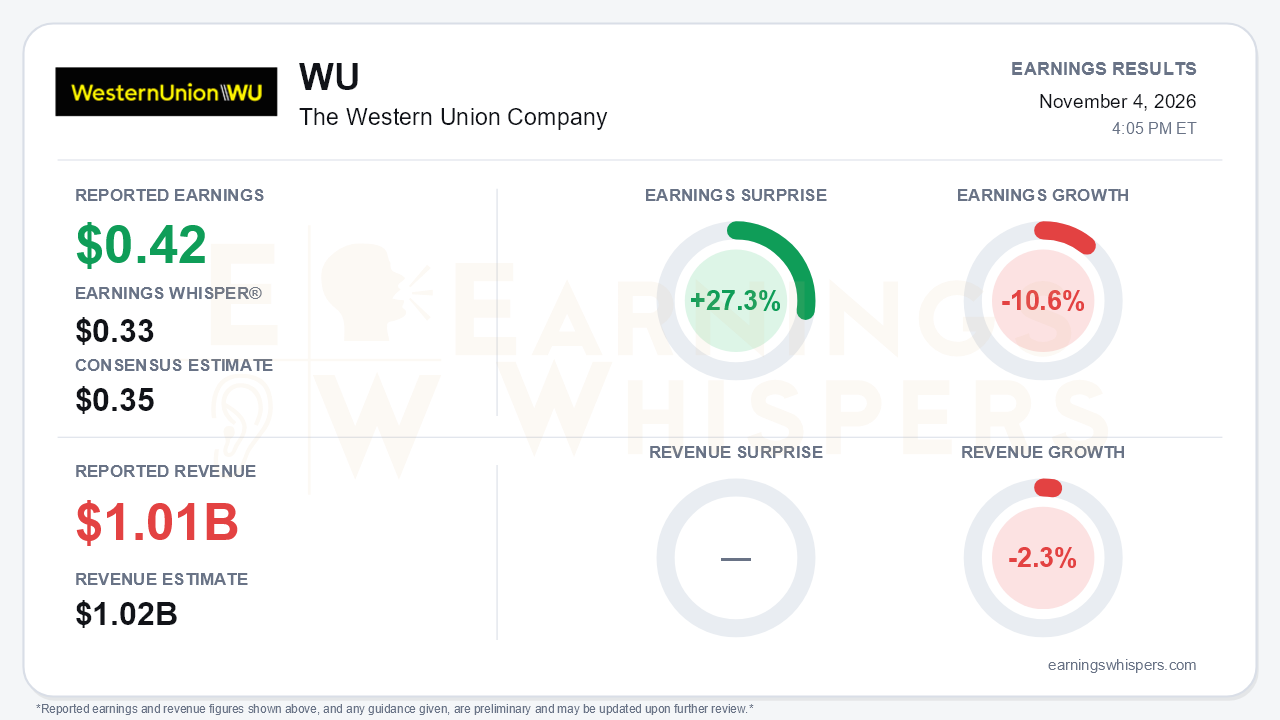
Western Union delivered the kind of earnings beat that cost-cutting is supposed to produce. Adjusted EPS of $0.42 cleared the $0.35 consensus by 27.3% and topped the $0.33 Earnings Whisper number. The top line did not follow. Revenue of $1.009 billion missed consensus by 1.0% and fell 2.3% year over year, while earnings still declined 10.6% from a year ago. That is the central tension of the quarter: profitability is recovering sequentially because expenses are coming out, but the revenue base is still shrinking, and full-year sales guidance was cut again.
The quality of the beat deserves scrutiny. Adjusted EPS improved sharply from $0.31 in Q2 and $0.25 in Q1, and the adjusted operating margin rebuilt to 18% from 15% and 13% in the prior two quarters. Still, the margin remains below the 20% posted a year ago. An adjusted tax rate of 9%, down from 12% a year earlier and 14% in Q2, also flattered the bottom line, along with a lower share count. GAAP EPS was $0.25, down from $0.43, after $37.3 million in Beyond efficiency program charges, worth $0.12 per share, and a higher GAAP tax rate. Segment operating income fell 13% year over year, with Consumer Money Transfer down 15%. That is not the profile of a business growing its way out of trouble.
Beneath the headline, the operating trends are mixed rather than deteriorating. CMT revenue declined 2%, a meaningful improvement from the -6% pace in Q1. Branded Digital grew revenue 8% on 21% transaction growth and now accounts for 32% of CMT revenue. North America revenue declines narrowed to 7% from 11% in Q1, and management cited roughly 500 basis points of improvement in North America outbound, with Mexico easing to low-to-mid single-digit declines. Management's tone shifted noticeably, from calling Q2 performance "not acceptable" to describing a cost structure brought "back into alignment." Beyond savings are running ahead of the $50 million year-end target, with an analyst citing roughly $80 million.
The weaknesses are equally concrete. Roughly half of Q3 Branded Digital revenue growth came from a low-margin Saudi partner that Western Union is exiting, so Q4 digital transactions and revenue will step down. Digital transaction growth already cooled to 21% from 25% in Q2. Consumer Services adjusted growth slowed to 5% from 12% in Q2 and 33% in Q1, as travel money and money orders softened, and management expects a softer Q4. LACA transactions fell 12%. Retail in the Americas remains down mid-teens.
The guidance is where the setup changed most. The full-year adjusted EPS range edged up to $1.28-$1.38 from $1.25-$1.35, but it remains far below the original $1.75-$1.85. Revenue guidance fell to flat to +1%, from +4% to +6% previously. Even that range assumes Intermex closes on November 10, 2026, and the deal still needs reinstated approval from the California DFPI. That outside date is days away and allows either party to walk. Excluding Intermex, revenue is guided down 1% to 2%. Balance-sheet flexibility is also tighter: year-to-date operating cash flow of $321 million is down 21%, buybacks remain paused, and gross leverage stands at 3.3x. On the positive side, there are real catalysts:
- the USDPT stablecoin has reached about $20 million in circulation and $150-$200 million in monthly volume;
- Canada Post went live and Publix renewed;
- the Beyond Digital platform is rolling out to Mexico, Australia and the U.S. in the first half of 2027.
Investors came into the print deeply skeptical. Earnings Whispers sentiment remained negative but improved modestly, moving from -0.57 to -0.51. Shares closed at $6.25 before the report, down 11.8% since the opening after the July release and 22.3% below the 200-day moving average of $8.05. The stock set a 52-week low of $5.87 on September 30 and entered earnings only 6.5% above that level, well off the $7.52 inter-earnings high. Price, momentum and AVWAP trend readings all remain negative. That backdrop explains why a sizable EPS beat may not be enough on its own: the market has been pricing in shrinking revenue, and the guidance did not refute that.
The bottom line is that Western Union showed its cost program is working, with sequential margin and EPS recovery that turnaround skeptics may have underestimated. However, the beat leaned partly on a low tax rate, revenue guidance fell again, and Q4 faces a known digital headwind. The outcome of the Intermex deal over the next several days now matters more to the near-term investment case than the quarter's EPS surprise.
Read our earnings preview for The Western Union Company: https://www.earningswhispers.com/article/WU/21973
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Oct-27 | |
| Oct-27 | |
| Oct-22 | |
| Oct-22 | |
| Oct-19 | |
| Oct-19 | |
| Oct-14 | |
| Oct-12 | |
| Oct-07 | |
| Sep-30 | |
| Sep-30 | |
| Sep-16 |
