Veracyte Matches The Whisper, But A Decipher Reset And A Soft 2027 Preview Overshadow The Quarter
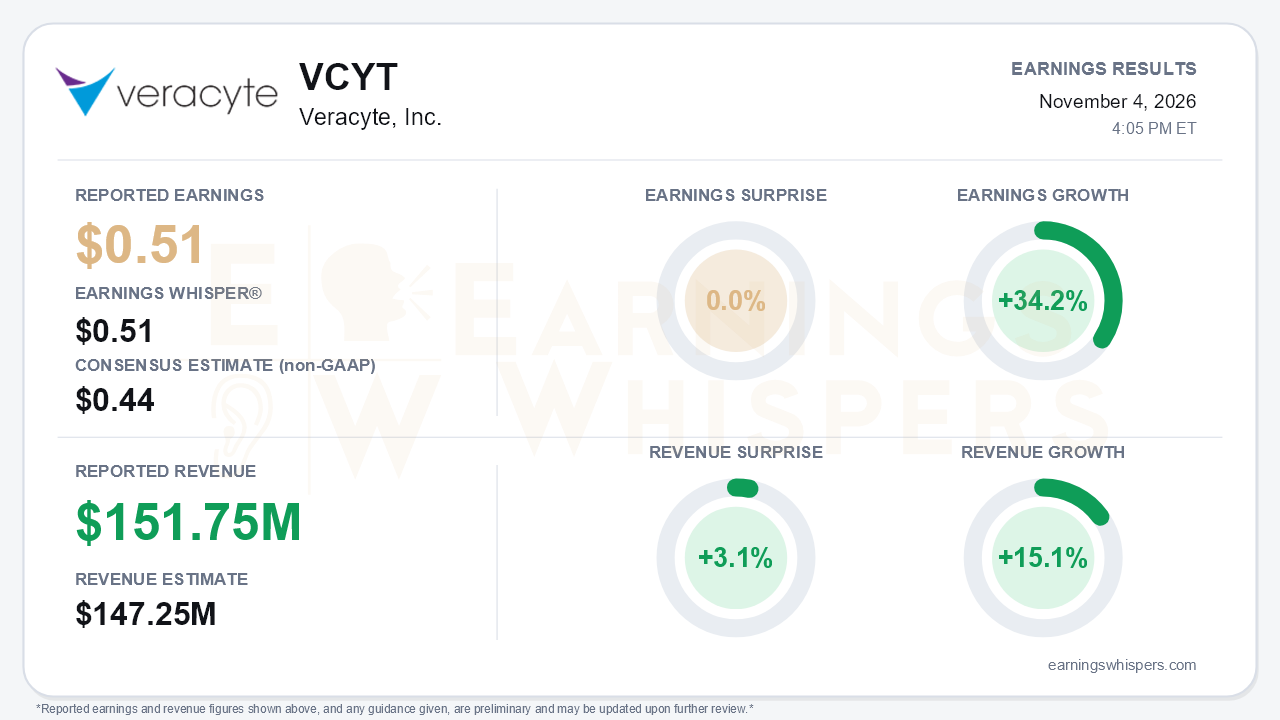
Veracyte (NASDAQ: VCYT) delivered a quarter that looked fine on paper and much worse in its outlook. Earnings of $0.51 per share matched the Earnings Whisper number, topped the $0.44 consensus, and grew 34.2% year over year on Earnings Whispers' normalized basis. Revenue of $151.75 million rose 15.1% and beat consensus by 3.1%. The second consecutive Decipher Prostate volume miss, a reset of that franchise's growth algorithm, and a preliminary 2027 view calling for only mid-single-digit revenue growth matter more than the headline. The quarter itself is not the problem. Veracyte's own forecast is.
The quality of the earnings deserves scrutiny. The company's non-GAAP diluted EPS was $0.51, the same as a year ago, which contrasts with the normalized growth figure. GAAP diluted EPS rose to $0.38 from $0.24, but a $10.4 million income tax benefit drove much of that gain. Adjusted EBITDA increased only 4% to $41.2 million, and the margin compressed to 27.2% from 30.1%. Non-GAAP operating expenses rose 24%, with non-GAAP R&D roughly doubling to $29.2 million. Non-GAAP gross margin of 73.7% was up year over year but down from 74.9% in Q2 and 75.7% in Q1. Revenue is growing, but costs are growing faster, and the margin trend has turned lower.
The call explained where the growth story bent. Decipher ran about 30,000 tests, up 12% but roughly 1,000 short of plan. Management had already trimmed its volume plan by about 1,000 tests last quarter, and growth has slowed from 24% in Q1 and 21% in Q4 2025. Management now expects 12,000 to 15,000 incremental Decipher tests per year, with 12,000 as the floor and the 2027 base case. That compares with the roughly 20,000 it cited only a quarter ago. Decipher's 2026 revenue growth assumption fell to about 16% from the roughly 20% reiterated all year, and Q4 volume is now expected to be about flat sequentially. Management cited three causes:
- normalization after two years of NCCN-driven growth;
- single-digit growth in low-risk patients;
- competitive digital pathology/AI promotion absorbing sales time.
The competitive point is a notable shift from earlier claims of no change in competitive dynamics. Afirma was the offset. It grew revenue 19% on 12% volume growth and posted its strongest sequential third quarter since 2020. Its 2026 growth outlook was raised to about 16% from 12% to 14%.
The net guidance effect was negative. Testing revenue guidance fell to $571-$573 million from $576-$582 million. Total revenue guidance narrowed to $590-$593 million, cutting the top end, while the >26% adjusted EBITDA margin target was held. The 2027 preview is the bigger issue. Management expects about 10% volume growth but only mid-single-digit revenue growth, citing tough comparisons and mix pressure. It also projects Afirma volume growth of about 5% and adjusted EBITDA of about 22%, with Q1 below that level. That margin outlook includes a roughly 30% urology sales-force expansion and ProSigna pricing near cost in the near term. The 'durable double-digit growth' language from earlier calls gave way to 'moderated near-term expectations.'
There are genuine catalysts:
- ProSigna secured Medicare coverage, and product revenue rose 40%.
- New predictive Decipher data from RTOG 0815 and STAMPEDE were presented, with STAMPEDE prognostic data added to NCCN guidelines.
- The $150 million Convergent Genomics acquisition builds out bladder testing, though the first UroAmp launch is not targeted until late 2028.
- A $100 million buyback was authorized, a reversal from Q2, when repurchases were 'not top of mind.' It is backed by $370.5 million in cash and investments and $40.3 million of quarterly operating cash flow.
Most of these catalysts pay off over years, while the guidance cuts hit now.
The market setup is more complicated than the in-line print implies. Investor sentiment remained slightly negative heading into the report but improved, moving from -0.105 to -0.037. Shares closed at $50.29 before the release, up 3.1% since the open after the July report and 17.2% above the 200-day moving average. They sat just 4% below the inter-earnings high of $52.39 set on October 29, after rallying 31.5% off a September low of $38.25. Momentum and AVWAP trend readings were positive. In short, the stock entered the report near the top of its range, with expectations recovering just as management reset the growth outlook.
The bottom line is that Veracyte's third quarter was solid, but the investment case changed. Decipher, the company's largest franchise, has shifted from a roughly 20,000-test annual growth engine to a 12,000-to-15,000-test one. The 2027 outlook implies slower revenue growth and a step down in margins. Afirma strength, ProSigna reimbursement, the bladder build-out, and the buyback give bulls something to hold onto. Bears, however, have legitimate ammunition in the guidance cuts and in a stock that entered the report pricing in a healthier trajectory than management now describes.
Read our earnings preview for Veracyte, Inc.: https://www.earningswhispers.com/article/VCYT/21963
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 3 hours | |
| 5 hours | |
| Nov-02 | |
| Oct-29 | |
| Oct-27 | |
| Oct-23 | |
| Oct-19 | |
| Oct-16 | |
| Oct-14 | |
| Oct-06 | |
| Sep-29 | |
| Sep-28 | |
| Sep-25 | |
| Sep-22 |
