Tigo Energy Breaks Even And Beats, But A Second Straight Guidance Cut Shows The Recovery Slipping Further Away
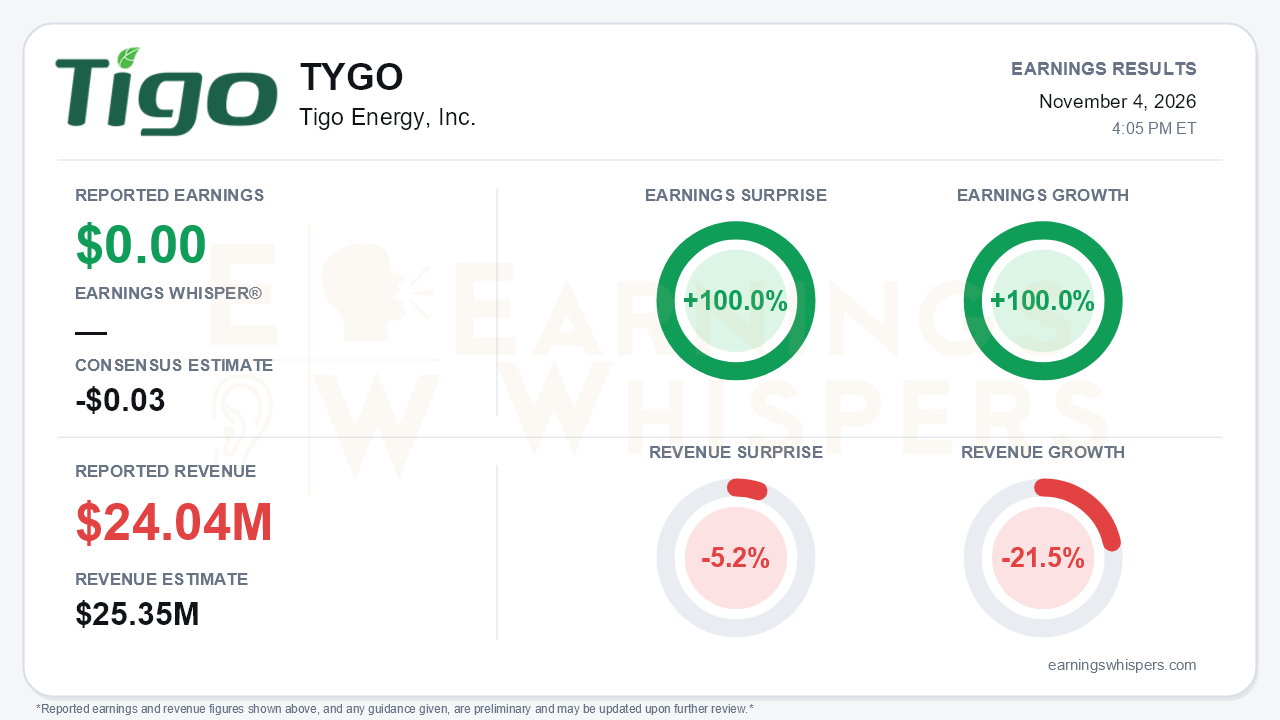
Tigo Energy (NASDAQ: TYGO) reported breakeven third-quarter results of $0.00 per share against a consensus estimate of a $0.03 loss. That works out to a 100.0% earnings surprise and 100.0% year-over-year earnings growth from the $0.03 loss a year earlier. The top line told a different story. Revenue of $24.04 million fell 21.5% from a year ago and missed the $25.35 million consensus by 5.2%. It landed at the bottom of management's $24 million to $26 million guide and declined 5.4% sequentially. That is the central tension. The bottom line improved even as the business shrank. Management then cut full-year 2026 revenue guidance for the second consecutive quarter, to $95 million to $97 million from $100 million to $110 million. Earlier in the year the outlook stood at $130 million to $135 million. The new range now sits below 2025's $103.5 million, so management has abandoned its earlier expectation of a roughly flat year.
The quality of the beat deserves scrutiny. Reported gross margin rose to 46.2% from 42.7% a year ago and 39.3% in the second quarter. However, gross profit included a $0.8 million tariff refund tied to prior periods. Without it, margin would have been roughly in line with last year. Adjusted EBITDA of $1.5 million topped the high end of guidance, which ran from a $1 million loss to a $0.5 million profit, and rose from about $52,000 in the second quarter. Yet that figure was lower than the $2.9 million posted a year ago, and the same non-recurring refund accounts for more than half of it. On a GAAP basis, Tigo actually posted a $77,000 operating loss. The $361,000 of net income, its second straight GAAP profit, relied on a $306,000 tax benefit and other income. The year-over-year earnings swing comes mostly from the balance sheet rather than operations: interest expense collapsed from $2.86 million to $101,000. Per-share comparisons also absorb a larger share count of 77.0 million basic shares versus 65.7 million, reflecting equity raised this year.
Cost and working-capital discipline is real.
- Operating expenses fell 10.0% year over year to $11.2 million, down from $11.7 million in the second quarter and $13.2 million in the first.
- Inventory dropped to $18.1 million from $31.3 million at year-end.
- Revolver borrowings were cut to $2.5 million from $4.1 million last quarter.
Still, nine-month operating cash flow was an $8.3 million outflow, largely because payables were paid down by $18.1 million. Cash of $16.8 million was supported by $14.25 million of stock issuance. Credit quality is a growing concern. The quarter carried $0.4 million of bad debt, including a charge tied to a single European customer, following a $1 million distributor bankruptcy in the first quarter. Receivables also edged up to $15.0 million.
The call made clear that demand weakness is broadening rather than stabilizing. Management described a reset in residential subsidies across several markets:
- Germany, where a pending feed-in law has customers waiting.
- The Czech Republic, which now has a 50% export cap.
- Italy.
- The U.S., where the 25D credit expired.
EMEA, 76.5% of revenue, fell 14.8%, and U.S. revenue dropped 51.4%. The GO ESS storage line keeps contracting, from $4.0 million in the first quarter to $2.2 million in the second and $1.3 million in the third. Utility-scale deals highlighted earlier in the year still have not closed, and a large Japan project has slipped to early 2027. The tone has shifted noticeably. Earlier in the year, management spoke of a strong start and accelerating growth. Now the emphasis is on cost control, and there is no 2027 guidance.
There are genuine pockets of growth.
- APAC grew 56.3%, led by 121.1% growth in Australia.
- Poland rose 41.2%.
- Spain more than doubled. The release cites 103.2% growth, while call commentary referenced a higher figure.
- The U.S. optimized inverter partnership finally produced about $0.8 million of revenue, and management expects more in the fourth quarter.
- Management framed the FCC restriction on foreign-produced inverters as a potential opening for U.S.-made product.
However, the partner's launch has been repeatedly delayed and is outside Tigo's control. Management itself warned the delay may affect the timing of future orders. Fourth-quarter guidance of $20 million to $22 million in revenue and an adjusted EBITDA loss of $1.5 million to $3.0 million shows that these bright spots are not yet offsetting the core residential decline.
The market had largely braced for this. Investor sentiment was essentially unchanged and firmly negative, moving from -0.484 to -0.488. Shares entered the report at $0.92, down 29.6% since the open following the prior report. They traded 65.1% below the 200-day moving average of $2.62. The stock set a 52-week low of $0.79 in late September and has recovered only about 16% from that level, well below the $1.40 inter-earnings high. The Earnings Whispers trend signals remain mostly negative, with price, momentum and AVWAP readings all weak. With the stock under $1, the company's own risk disclosures flag Nasdaq listing compliance as a consideration.
The bottom line is that Tigo delivered a cleaner income statement and a healthier balance sheet, but the earnings beat leaned on a one-time tariff refund and below-the-line items. Meanwhile, revenue, storage sales and guidance all moved the wrong way. Bears have legitimate ammunition in a second consecutive outlook cut and a guided return to EBITDA losses. Any rerating likely depends on the inverter partnership and the faster-growing regions proving large enough to outrun the residential subsidy reset.
Read our earnings preview for Tigo Energy, Inc.: https://www.earningswhispers.com/article/TYGO/21959
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 5 hours | |
| 15 hours | |
| Oct-27 | |
| Oct-22 | |
| Oct-21 | |
| Oct-13 | |
| Oct-12 | |
| Oct-05 | |
| Oct-05 | |
| Oct-01 | |
| Oct-01 | |
| Sep-30 | |
| Sep-28 | |
| Sep-10 |
