ONE Group's Operating Repairs Can't Outrun A Third Guidance Cut And A Wider-Than-Expected Loss
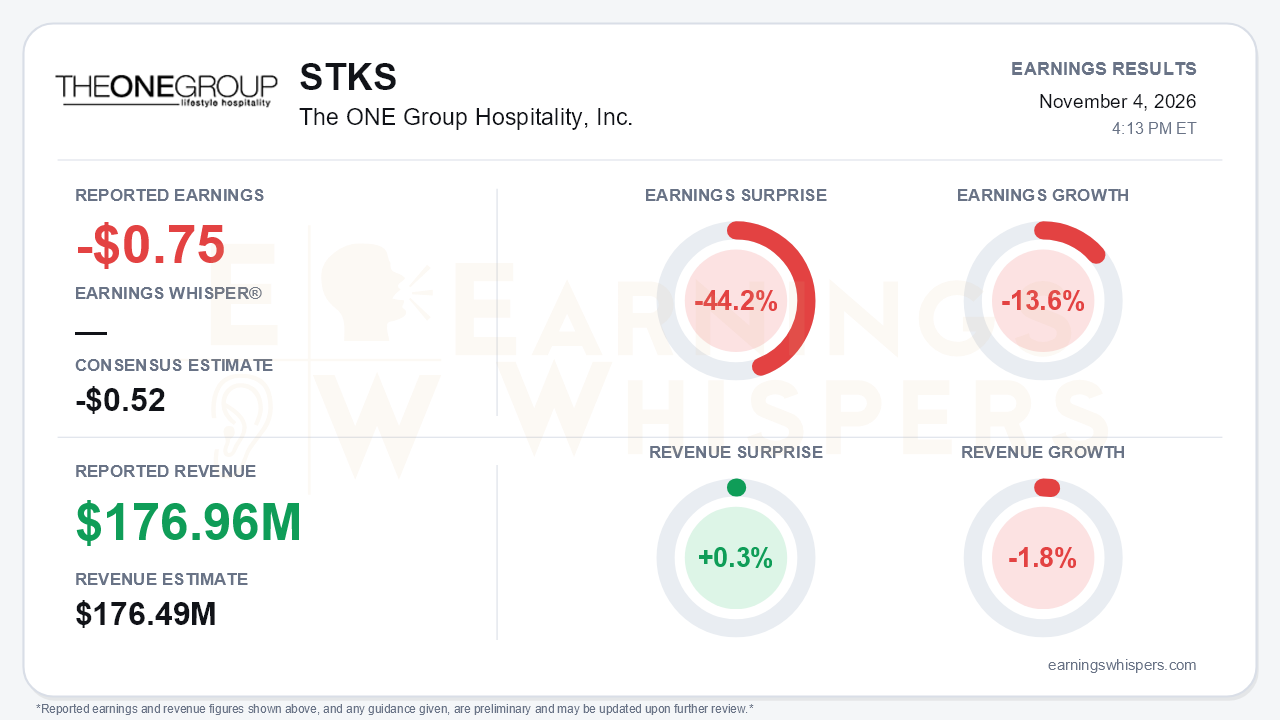
The ONE Group Hospitality (NASDAQ: STKS) reported a third-quarter loss of $0.75 per share, well short of the -$0.52 consensus. That is a 44.2% negative surprise, and earnings fell 13.6% year over year. Revenue of $176.96 million edged past the $176.49 million consensus by 0.3% but declined 1.8% from a year ago. Management also lowered full-year guidance for the third straight quarter. The central tension is that restaurant-level operations are improving in ways that matter: traffic, cost of sales, restaurant margins and operating cash flow are all moving in the right direction. Yet the company missed its own quarterly targets again, and the common shareholder sits behind a growing preferred claim and roughly $348 million of high-cost debt.
The quality of the quarter deserves scrutiny. The release shows a GAAP diluted loss of $0.79 per share versus $2.59 a year earlier. That apparent improvement is flattered by a $59.1 million tax provision and a $3.4 million impairment in the prior-year period. Net loss attributable to the company was $16.1 million. However, the Series A preferred paid-in-kind dividend and accretion rose to $10.3 million from $8.5 million, which pushed the loss available to common holders to $26.4 million. The preferred carrying value has climbed to $220.9 million from $191.3 million at year-end, and the stockholders' deficit widened to $117.7 million. Below the restaurant line, pre-opening expense nearly quadrupled to $2.7 million, and interest consumed $10.0 million. Those two items are why a 190-basis-point margin gain still produced an operating loss.
The operating story is genuinely better. Restaurant operating profit rose to 13.2% of owned revenue from 11.3%. Cost of sales fell to 19.5% from 21.1% on the beef strategy and menu work. Benihana led the improvement, with restaurant margin up to 15.8% from 13.9%, transactions up 2.7% and comps up 0.7%. Consolidated traffic grew 1.8%, the second straight positive quarter. But comps slipped 0.4%, against a 0-2% guide, and the gap between traffic and sales points to check dilution from value-oriented promotions in a cautious consumer environment. STK owned comps turned negative at -1.2% after +2.5% in Q2. The Grill portfolio remains the weak link: Grill comps fell 4.0%, and core Grill restaurant operating margin slipped to 3.0% from 4.0%. Adjusted EBITDA of $11.1 million rose 5% but missed management's $12-15 million guide. That follows a Q2 miss as well, and management also cited late-September East Coast weather.
Guidance is where credibility erodes:
- Revenue has moved from $840-855 million at Q1 to $805-820 million at Q2 to $800-810 million now.
- Comps have gone from 1-3% to roughly 1%.
- Adjusted EBITDA has narrowed from $100-110 million to $95-100 million.
- Fee revenue and venue openings were trimmed.
- Pre-opening, G&A and capex targets were nudged higher.
The offsets are real. Year-to-date operating cash flow more than doubled to $41.8 million after $29.4 million of interest, and debt fell about $6 million. Beef costs are now contracted to roughly September 2027, the buyback authorization grew by $5 million, and transition and integration costs are expected to end after Q3. Benihana Express is the most interesting catalyst. The Miami prototype is pacing at $1.8 million annually, up from roughly $1.2 million cited last quarter, and the franchise team is being refocused on licensing the format. The trade-off is that non-Express licensing is being deferred, and the Q2 license deals were not reiterated. Seven closed Grill units await Benihana conversions mostly slated for 2027, which will weigh on near-term revenue.
Liquidity is thin enough to keep bears engaged. Cash was just $3.6 million, with $40.3 million of total short-term liquidity including the revolver, against a weighted-average debt cost around 10.2%.
Investor sentiment moved from modestly negative (-0.13) to modestly positive (+0.10) heading into the report. That suggests some expectation that the cost and traffic work would show through. The stock tells a harsher story. As of the pre-report snapshot, shares were at $1.18, down 31.4% from the open after the August report. That is about 34% below the $1.80 200-day moving average and only 10% above the $1.07 52-week low set on October 21. The stock has given back the entire post-Q2 move to $1.85 and then some, and the Earnings Whispers trend readings remain mostly negative on price and AVWAP. Another guidance cut gives the market little reason to rerate quickly.
The bottom line is that ONE Group is fixing the restaurant box faster than it is fixing the equity story. Margins, traffic, Benihana execution and cash generation all improved, and Benihana Express offers a plausible asset-light growth path. But a sizable EPS miss, a second straight EBITDA shortfall against its own guide, and a third consecutive downward revision leave management's forecasts in question. Rising preferred accretion and leverage further limit how much operating progress reaches common shareholders. Until comps convert traffic into sales and guidance stops moving lower, the improving operations are likely to remain overshadowed by the capital structure.
Read our earnings preview for The ONE Group Hospitality, Inc.: https://www.earningswhispers.com/article/STKS/22521
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Oct-30 | |
| Aug-10 | |
| Aug-10 | |
| Aug-05 | |
| Aug-05 | |
| Aug-03 | |
| Jun-03 | |
| May-28 | |
| May-11 | |
| May-06 | |
| May-06 | |
| May-01 |
