Sight Sciences Lands A Record Top-Line Beat And Third Straight Guidance Raise, But Misses The Whisper And Implies A Q4 Pause After A 63% Run
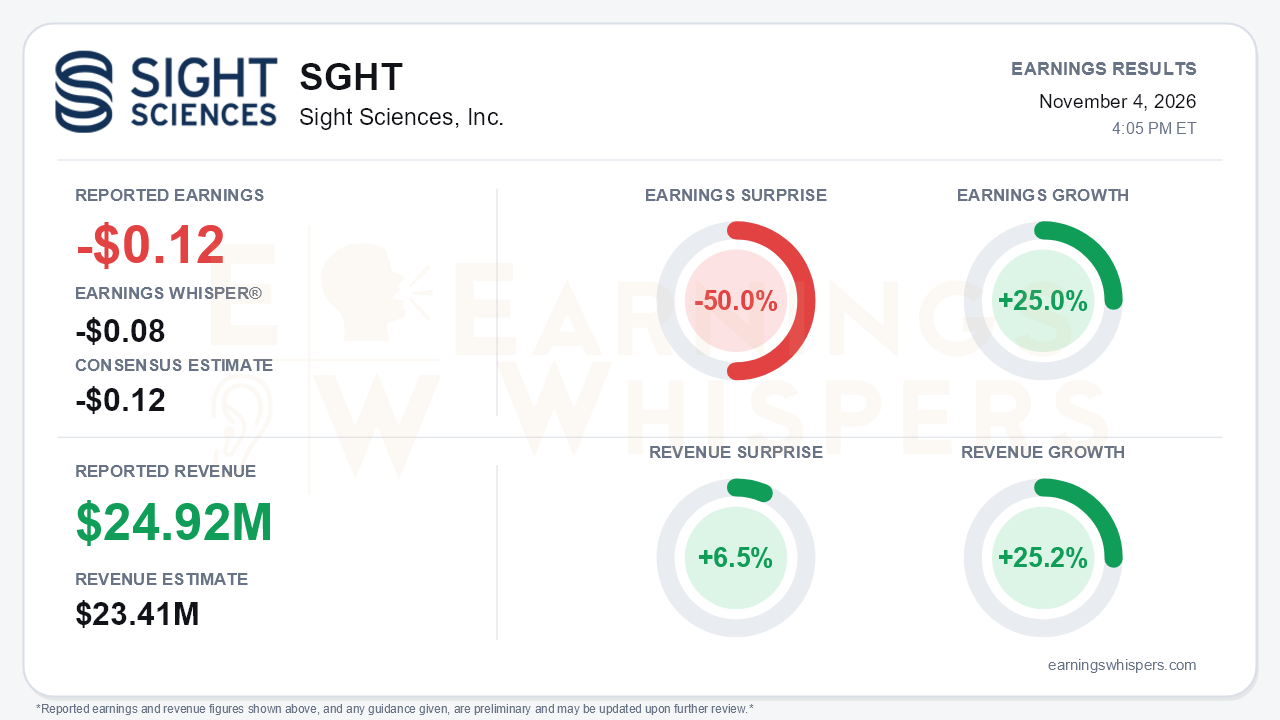
Sight Sciences delivered the revenue acceleration bulls wanted, but the bottom line fell short of the bar investors had set. The eyecare device maker reported a third-quarter loss of $0.12 per share. That matched the consensus estimate but missed the Earnings Whisper number of -$0.08, a 50.0% shortfall against that higher bar. Revenue was a record $24.92 million, beating consensus of $23.41 million by 6.5% and growing 25.2% year over year. Earnings improved 25.0% from the prior-year loss of $0.16 per share. Management raised full-year revenue guidance for the third consecutive quarter. The central tension is the stock's run into the report: shares had climbed 63.3% since the prior report's open, so a strong quarter met elevated expectations and a guide that implies a sequential pause.
The top-line trajectory is the most important development. Quarterly revenue growth has stepped up from 7% in the fourth quarter of 2025 to 13%, then 20%, and now 25%. Interventional Dry Eye (IDE), driven by TearCare, did most of the work. IDE revenue reached $3.9 million, up from $0.2 million a year ago and 45% higher than the second quarter. IDE gross margin rose to 79% from 38% a year ago, so the new engine is now scaling profitably rather than diluting the mix. Interventional Glaucoma (IG) grew a steadier 7% to $21.0 million, its fifth straight growth quarter, with active customers rising to 1,253 from 1,197.
The earnings quality is more nuanced. Cash usage fell to just $2.4 million from $9.1 million a year earlier, a 74% reduction. Year to date, revenue is up 19% while adjusted operating expenses are down 2%. But third-quarter adjusted opex rose 21% year over year to $24.0 million as the company invests behind the IDE commercial ramp. The GAAP net loss of $6.8 million also widened from $4.4 million in the second quarter, although the second quarter was flattered by tariff refunds. That pattern helps explain why the company met consensus but missed the whisper: revenue beat, yet spending absorbed much of the upside.
The call reinforced a credible two-engine growth story. IDE ordering accounts climbed from 176 to 222 sequentially, and SmartLids per account rose from roughly 18 to 21, which points to both breadth and depth of adoption. Full-year IDE guidance has moved from an initial $5-7 million to roughly $12 million. Total revenue guidance now stands at $92-93 million, about 20% growth, up from $82-88 million at the start of the year. Adjusted opex guidance was held at $92-94 million. Management sounded noticeably more confident, citing 'two strong engines' and a return to high growth. It also reiterated that no equity raise is needed to reach cash-flow breakeven, a claim aided by a six-month extension of the debt's interest-only period to August 2027.
The forward catalysts are tangible:
- an August FDA label expansion for TearCare;
- the full U.S. launch of OMNI Ultra at AAO, with broad adoption expected in 2027;
- Aetna coverage of OMNI and SION adding roughly 25 million covered lives.
Bears have legitimate ammunition, however. The raised guidance implies fourth-quarter revenue roughly flat to down from the third quarter at the high end. The roughly $12 million IDE target implies only about 6% sequential growth after a 45% jump; management characterized this as conservatism. Additional payer coverage decisions slipped from 'this year' to 'coming quarters.' The Alcon appeal of a roughly $55 million judgment remains unresolved, with no cash received, and no 2027 guidance was offered.
The market setup is more complicated than the revenue beat implies. Investor sentiment remained positive but weakened sharply, falling from 0.34 to 0.09 heading into the report. That suggests enthusiasm cooled even as the stock rallied. Shares entered the print at $9.42, about 3% below the 52-week high of $9.71 set on September 29 and roughly 57% above the 200-day moving average of $6.01. The Earnings Whispers trend signals are mostly positive, though sequential growth reads neutral, consistent with a guide that flattens the near-term curve.
The bottom line is that Sight Sciences' fundamentals improved meaningfully: growth accelerated for a fourth straight quarter, IDE is scaling at high margins, and cash burn has nearly disappeared. But a stock sitting near its highs after a 63% run needed more than an in-line loss and a guide implying a fourth-quarter plateau. Whether management's conservatism proves real, and whether delayed payer decisions arrive, will determine if the next leg of growth justifies the rerating already in the price.
Read our earnings preview for Sight Sciences, Inc.: https://www.earningswhispers.com/article/SGHT/21936
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 4 hours | |
| Oct-27 | |
| Oct-21 | |
| Oct-01 | |
| Sep-01 | |
| Aug-19 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 | |
| Jul-22 | |
| May-06 | |
| Apr-29 |
