Biote Swings To A Penny Profit And Holds Its Reduced Guidance, But Procedure Revenue Keeps Shrinking
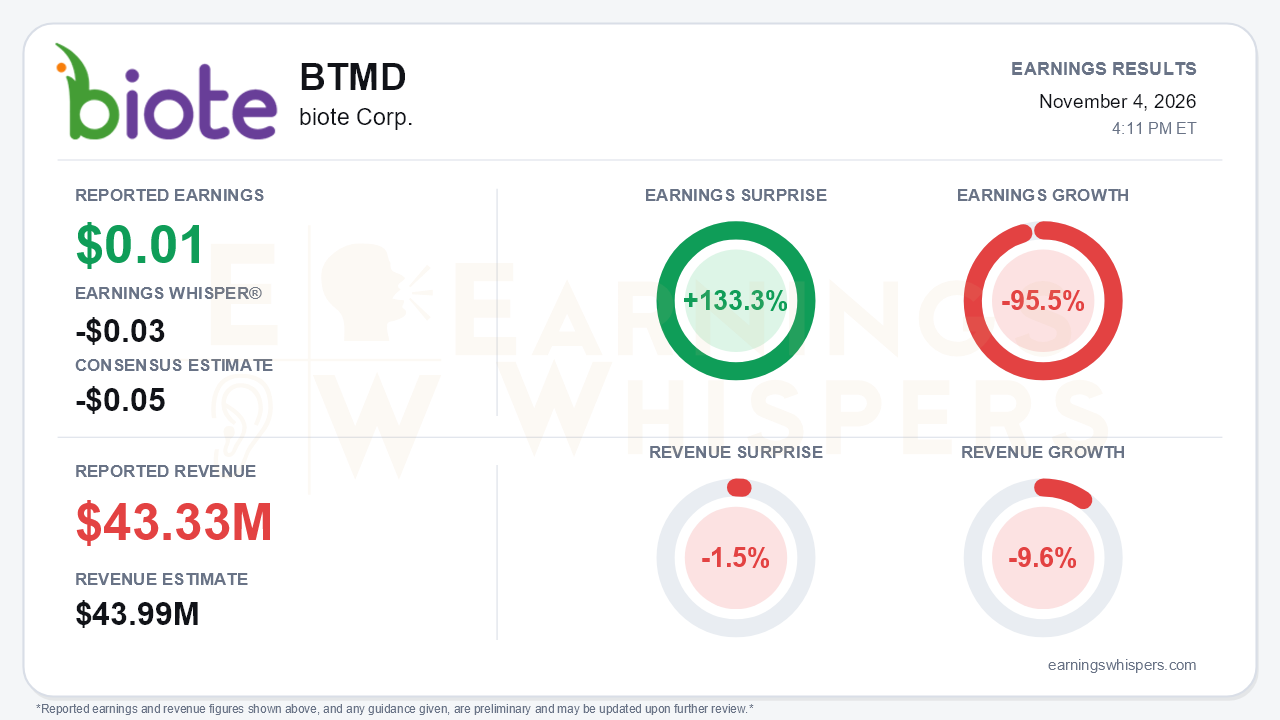
biote Corp. (NASDAQ: BTMD) reported third-quarter earnings of $0.01 per share, against a consensus estimate of a $0.05 loss and an Earnings Whisper number of a $0.03 loss. That works out to a 133.3% earnings surprise. Revenue of $43.33 million missed the $43.99 million consensus by 1.5% and fell 9.6% year over year. Earnings fell 95.5% from the $0.22 the company earned a year ago. The EPS beat looks good on paper, and the swing from a $7.4 million GAAP loss in the second quarter to a $0.6 million profit is real. Still, the central tension is that the business biote most needs to fix, its pellet procedure franchise, deteriorated again. The upside came from cost relief and margin repair, not demand.
The quality of the beat deserves scrutiny. Pre-tax income was $1.4 million, and $1.0 million of that came from a non-operating gain on the fair value of earnout liabilities. Without that gain, the profit would have been close to breakeven. The bigger sequential driver was SG&A, which fell 20.8% to $26.8 million from $32.4 million in Q2 as legal settlement costs rolled off. Adjusted EBITDA, the measure management guides to, slipped to $5.1 million from $5.6 million in the second quarter and $8.7 million in the first. Adjusted EBITDA margin was 11.7%, compared with 26.9% a year earlier. On the metric that strips out one-time items, profitability is still moving the wrong way.
The top line shows the deceleration plainly. Procedure revenue fell 15.1% to $28.9 million, worse than the 13.2% decline in Q1. It was also below second-quarter levels, even though management had called for sequential improvement in the back half on the prior call. Total revenue declines widened from 8.3% in Q1 to 9.6%. Dietary supplements were the lone growth engine, rising 7.3% to $12.0 million, up from 5.7% growth in Q2. Interim CEO Bob Peterson acknowledged that the return to growth is "progressing more slowly than anticipated." He cited only "early evidence of stabilization" in modest increases in daily procedure volume. Management offered no normalized growth algorithm and no commentary on 2027.
The credible part of the story is gross margin. It recovered to 67.7% from 65.4% in Q2 as Asteria Health returned to pre-recall output. Asteria now supplies more than 50% of shipped pellets, compared with roughly 30% earlier in the year, which reduces reliance on lower-margin third-party product. Management expects further sequential margin gains. Operating cash flow turned positive at $3.7 million after a $1.2 million outflow in Q2. Other potential catalysts include:
- the work of new Chief Medical Officer Dr. Komal Bajaj on practitioner engagement;
- an upgrade of roughly 50 sales reps;
- a revamped competitive region showing same-store growth and win-backs.
These are early operating signals rather than proof of a turnaround.
The balance sheet and leadership add risk. Cash fell to $8.9 million from $11.2 million at the end of Q2 and $24.1 million at year-end 2025. Meanwhile, term debt sits near $120 million and the company spent $7.2 million on buybacks this year. Peterson now serves as both interim CEO and CFO following Brett Christensen's departure, and Marc Beer is executive chairman. The reaffirmed outlook calls for revenue above $175 million and adjusted EBITDA above $25 million. That is the same guidance already cut from above $190 million and above $38 million last quarter. Based on nine-month results, it implies fourth-quarter revenue of at least roughly $42.5 million and adjusted EBITDA of about $5.6 million or more. Revenue at that level is achievable at current run rates. The EBITDA target requires a reversal of this quarter's sequential decline.
The market had already priced in heavy skepticism. Shares were at $1.12 entering the report, down 41.4% since opening at $1.91 after the August release. They sat 38.4% below the 200-day moving average of $1.82. The stock set a 52-week low of $1.00 on October 13 and was trading just 12% above that level. Investor sentiment became meaningfully more negative, falling from -0.53 to -0.71. The Earnings Whispers trend signals are uniformly negative, with sequential growth and momentum still deteriorating. A penny of profit against a modeled loss may relieve some near-term pressure, but bears retain legitimate ammunition in the procedure trend.
The bottom line is that biote delivered a cleaner quarter on margins, costs, and cash flow. However, it did not deliver the evidence of procedure stabilization that the investment case depends on. Until procedure revenue stops shrinking and adjusted EBITDA turns up sequentially, the beat reads more as damage control than as an inflection point.
Read our earnings preview for biote Corp.: https://www.earningswhispers.com/article/BTMD/21796
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Oct-27 | |
| Oct-21 | |
| Aug-06 | |
| Aug-04 | |
| Jul-22 | |
| Jun-01 | |
| May-28 | |
| May-06 | |
| Apr-22 | |
| Mar-11 | |
| Mar-11 | |
| Mar-11 | |
| Mar-10 |
