Bio-Rad Returns To Currency-Neutral Growth As Margin Gains Carry A Modest EPS Beat; Top Line Still Falls Short
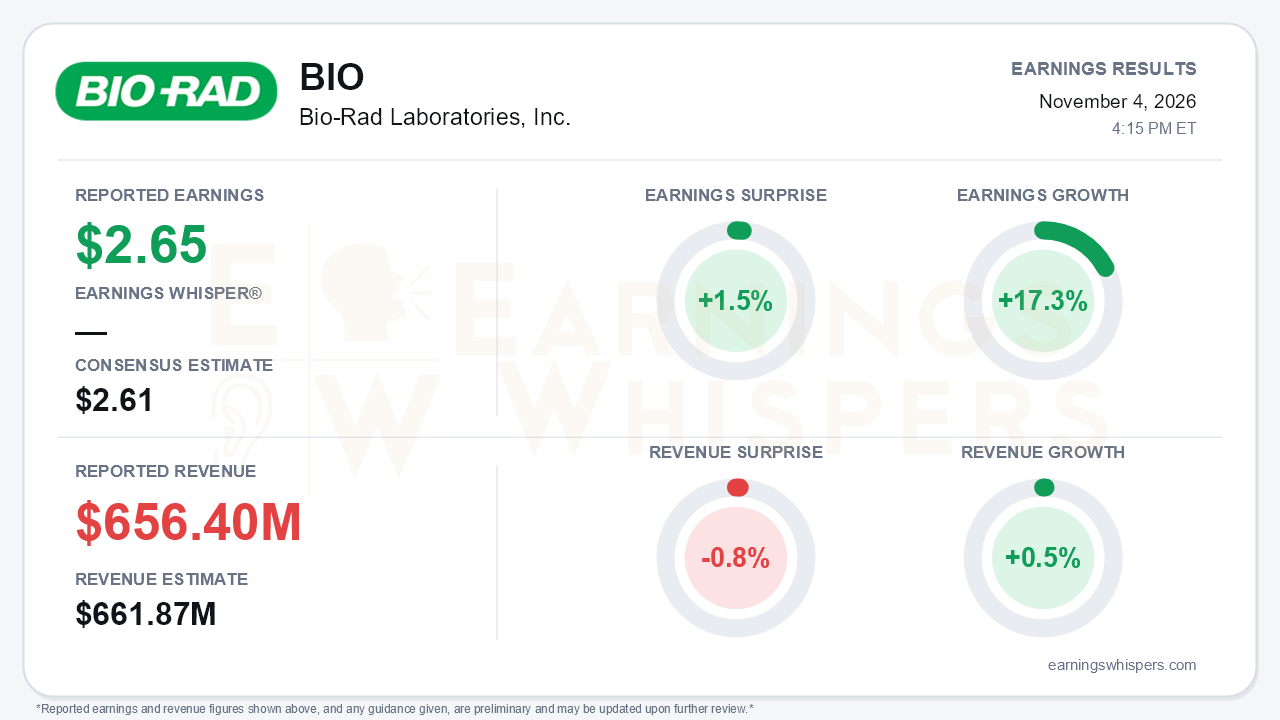
Bio-Rad Laboratories delivered non-GAAP earnings of $2.65 per share for the third quarter, beating the $2.61 consensus by 1.5% and rising 17.3% from a year ago. Revenue of $656.4 million grew just 0.5% and missed the $661.87 million consensus by 0.8%. The central takeaway is that Bio-Rad's earnings recovery is running well ahead of its revenue recovery. Margin expansion is real and broadening. The top line is still essentially flat, and the funding environment for a key customer group just got worse.
The quality of the beat deserves scrutiny. Non-GAAP operating income rose to $83.7 million from $77.0 million, and operating margin widened to 12.8% from 11.8%. Gross margin also improved to 54.5% from 53.5%. Part of that leverage, however, came from non-GAAP R&D spending, which fell to $60.0 million from $70.2 million as management reprioritized research programs. Below the operating line, the non-GAAP tax rate dropped to 21.4% from 26.7% on geographic mix. That is why non-GAAP net income grew about 18% even though pretax income rose roughly 10%. The GAAP picture is noisier still. A $588.2 million mark-to-market gain on the Sartorius stake produced GAAP EPS of $17.02. Strip that out, and GAAP operations swung to a $49.7 million loss on $77.2 million of restructuring charges and a $49.8 million impairment of life science intangibles. Cash generation also lagged. Free cash flow was $65.2 million versus $89.2 million a year earlier, and the nine-month total of $210 million leaves meaningful ground to cover against the reaffirmed $290–340 million full-year target.
Beneath the headline, the trajectory is clearly improving. Currency-neutral revenue rose 0.7%, Bio-Rad's first growth quarter of the year, after declines of 1.9% in Q2 and 4.2% in Q1. Clinical Diagnostics grew 2.8% currency-neutral, up from 0.3% and -4.1% in the prior two quarters, led by quality controls and diabetes. Life Science overall still fell 2.4% on weaker process chromatography and academic demand. Excluding process chromatography, however, the segment grew 2.5%, the third straight quarter of sequential improvement. Droplet Digital PCR grew 7%, and instrument revenue rose more than 20% for a third consecutive quarter. Margin progression was equally steady. Non-GAAP operating margin went from 6.6% in Q1 to 12.5% in Q2 to 12.8% in Q3.
Guidance tells a more measured story. Management reaffirmed currency-neutral revenue of -3% to +0.5% and pinned it to roughly the midpoint. It steered gross margin to the upper half of 53–54% and operating margin to the upper half of 10–12%. That is a margin raise, not a revenue raise, and every metric remains below the original targets that were cut in Q1. Bears have legitimate ammunition:
- NIH outlays fell about 15% year over year in the quarter, reversing the encouraging funding signals management cited in Q2. The Q4 outlook assumes no academic recovery.
- China's NHSA pricing guidelines are now expected to cost a mid-single-digit million dollars in revenue in 2027, after management said in Q1 it expected no impact.
- China's Q3 return to growth was largely order timing.
- ddPCR consumable pull-through may not normalize until 2027, while instrument comparisons get tougher.
- Q4 gross margin is expected to dip sequentially on instrument mix, lower process chromatography, and fuel costs.
On the other side, the ChemiDoc Pro imaging system launched about two quarters early, and biopharma recovery is broadening toward discovery customers. The $30–35 million in restructuring savings remains intact. Management described its dialogue with Elliott as productive and aligned, and board expansion is underway. Management also framed 2027 as a year of positive growth with further margin expansion. That remains a stated expectation, not a reported result.
The market had already moved toward this narrative. Investor sentiment improved from -0.24 to +0.02 heading into the report, a meaningful shift from negative to roughly neutral rather than outright enthusiasm. Shares traded at $374.91 ahead of the release, up 10.3% from the $340 open after the prior report. That left the stock 19.4% above its 200-day moving average but 5.4% below the 52-week high of $396.23 set in late August. The stock has therefore given back some of its post-Q2 run while holding most of the gain. The Earnings Whispers trend signals lean positive, with sequential growth and AVWAP readings favorable and price and momentum neutral. That setup leaves less room for a revenue miss than the depressed sentiment of a quarter ago did.
The bottom line is that Bio-Rad is executing the margin side of its turnaround convincingly, with three quarters of steady improvement and full-year targets nudged higher. Revenue growth remains barely positive, missed expectations, and faces renewed academic and China headwinds that now extend into 2027. With the stock well above its long-term average and sentiment no longer bearish, the next leg depends on whether top-line growth can catch up with the margin story.
Read our earnings preview for Bio-Rad Laboratories, Inc.: https://www.earningswhispers.com/article/BIO/21793
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Oct-29 | |
| Oct-27 | |
| Sep-24 | |
| Sep-16 | |
| Sep-08 | |
| Aug-31 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 | |
| Jul-30 | |
| Jul-23 | |
| May-22 | |
| May-18 |
