BBSI Hits In-Line $0.69 But Trims 2026 Outlook A Third Time, Leaning On A 2027 Recovery Story
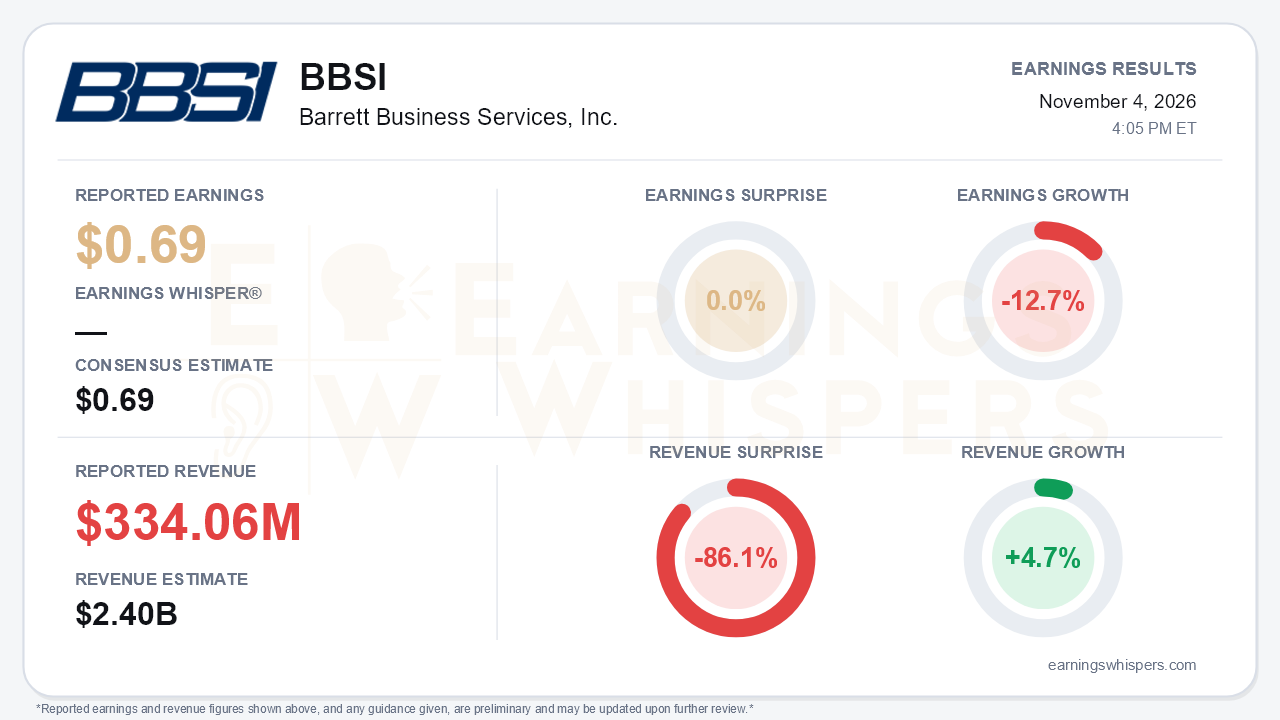
Barrett Business Services delivered exactly what Wall Street expected in the third quarter: earnings of $0.69 per share, matching consensus. Earnings still fell 12.7% from a year ago. Revenue grew 4.7% to $334.06 million. The reported revenue shortfall of 86.1% against a $2.40 billion consensus needs context. That consensus figure matches the company's gross billings, which came in at $2.40 billion and rose 3%. BBSI reports PEO revenue net of direct payroll costs, so the headline revenue miss reflects a mismatch in what was being measured rather than an operating collapse. The real story is not the in-line print. This was the third consecutive call in which management trimmed its 2026 outlook, while asking investors to look toward a firmer 2027.
The quality of the quarter deserves scrutiny, because the earnings decline was concentrated in gross margin. Gross margin fell to $72.7 million from $76.8 million. As a share of gross billings, it slipped to 3.0% from 3.3%. Two factors did most of the damage:
- **Benefit costs** rose to 1.3% of billings from 0.9%, reflecting growth in the company's benefits offering.
- **Workers' compensation reserve releases shrank.** Favorable prior-year adjustments were just $0.8 million, versus $3.9 million a year earlier. Year to date they total $3.9 million against $16.5 million in 2025.
That second point matters. A meaningful slice of last year's profitability came from reserve releases that are no longer recurring at the same scale. Net income fell to $16.8 million from $20.6 million. A diluted share count of roughly 24.4 million, down from 26.2 million thanks to buybacks, cushioned the per-share decline. Investment income also fell to $1.2 million as cash went to repurchases. SG&A, down about 2% year over year, was a genuine bright spot. On a GAAP basis, nine-month EPS of $0.60 still carries the first-quarter $11.6 million charge for disallowed prior-year tax credits. Excluding that charge, nine-month EPS was $1.06.
Beneath the headline, the volume engine remains the weak link. Average worksite employees grew just 0.6%, compared with 6.1% growth in the year-ago quarter. Controllable WSE additions slowed to about 3,100 year over year. That compares with roughly 4,500 in the second quarter and 8,300 in the fourth quarter of 2025. Management again cited soft client hiring. As a result, full-year average WSE growth guidance was cut to 1-2%, down from 2-3% last quarter and 2-4% originally. Gross margin is now expected at the low end of a 2.70-2.75% range, which had already been narrowed from 2.70-2.85%. Gross billings guidance held at 3-4%, but only after a prior cut from 3-5%.
Pricing and mix are doing the heavy lifting. Several trends improved for a third straight quarter:
- **Billing per WSE per day** rose 2.7%, up from 2.2% in the second quarter and 1.7% in the first.
- **Gross billings growth** improved to 3.2% from 2.6% in the second quarter.
- **Staffing's decline** narrowed to 7%, from 18% in the second quarter.
That is why the call preserved a credible, if deferred, recovery narrative. Workers' comp pricing has now risen for 11 consecutive months. Management said pricing more than offsets current-year cost increases and described 2026 as the low watermark for margin. Forward indicators also strengthened:
- Benefits submissions rose about 30% in the third quarter, and October submissions for January 1, 2027 effective dates jumped roughly 55%.
- White-collar new business was up about 50%.
- Northern California returned to 2% growth, and the East Coast grew 18%.
- Pittsburgh converted from an asset-light market to a physical branch, with two more conversions expected within about four months.
Bears have legitimate ammunition, however. Southern California and the Mountain region each declined 1%. Buybacks slowed to $9 million from $15 million in the second quarter and $20 million in the first. With unrestricted cash and investments at $73.7 million, the per-share support that cushioned this quarter may be less forceful going forward.
Investor expectations were already sour heading into the report. Earnings Whispers sentiment deteriorated meaningfully, falling from -0.42 to -0.59. Shares closed at $32.73 before the release. That is 6.6% below the $35.03 opening price after the August report and essentially on top of the 200-day moving average at $32.92. The stock sits roughly midway in its inter-earnings range. It is 9.1% below the $36.00 high set the day after the last report and 9.3% above the $29.94 low touched on October 5. The market has steadily discounted the guidance erosion. The internal trend readings are mixed: price trend is negative, while sequential growth is positive, consistent with EPS rising from $0.52 in the second quarter.
The bottom line is that BBSI's in-line quarter changed little about 2026 and a lot about how much the bull case now rests on 2027. Shrinking reserve releases, rising benefit costs and stalled WSE growth define the current year, and another guidance trim keeps credibility under pressure. Firming workers' comp pricing, a surging benefits pipeline and improving billing per employee give management a plausible path to margin recovery. Investors will need to see that path show up in WSE growth and margins before sentiment meaningfully turns.
Read our earnings preview for Barrett Business Services, Inc.: https://www.earningswhispers.com/article/BBSI/21792
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Nov-02 | |
| Oct-27 | |
| Oct-21 | |
| Aug-05 | |
| Aug-05 | |
| Jul-22 | |
| May-06 | |
| May-06 | |
| Apr-28 | |
| Apr-22 | |
| Mar-11 | |
| Mar-03 |
