Alto Ingredients Clears A Low Bar As 45Z Credits Offset A Sharp Drop In Operating Profit
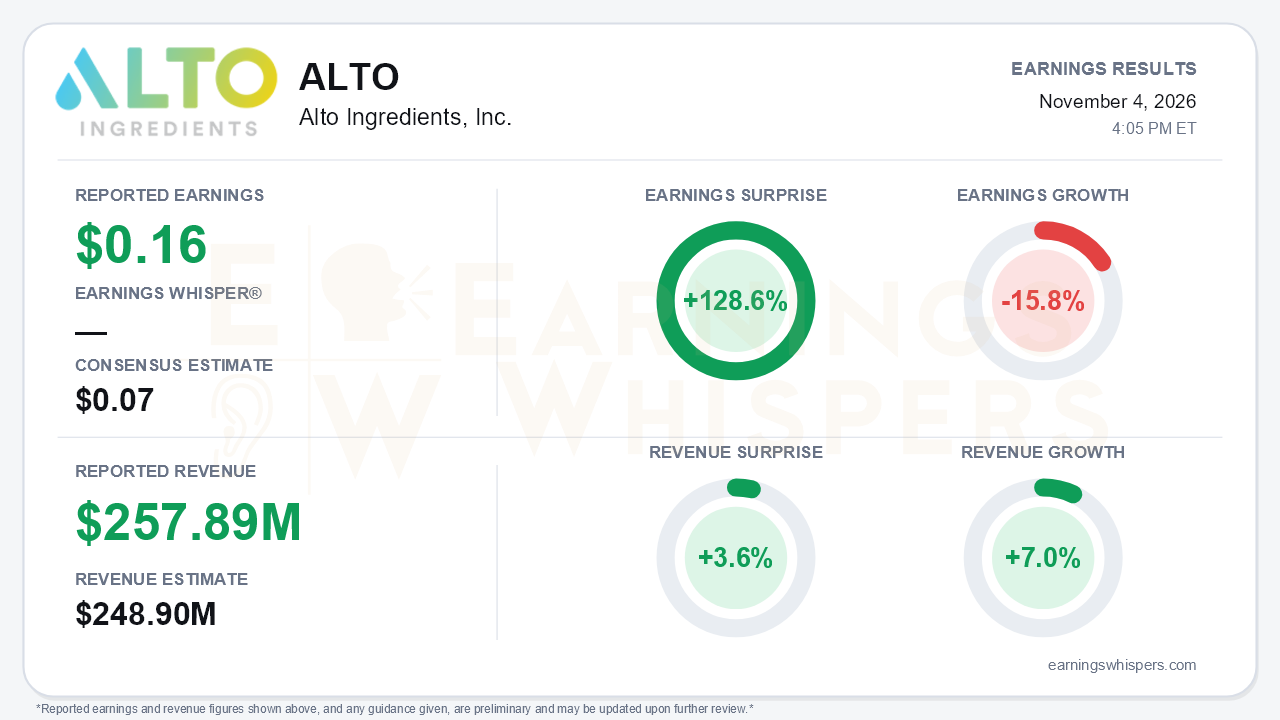
Alto Ingredients (NASDAQ: ALTO) posted third-quarter earnings of $0.16 per share, beating the $0.07 consensus estimate by 128.6%. Revenue of $257.89 million topped expectations by 3.6% and grew 7.0% year over year. Earnings still fell 15.8% from a year ago. The quality of the beat deserves scrutiny, and that is the central tension. Section 45Z transferable tax credits supplied $7.6 million of the quarter's $13.0 million pre-tax income. Income from operations, meanwhile, fell to $7.0 million from $17.0 million. The headline surprise reflects a policy-driven earnings stream layered on top of a core business that was materially less profitable than it was a year earlier.
The pressure is easy to locate. Gross profit dropped to $14.8 million from $23.5 million, and nearly all of the damage came from the Pekin Campus. Pekin's gross profit roughly halved, to $9.5 million from $18.9 million. Higher selling prices helped: the average sales price rose to $2.23 per gallon from $2.09. Corn costs worked the other way. The average cost per bushel climbed to $4.79 from $4.55, and the board crush margin compressed to $0.30 per gallon from $0.41 a year ago. Pekin production also slipped to 53.7 million gallons from 55.5 million. Specialty alcohol volumes eased to 21.5 million gallons from 22.4 million. SG&A rose to $7.8 million from $6.5 million. Adjusted EBITDA of $21.0 million was essentially flat year over year only because it captures the tax credits. By the same measure, it was down from the $23.7 million reported in the second quarter.
There were genuine bright spots. Western production gross profit improved to $2.6 million from $1.5 million on higher volumes and pricing. The consolidated essential ingredients return edged up to 53.5% from 52.5%. The year-to-date picture is far stronger than the quarter alone suggests. Nine-month net income attributable to common stockholders was $28.0 million, compared with a $9.4 million loss a year earlier. Nine-month adjusted EBITDA was $49.3 million versus $16.7 million. The balance sheet is also improving. Alto paid down $6.5 million on its line of credit in the quarter, bringing year-to-date debt reduction to $26.5 million. It ended September with $23.6 million in cash and $108 million of borrowing availability.
The most important forward-looking change is the 45Z outlook. Management now expects a minimum of $20 million in 2026 credits, net of monetization costs, citing carbon-score reductions at Columbia and the Pekin dry mill. On the prior call, that figure was tracking at $15 million to $16 million. Alto also signed its first multi-year low-carbon-intensity corn supply agreement with a local farmer cooperative and said more agreements are in the works. The Pekin debottlenecking project should allow the company to exit the year with higher capacity and qualify more gallons. Management cited healthy ethanol demand and the improved outlook for year-round E15 adoption in California as industry tailwinds. Investors should recognize the risk in the mix, however. A growing share of profitability now depends on achieving carbon-intensity scores, monetizing credits at the expected cost, and maintaining the regulatory framework. Updated conference-call commentary was not available for this review. As a result, management's latest views on exports and specialty alcohol premiums cannot be assessed. Both were soft spots in the second quarter. The $50 million at-the-market equity program added last quarter also remains a dilution consideration.
The market setup is more complicated than the surprise implies. Investor sentiment swung sharply, from negative (-0.29) at the prior report to solidly positive (+0.49), a meaningful shift in expectations. Price action has told a different story. Entering the report, shares sat at $3.55, down 26.2% from the $4.81 open after the August release. That left the stock 17.1% below its 200-day moving average of $4.28 and just 4.6% above its October 16 inter-quarter low of $3.40. It also stood 27.6% below the $4.90 high set the day after the prior report. Price and AVWAP trend readings remain negative, although momentum has turned positive. In short, the stock has absorbed a steady markdown even as sentiment improved.
The bottom line is that Alto delivered a headline beat built substantially on tax credits, while its underlying crush economics weakened noticeably from a year ago. Bulls can point to the higher 45Z floor, continued deleveraging, and added capacity as levers that should matter more in 2027. Bears have legitimate ammunition in the halving of Pekin gross profit and the growing reliance on policy-driven earnings. With shares trading near their quarterly lows, the next leg depends on whether crush margins stabilize enough for core operations to carry more of the load.
Read our earnings preview for Alto Ingredients, Inc.: https://www.earningswhispers.com/article/ALTO/22012
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Oct-28 | |
| Oct-28 | |
| Sep-14 | |
| Aug-05 | |
| Aug-05 | |
| Jul-29 | |
| Jun-29 | |
| Jun-15 | |
| May-28 | |
| May-18 | |
| May-06 | |
| May-06 |
