Aeva Beats On Record Revenue And Optical Wins, But Not Reaffirming The FY26 Target Clouds The Story
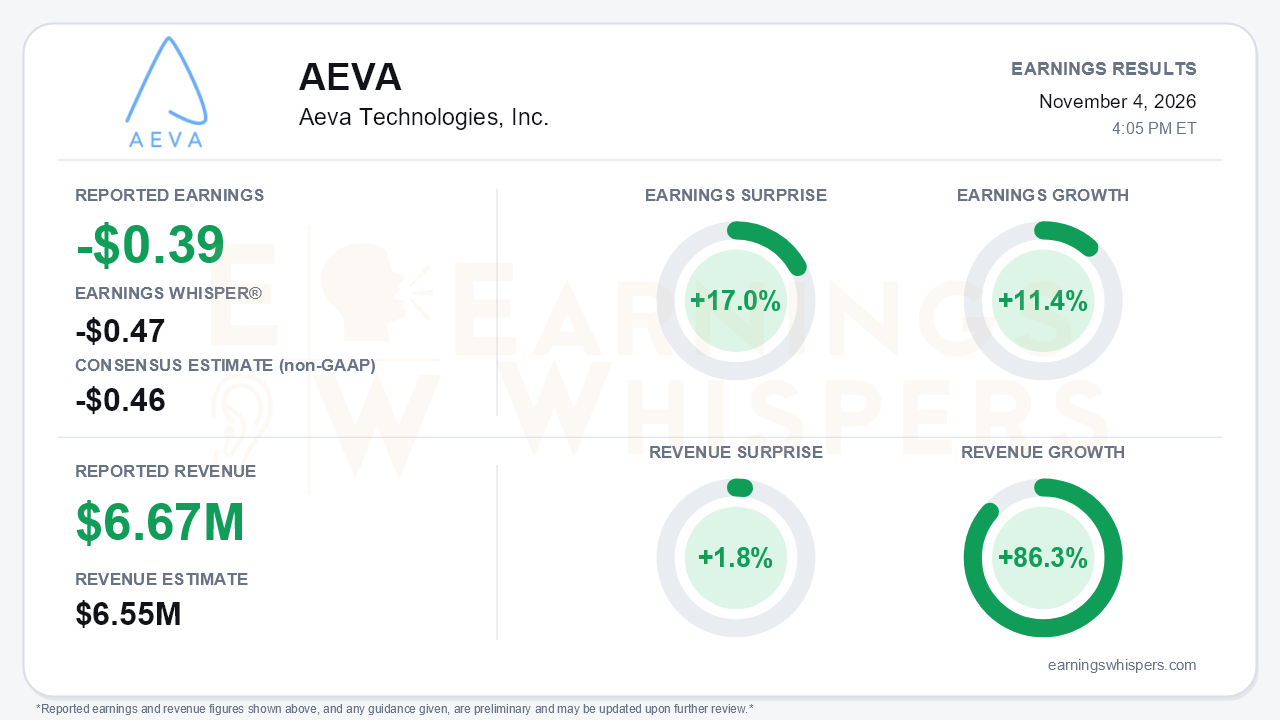
Aeva Technologies delivered a clean beat on paper for the third quarter. The non-GAAP loss of $0.39 per share topped the $0.46 consensus by 17.0% and came in ahead of the $0.47 Earnings Whisper number. Revenue of $6.67 million beat the $6.55 million consensus by 1.8% and rose 86.3% year over year to a company record. Earnings improved 11.4% from a year earlier. The central tension sits beneath those numbers. Aeva produced its most strategically important quarter yet in optical connectivity, but management declined to stand behind its full-year revenue target while losses kept drifting higher. The beat is real. It does not resolve the questions investors now care about most.
The quality of the earnings beat deserves scrutiny. The per-share improvement came largely from a bigger denominator, not a smaller loss. Non-GAAP net loss actually widened to $27.4 million from $26.7 million a year ago, while basic weighted shares rose to 69.6 million from 57.9 million, helped by the roughly $115 million equity raise earlier this year. On a GAAP basis, the $0.06 basic profit is an accounting artifact of a $43.3 million warrant fair-value gain; diluted GAAP loss was $0.54. Stock-based compensation nearly doubled to $11.4 million. There is genuine operating progress, however. Gross profit rose to $2.2 million from $0.4 million. Product revenue roughly doubled to $3.5 million, and product shipments grew more than 50% sequentially. Professional services still contributed $3.2 million, nearly half the total.
The revenue trajectory is improving, but slowly. Quarterly sales went from $5.6 million in Q4 FY25 to $6.3 million, $6.1 million, and now $6.7 million. Nine-month revenue of about $19.1 million is well ahead of last year's $12.5 million. That pace sits awkwardly against the $30-36 million FY26 target set last year. Hitting even the low end would require roughly $11 million in Q4, far above the current run rate. When asked directly, the interim CFO did not reaffirm the range. Bears have legitimate ammunition in that silence. Non-GAAP operating loss has also risen every quarter, from $23.8 million in Q4 FY25 to $27.7 million, as Aeva steps up optical investment and long-lead supply commitments.
The call's offsetting case rests on optical connectivity, and it was substantive. The business went from a single joint development agreement in Q2 to first revenue in Q3, with Ultra-High Power chipsets shipped to the JDA customer for validation. That partner is extending the platform to an additional hyperscaler. A second optical customer is now in commercial negotiations, which management sized at potentially multiple millions of units and multiple hundreds of millions of dollars annually from 2028. Aeva also broadened its portfolio with UHP, SPECTRA, and MESA products. Beyond optical, the company announced a US Air Force/Navy airborne autonomy program and a Micro-Epsilon supply deal with a multi-thousand-sensor initial order. On the automotive side, it completed the Bendix development program and passed a top-10 European OEM's VDA audit. The CEO's tone was notably expansive. Still, the economics depend on hyperscaler qualification targeted for mid-to-late 2027 and on securing incremental foundry capacity, so the payoff is at least a year out.
That timing gap matters for the balance sheet. Gross cash use ran about $30.6 million in the quarter, and total liquidity fell to $272.5 million from $302.9 million. Only $147.5 million of that is cash and securities; the rest is an undrawn $125 million facility, whose maturity was helpfully extended two years. Governance and focus questions add friction. The CFO seat is still filled on an interim basis, the CEO flagged organizational "adjustments" in the non-optical businesses, and the top-5 passenger OEM program went unmentioned.
The market had already turned hard against the stock before the report. Shares fell 65.3% from the $25.80 open following the August report to $8.94. They sit 46.8% below the 200-day moving average and just 4.9% above the 52-week low of $8.52 set two days before earnings. Investor sentiment swung from mildly positive (0.15) to clearly negative (-0.26), a meaningful deterioration. Earnings Whispers trend readings are mixed, with price and AVWAP trends negative even as sequential growth and momentum register positively. The market setup is more complicated than the surprise implies. Expectations were depressed, but the guidance ambiguity gives skeptics a fresh reason to stay cautious.
The bottom line is that Aeva delivered a headline beat and a genuinely stronger optical narrative, but the quarter traded near-term credibility for long-term optionality. Investors are being asked to look past widening losses, steady cash burn, and an unconfirmed revenue target toward hyperscaler programs that will not mature until 2027-2028.
Read our earnings preview for Aeva Technologies, Inc.: https://www.earningswhispers.com/article/AEVA/21770
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 5 hours | |
| Nov-03 | |
| Oct-27 | |
| Oct-20 | |
| Oct-14 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Jul-15 | |
| Jun-16 | |
| Jun-11 | |
| Jun-10 | |
| Jun-05 | |
| Jun-04 |
