Ascent Industries Swings To Profit As Margins Rebuild, But Slowing Commercial Wins Cloud The Outlook
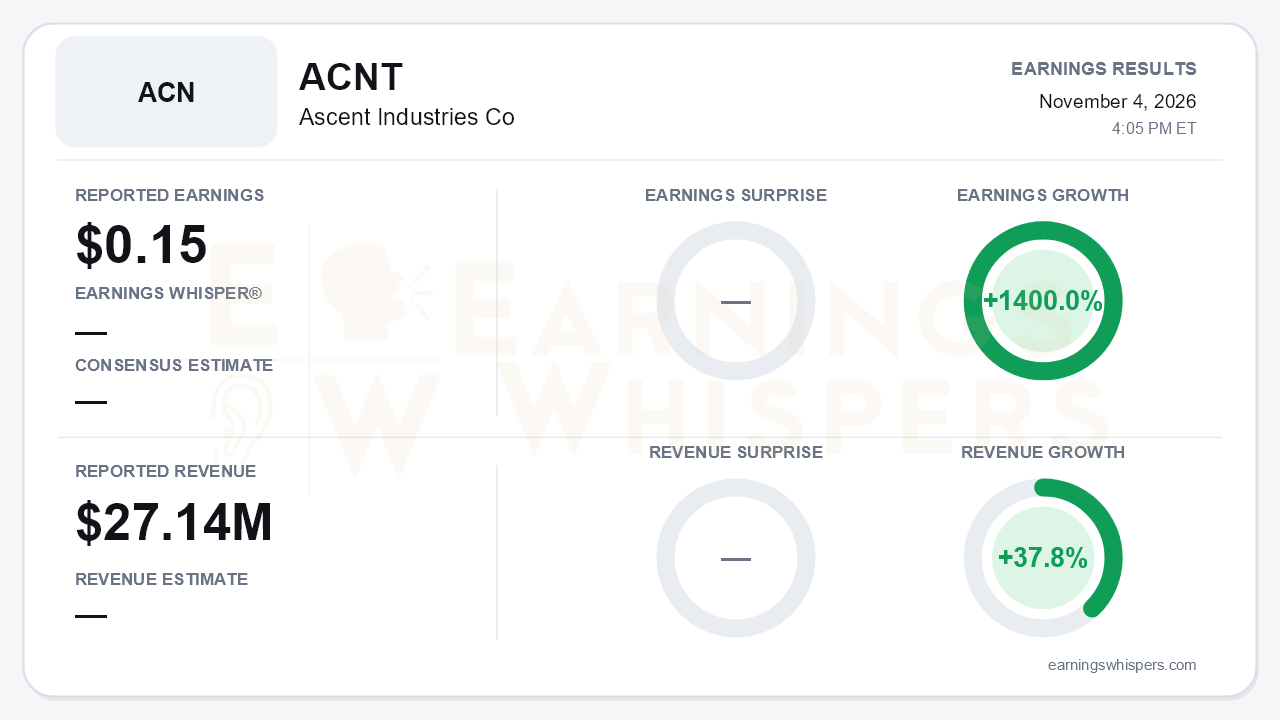
Ascent Industries (NASDAQ: ACNT) delivered its cleanest quarter since repositioning as a pure specialty chemicals platform. It earned $0.15 per share from continuing operations on revenue of $27.14 million, compared with a loss of $0.01 a year ago. Earnings grew 1400.0% year over year and revenue rose 37.8%. No consensus estimate or Earnings Whisper was available, so the quarter has to be judged on its own trajectory, and on that basis the improvement is real. The central tension is that the income statement finally caught up to the turnaround narrative just as the leading commercial indicators that should sustain it lost momentum.
The headline growth flatters slightly, but less than investors might assume. The Midwest acquisition, closed in May, added $2.3 million of sales, a $0.7 million net loss and negative $0.2 million of adjusted EBITDA. Organic growth was still a healthy 26.3%, driven by both volume and price. Excluding Midwest, EPS was $0.23 and adjusted EBITDA margin was 15.1%, so the deal diluted reported profitability. Management said Midwest was accretive before corporate allocations. Consolidated adjusted EBITDA rose to $3.5 million, a 13.0% margin, from $1.4 million (7.0%) a year earlier.
The quality question centers on gross margin. Gross margin of 26.2% remains 342 basis points below the 29.7% posted in the prior-year quarter, reflecting higher material, labor and freight costs. Much of the year-over-year EBITDA expansion came from SG&A, which fell to $5.3 million from $6.3 million. The Specialty Chemicals segment's adjusted EBITDA margin actually slipped to 14.9% from 16.0%. Management also acknowledged that pricing has contributed to performance and that it wants more of the future margin gains to come from execution and productivity. The sequential picture is far more encouraging:
- **Gross margin** climbed from 14.5% in Q1 to 21.6% in Q2 and 26.2% in Q3. That already exceeds the "low 20s" full-year expectation set earlier in the year.
- **SG&A** fell to 19.6% of sales from 26.4% in Q1, against a 15% long-term target.
- **Operations** posted concrete wins: Tennessee cycle time was cut from 4.5 days to 4 hours, and Virginia yields improved 14.7%.
- **Cost program:** management said the $3-5 million gross-profit improvement program remains on track.
The weakness is in the commercial funnel, and bears have legitimate ammunition there:
- **New wins** fell to $2.8 million annualized across 12 wins, down from $5.8 million in Q2 and $7.6 million in Q1.
- **Conversion** dropped to roughly 13% from 26% in Q2.
- **Sales cycles** stretched to about 7.5 months, from roughly 3.5 months in Q1.
- **Pipeline** eased to about $135 million from a record $140 million, though it remains roughly 60% higher year over year.
There are offsets. Average win size now exceeds $200,000, half of the quarter's wins came from new customers, and Midwest added more than $50 million of pipeline and two wins worth over $500,000 annualized. Still, a halving of the conversion rate in a muted demand environment is not a trend investors can dismiss. Management also flagged that extended payment terms are being used to win business. That shows up on the balance sheet, where receivables have doubled to $21.1 million since December.
Cash is the other moving part. Cash fell to $28.7 million from $57.6 million at year-end, reflecting:
- the $13.6 million Midwest purchase;
- $6.8 million of share buybacks, none of them in Q3;
- $5.5 million of year-to-date operating cash use from continuing operations.
The inflection is that operating cash flow turned positive in Q3, generating about $2.2 million after $7.7 million of first-half use. The full $4.55 million Bristol Metals escrow also arrived after quarter-end. With no revolver debt, $21.1 million of availability and a reaffirmed liquidity outlook in the low-to-mid $50 million range, the balance sheet still allows for disciplined M&A or renewed repurchases.
The forward setup is less clean than Q3 itself. Management issued no formal guidance and again warned of seasonal fourth-quarter margin and earnings compression tied to agriculture, jet fuel additives and destocking. The CEO did say Q4 revenue should exceed the prior-year period. Market data is limited this cycle: no current price or sentiment reading was available. For reference, shares opened at $16.01 after the August report, and the 200-day moving average sits at $14.65. Whether the stock holds above that zone will likely depend on how investors weigh the margin rebuild against the slowdown in wins.
The bottom line is that Ascent proved its cost and operating initiatives can produce genuine profitability. Sequential margin gains, lower overhead and positive operating cash flow mark a credible turning point. The next leg depends on growth, and the sharp drop in conversion, longer sales cycles and a slightly smaller pipeline suggest that leg is not yet secured, especially heading into a seasonally weak quarter.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Oct-26 | |
| Aug-19 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 | |
| Jul-27 | |
| May-06 | |
| May-06 | |
| May-06 | |
| Apr-27 | |
| Mar-04 | |
| Mar-03 |
