Sezzle Beats And Raises For A Fourth Time, But A Visa-Aided Margin And Slower Subscriber Adds Complicate A Clean Story
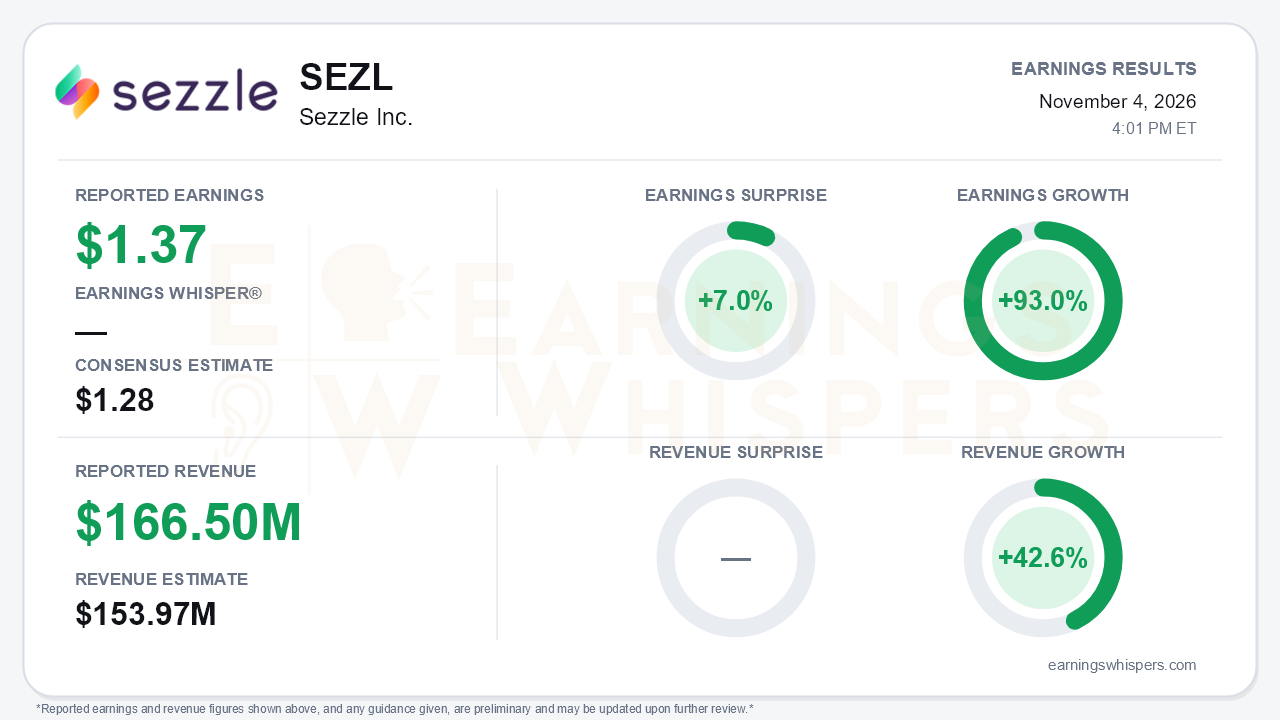
Sezzle delivered another quarter that pushed its earnings power higher. Adjusted earnings of $1.37 per share beat the $1.28 consensus by 7.0% and grew 93.0% year over year. Revenue of $166.5 million topped the $153.97 million estimate by 8.1% and rose 42.6%. GAAP results were nearly identical, with net income up 79.3% to $47.8 million, or $1.38 per diluted share. The more consequential news was forward-looking. Management raised FY2026 guidance for the fourth time this year, to roughly 42.5% revenue growth, $190 million of adjusted net income, and $5.45 to $5.50 of adjusted EPS. That compares with an original EPS target of $4.35. Sezzle also introduced a preliminary FY2027 adjusted EPS target of $7.20, or roughly 31% to 32% growth. The central takeaway is that the growth trajectory keeps steepening. The full-year revenue growth outlook has climbed from 25% to 30% at the start of the year to 42.5% now, and revenue per monetized user grew 28.1% versus 16.2% in the second quarter.
The quality of the beat deserves some scrutiny, even though it holds up. The leverage came largely from transaction economics. Total Transaction Volume rose 34.9% to $1.4 billion, yet transaction-related costs rose only 9.8%, falling to 4.2% of TTV from 5.2%. All three components improved: the credit loss provision fell to 2.7% of TTV from 3.1%, transaction expense dropped to 1.3% from 1.7%, and net interest expense fell to a company-low 0.2%. That drove operating margin up 8.2 points to 38.6%. Part of the transaction-expense improvement, however, came from a $3.7 million payment network incentive tied to a new exclusive Visa arrangement for U.S. credit products. Excluding that benefit, net transaction margin would have been roughly 62.5% rather than the reported 64.7%. That is still healthy, but it means the sequential gain from 63.5% in the second quarter was largely flattered. Taxes worked the other way, with the effective rate rising to 22.1% from 15.7%.
Beneath the headline, operating metrics were mostly strong, with one notable soft spot. Active subscribers reached 955,000, up 68.1% year over year and up from 854,000 in the second quarter. Quarterly transaction frequency hit a company-high 7.8x, compared with 7.2x last quarter. But net subscriber additions slowed to 101,000 from a record 140,000 in the second quarter after management deliberately cut marketing to $15.9 million from $19.4 million. That trade-off flattered margins. Whether subscriber growth can stay this strong on leaner spending is a fair question.
The new products are both the catalyst and the risk. SezzleCash completed its first full quarter, and more than 15% of eligible new Anywhere subscribers made it their first transaction, up from about 10% cited in the second quarter. The release says more than 60% of those users subsequently shopped at checkout, while the call characterized the 60%-plus figure as users taking multiple advances. Investors should note that the two descriptions of this cross-sell metric are not the same. Management also conceded that Sezzle Send "still needs fine-tuning." Both products carry lower margins and higher initial losses, and management declined to commit to sustaining high-end transaction margins. Revenue yield is expected to step down seasonally in the fourth quarter as provisions rise. Longer-dated catalysts include the national bank charter application filed in October, the Canadian Anywhere soft launch, and a WebBank arrangement that keeps SezzleCash and Sezzle Send loans off the balance sheet. Those items come with cost: antitrust litigation and charter expenses are expected to continue through 2027.
The market setup is more complicated than the surprise implies. Shares entered the report at $122.43, down 7.5% from the open following the August report. They sat 13.6% below an inter-earnings high of $141.72 set just one day earlier, on November 2, after recovering 16.7% from a September low of $104.87. The stock remains 12.3% above its 200-day moving average. Investor sentiment stayed negative but improved modestly, from -0.23 to -0.18. Skepticism is easing, but it has not been dispelled. The Earnings Whispers trend signals lean positive, with sequential growth, momentum, and AVWAP readings favorable while price is neutral.
That skepticism has a logic. Bears have legitimate ammunition in the Visa-aided margin, slower subscriber additions, a higher tax rate, and the margin dilution newer products could bring. Against that, the call preserved a credible growth story: fourth-quarter guidance raises, record frequency, rising monetization per user, $227.9 million of year-to-date operating cash flow, and roughly $239 million of liquidity.
The bottom line is that Sezzle again outran both consensus and its own guidance, and the $7.20 FY2027 target extends the earnings runway. The next test is whether margins and subscriber growth hold up as the Visa benefit normalizes, marketing stays restrained, and lower-margin products scale.
Read our earnings preview for Sezzle Inc.: https://www.earningswhispers.com/article/SEZL/21935
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Oct-27 | |
| Oct-23 | |
| Oct-22 | |
| Oct-19 | |
| Oct-08 | |
| Oct-07 | |
| Oct-06 | |
| Sep-29 | |
| Sep-01 | |
| Aug-13 | |
| Aug-07 | |
| Aug-07 |
