Paycom's Margin Surge Powers A 16.6% Beat And Second Straight Raise, But Revenue Growth Isn't Speeding Up
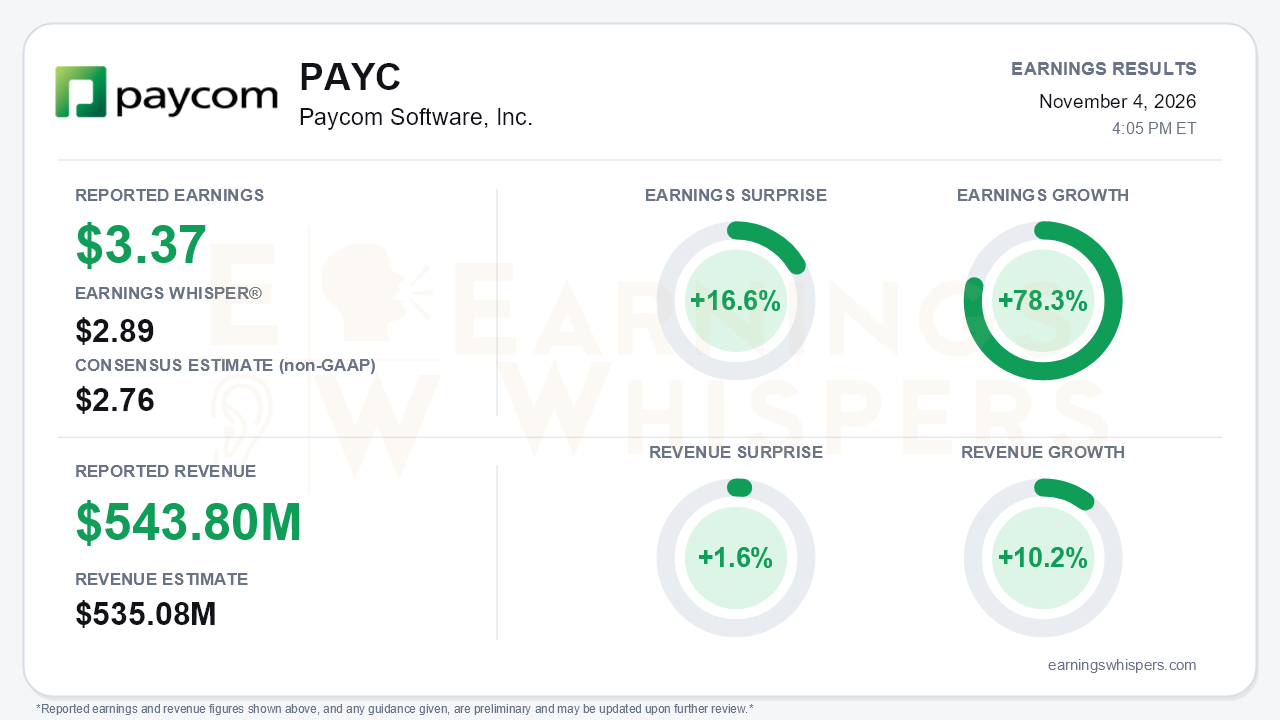
Paycom Software delivered the kind of profit upside that is hard to ignore. Third-quarter non-GAAP earnings of $3.37 per share beat the $2.76 consensus by 16.6% and cleared the $2.89 Earnings Whisper number. Earnings grew 78.3% year over year. Revenue rose 10.2% to $543.8 million, 1.6% ahead of consensus, and management raised full-year guidance for the second consecutive quarter. Revenue and profits did not move at the same speed, though. Earnings growth of nearly 80% sat on top of top-line growth that was steady rather than accelerating. That is the central tension. The quarter was driven by cost discipline and capital return far more than by a change in demand.
The quality of the beat deserves scrutiny, because the drivers are visible in the income statement. Adjusted EBITDA margin jumped to 49.3% from 39.4% a year ago and 44.2% in the second quarter. The biggest lever was research and development. Total R&D costs, including capitalized amounts, fell to $55.9 million from $117.6 million, or 10.3% of revenue versus 23.8%. Sales and marketing also declined in absolute dollars, to $108.0 million from $125.7 million. Share count did the rest. Diluted shares fell to 44.5 million from 56.4 million after roughly $1.39 billion of repurchases this year, partly funded by a revolver. GAAP EPS of $2.99 versus $1.96 tells the same story. It also absorbed $11.7 million of interest expense and lacked last year's $35.6 million naming-rights gain. Interest on client funds slipped to $24.5 million from $26.8 million. That leaves the margin gain resting on operating leverage, not float income.
The call preserved a credible, if measured, growth story. Recurring revenue grew 11%, matching the second quarter and improving on first-quarter growth of about 9%. However, it did not accelerate despite an extra-Wednesday calendar benefit, which management attributed to a tough comparison. Product signals were more encouraging:
- **Asset management:** the product launched in July already has more than 300 clients and is now billable.
- **iWANT:** usage is up roughly 65% versus the end of 2025, compared with 33% as of the first quarter.
- **Sales force:** management said new sales reps are outperforming any prior class.
- **International:** Paycom is hiring sales staff in Europe and won a large enterprise client in Mexico.
Management's tone shifted noticeably. Earlier in the year it was defending against AI-disruption narratives; now it says the company is "back to our old selves." Management also attributed the lower R&D spending to AI-driven efficiency, aided by Paycom's own data centers.
The forward picture contains both genuine catalysts and legitimate bear ammunition. Full-year guidance now calls for revenue of $2.213 billion to $2.218 billion, or about 8% growth, and adjusted EBITDA of $1.069 billion to $1.079 billion, a 48.5% margin. Management called the margins sustainable and expects 2027 free cash flow to exceed 2026's. Nine-month free cash flow of $536.5 million already nearly doubled last year's pace, helped by capex falling to $77.4 million from $197.4 million. Management also framed 2027 as "transformational" given products in testing.
Bears have several points to press:
- **Fourth-quarter slowdown:** the full-year guide implies fourth-quarter growth below the third quarter's, which analysts questioned.
- **Client funds:** average funds held grew just 7%, down from 9% in the second quarter and 11% in the fourth quarter of 2025, leaving the float exposed to rate cuts.
- **Balance sheet:** Paycom now carries $750 million of debt versus none at year-end, cash has fallen to $194 million, and stockholders' equity dropped to $707 million from $1.73 billion.
- **Buybacks:** repurchases slowed to $3 million in the third quarter from $346 million in the second and $1.06 billion in the first, removing a key EPS tailwind.
- **Spending ahead:** heavier sales and marketing investment and a new sales group for new products in 2027 may temper further leverage. The steep R&D decline also invites an underinvestment question.
The market setup is more complicated than the surprise implies. Shares closed at $262.99 ahead of the report, up 23.5% from the open after the August release. That leaves the stock about 59.5% above its 200-day moving average. It sits 4.4% below the $275.22 52-week high set on October 23, near the top of an inter-earnings range that bottomed at $204.36 in mid-August. Investors, however, have not grown more enthusiastic alongside the price. Earnings Whispers sentiment remained negative and weakened modestly, from -0.22 to -0.30. The Earnings Whispers trend signals are broadly positive, consistent with the stock's sustained advance. The divergence suggests a market that has rewarded the margin story while skepticism about its durability lingers.
The bottom line is that Paycom produced a high-quality profitability quarter and a believable raise. The headline beat, however, owes more to aggressive cost reduction and a sharply smaller share count than to accelerating demand. With buybacks largely paused, debt on the balance sheet, float growth cooling and a fourth-quarter slowdown embedded in guidance, the next leg depends on whether new products and international expansion can lift revenue growth. With shares already near their highs, the stock has to deliver on that 2027 "transformational" promise rather than on further margin expansion alone.
Read our earnings preview for Paycom Software, Inc.: https://www.earningswhispers.com/article/PAYC/21905
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Nov-02 | |
| Oct-30 | |
| Oct-27 | |
| Oct-27 | |
| Oct-21 | |
| Oct-15 |
Dow Jones Futures: Techs Slide On Anthropic Valuation Doubts; Tesla Roadster On Tap
PAYC +5.80%
Investor's Business Daily
|
| Oct-15 | |
| Oct-15 | |
| Oct-14 | |
| Oct-13 | |
| Oct-13 | |
| Oct-09 |
