Magnachip's Loss Deepens As Won-Driven Margin Miss Overshadows A Louder Transformation Pitch
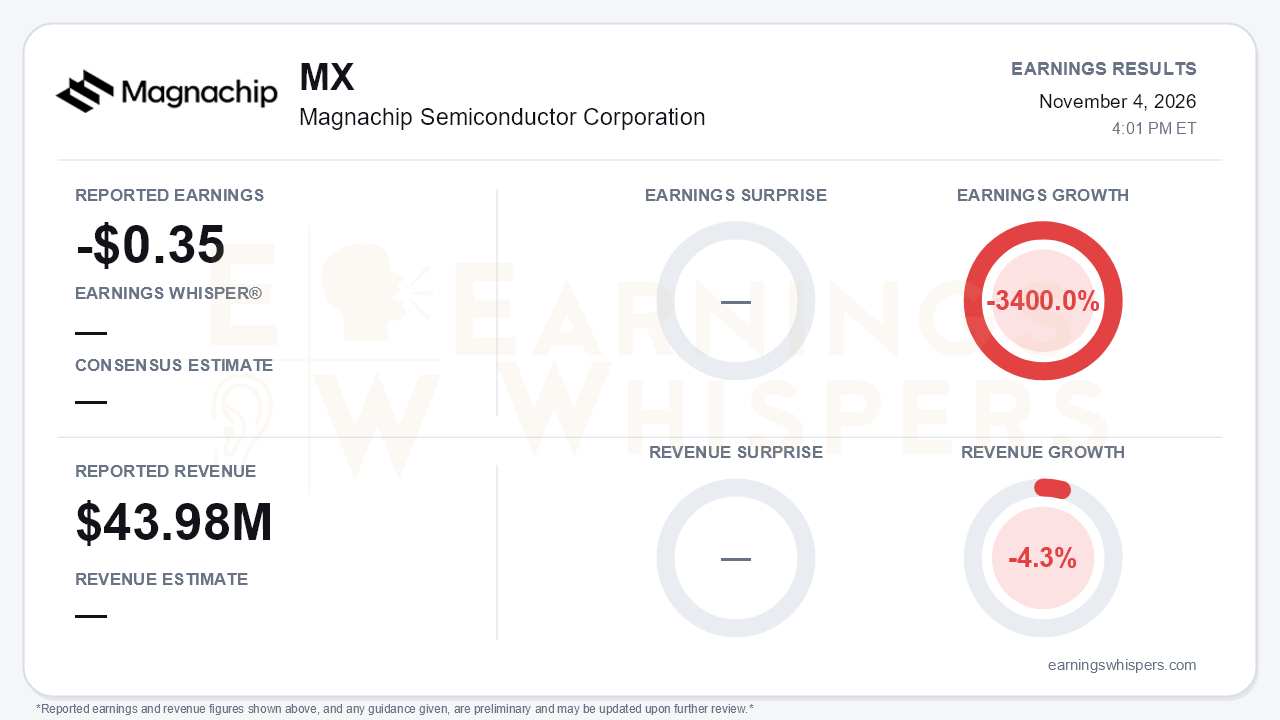
Magnachip Semiconductor (NYSE: MX) reported a loss of $0.35 per share on revenue of $43.98 million for the September quarter. Earnings fell 3400.0% year over year, and revenue declined 4.3%. No consensus estimate or Earnings Whisper was available, so the quarter cannot be scored as a beat or miss against the Street. Measured against the company's own targets, though, the verdict is clear.
- **Revenue** landed inside the $41.5 million to $45.5 million guidance range.
- **Gross margin** came in at 14.0%, well below the 17% to 19% range. That compares with 19.3% in the June quarter and 18.6% a year ago.
The central tension is that the strategic narrative under new CEO Chae Lee became noticeably more specific and confident, while nearly every near-term financial line moved the wrong way.
The headline per-share figure needs context. The release shows:
- a GAAP loss from continuing operations of $0.36;
- a total GAAP loss, including discontinued operations, of $0.34;
- an adjusted loss of $0.29, versus $0.13 in the prior quarter and $0.01 a year ago.
The pre-tax picture was actually less bad than the bottom line suggests. Pre-tax loss narrowed to $8.4 million from $9.6 million in Q2, helped by:
- a $1.8 million foreign-currency gain;
- $2.1 million of other income, largely from selling investment securities.
What swung the result was a $4.9 million tax expense. Management tied it to a reduction in deferred tax assets following a Korean tax audit. That charge is non-cash, but it is not the core problem.
The operating deterioration is real:
- Power Analog Solutions, roughly 90% of sales, saw gross margin collapse to 10.7% from 17.2% sequentially.
- Adjusted operating loss widened for a third straight quarter, from $6.5 million to $7.0 million to $8.6 million.
- The smaller Power IC business was a bright spot, with margin rising to 45.0%.
Management attributed the margin miss to the Korean won's sharpest quarterly gain against the dollar since late 1998. That is a credible explanation for a Korea-based manufacturer selling in dollars. Still, it does not explain the top line. Revenue has now slipped three quarters running, from $46.2 million to $44.7 million to $44.0 million. Management cited:
- weaker volumes in certain consumer applications;
- packaging constraints that limited its ability to meet demand in some product areas.
Fourth-quarter guidance extends the slide:
- **Revenue:** $41 million to $45 million, a midpoint down 2.2% sequentially but up 6.0% from a weak year-ago quarter.
- **Gross margin:** 10% to 12%, pressured by a fab power shutdown for the Gumi substation upgrade and continued won strength.
The substation impact had been flagged earlier in the year, but from a much higher margin base. Management now describes Q4 as the gross-margin trough. It also said it is weighing selective price increases following peers' hikes. Both are management expectations, not demonstrated results.
The call preserved a credible, if distant, growth story. Lee outlined two roadmaps:
- **Near term:** silicon MOSFET and IGBT modules with integrated sensing for AI server, industrial and higher-margin consumer uses, with sampling targeted within 12 months.
- **Longer term:** 800V protection products for data-center and industrial markets, a market management sizes at about $1 billion, with sampling expected in the second half of next year.
Other supporting points:
- The 2026 new-generation product launch count has been raised repeatedly, from 40+ to 55 to roughly 85 projected, with 57 launched year to date.
- Navitas followed its July partnership with a $5 million equity investment.
- The CEO bought shares in the open market.
But bears have legitimate ammunition. Lee conceded most new products remain undifferentiated. The previously repeated target of roughly 10% of Q4 revenue from new-generation products went unmentioned.
The balance sheet deserves scrutiny. Operating activities consumed $18.2 million in the quarter. Inventories have risen to $40.4 million from $34.2 million at year-end. Total borrowings stand at $47.1 million, with $30.0 million now classified as current.
The call framed cash as rising to $86.9 million from $83.9 million. The cash flow statement, however, shows Q3 beginning cash of $87.9 million and a modest $1.0 million decline. Either way, cash held near $87 million only because of an $8.3 million exchange-rate translation benefit and $4.9 million of stock issuance, including the Navitas stake. Adjusted EBITDA did improve modestly to -$3.5 million from -$4.2 million, a small offset.
Market context is limited. Current sentiment readings and recent price data were not available. For reference, the stock opened at $2.91 after the July report, below the current 200-day moving average of $3.65. That suggests investors were already treating the transformation story with skepticism heading into this quarter.
The bottom line is that Magnachip delivered in-line revenue but a materially wider loss. The quarter was driven by a currency-hit margin miss and a tax-related write-down, and Q4 guidance points to an even lower margin trough. The strategic roadmap is sharper and backed by Navitas and insider buying. However, its meaningful revenue contribution is at least a year away, while cash burn, rising short-term debt and a shrinking top line define the present. Until margins recover from the guided trough and new products show differentiated revenue, the turnaround remains a story rather than a result.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Oct-14 | |
| Oct-05 | |
| Sep-21 | |
| Sep-21 | |
| Jul-29 | |
| Jul-29 | |
| Jul-08 | |
| Jun-29 | |
| Jun-22 | |
| May-29 | |
| Apr-29 | |
| Apr-28 |
