Maravai Beats And Raises Again, But Sequential Fade And A Flat Implied Q4 Temper The Upgrade
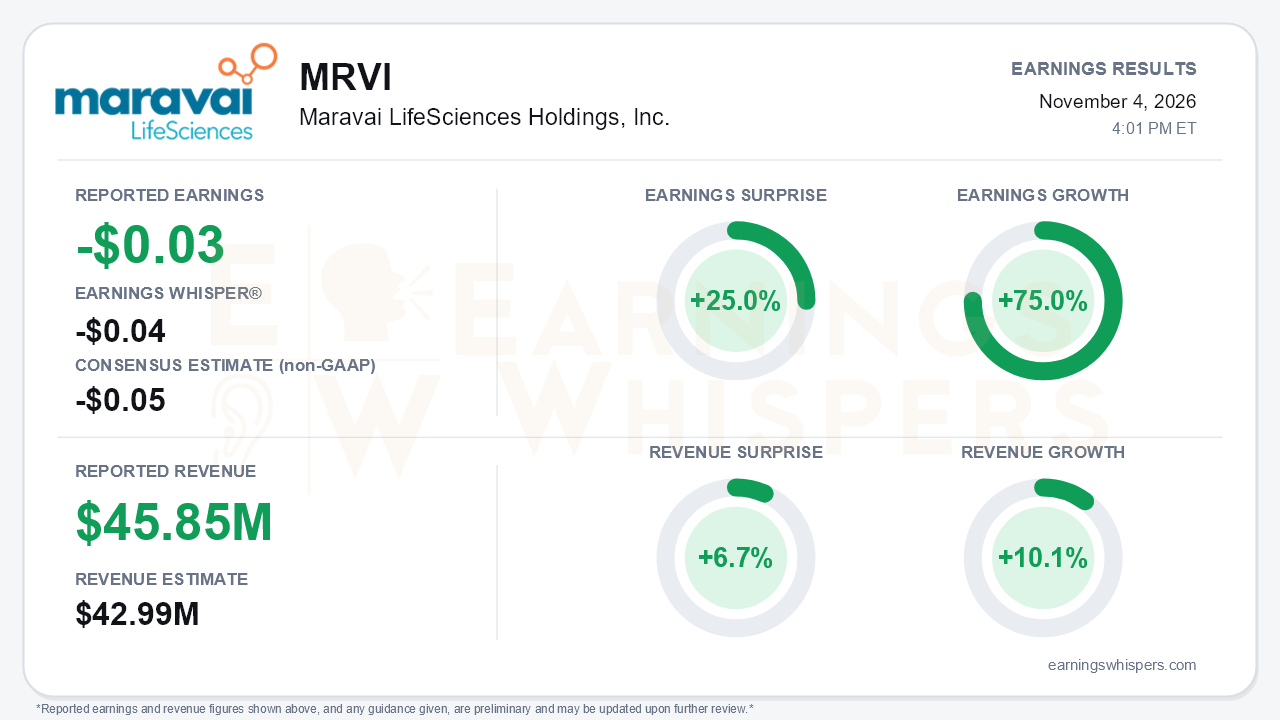
Maravai LifeSciences delivered another clean beat-and-raise in the third quarter, posting an adjusted loss of $0.03 per share against a $0.05 consensus estimate and a $0.04 Earnings Whisper number, a 25.0% surprise. Revenue of $45.85 million rose 10.1% year over year and topped the $42.99 million consensus by 6.7%. Earnings improved 75.0% from the prior-year adjusted loss of $0.08. Management raised full-year guidance for the fourth time in 2026, lifting revenue to $212 million to $216 million and adjusted EBITDA to $40 million to $42 million. The year-over-year story is unambiguously better. The central tension is that the quarter-over-quarter trajectory is softening, and the new guidance implies a nearly flat fourth quarter.
The year-over-year improvement is real and visible below the non-GAAP line. GAAP net loss narrowed to $24.0 million from $45.1 million, and GAAP loss per Class A share halved to $0.09 from $0.18. Gross profit nearly tripled to $16.2 million as cost of revenue fell despite higher sales. SG&A dropped about $5 million, a sign that the 2025 realignment is still paying off. Adjusted EBITDA swung to a $5.8 million profit from a $10.8 million loss. Still, this remains a GAAP loss-making company carrying stock compensation of roughly $10 million a quarter. Restructuring charges also continue to recur, and those items are excluded from the adjusted figures.
The sequential picture is where bears have legitimate ammunition. Adjusted EBITDA has stepped down from $20.3 million in Q1 to $8.7 million in Q2 and $5.8 million in Q3. Q1 was inflated by $14.3 million of COVID CleanCap orders. TriLink segment EBITDA fell to $2.5 million from $7.0 million in Q2. Adjusted gross margin eased to 57.7% from 58.9% in Q2 and 65.3% in Q1, even though it remains about 1,700 basis points above last year. Within TriLink, GMP consumables growth slowed to 30% from 55%, and specialty chemistry declined 4% on non-repeating large orders. The 20.1% nine-month revenue growth figure flatters the base business. Excluding COVID CleanCap, TriLink grew 12.9%.
The call nonetheless preserved a credible growth story at the front end of the funnel. Discovery mRNA growth accelerated to 27% from 17% in Q2, and Maravai added a record 70-plus new discovery customers. RUO-to-GMP conversions reached 10 year to date, already beating the full-year target of nine. Four of those conversions came this quarter. ModTail users climbed to more than 180 from 125 in Q2. Cygnus posted its sixth straight growth quarter, with growth accelerating to 8% from 3% in Q2 and roughly 1% in Q1, at 71% EBITDA margins. New initiatives include:
- an R&D library of novel cap analogs opened to customers;
- an in-country China sales presence, backed by a second China patent;
- the SV40 MockV kit for AAV viral clearance;
- the AI-assisted mRNA Builder.
Management sounded confident and said there is "little or no risk" to guidance. Cash rose to $73 million, with debt at roughly $147 million after the Q2 refinancing.
The forward caveats matter, though. Full-year revenue guidance implies only about 2% fourth-quarter growth, versus roughly 10% year to date. The EBITDA range implies a Q4 roughly in line with Q3's run rate, not a rebound. Management warned that 2027 GMP revenue will be back-half weighted and that GMP ModTail will not be material next year. Some customer mRNA cancer vaccine programs disappointed, and part of Cygnus' 48% China growth was timing catch-up from a soft Q1. The raise itself was modest at the top line: the midpoint moved up $4 million, with the low end raised $7 million and the high end just $1 million.
The market setup is more complicated than the surprise implies. Shares are up 33.0% from the $5.60 open after the August report and sit about 41.5% above the 200-day moving average near $5.26. However, they have given back much of the post-report spike to a 52-week high of $9.42 on August 26 and trade roughly 21% below that peak. Investor sentiment slid from essentially neutral to modestly negative, around -0.20, ahead of the report. That is a meaningful cooling, though not a capitulation. The Earnings Whispers trend readings are mixed: momentum and AVWAP remain positive while sequential growth is negative, which mirrors the fundamental split.
The bottom line is that Maravai's turnaround is progressing on a year-over-year basis, with margin repair, a growing discovery pipeline and repeated guidance raises. The quarter-to-quarter cadence, however, is decelerating as COVID CleanCap rolls off and GMP orders remain lumpy. Investors who already re-rated the stock this summer will likely need evidence of a re-acceleration in 2027, particularly in GMP, more than another incremental raise.
Read our earnings preview for Maravai LifeSciences Holdings, Inc.: https://www.earningswhispers.com/article/MRVI/21878
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Oct-29 | |
| Oct-27 | |
| Oct-14 | |
| Sep-29 | |
| Aug-06 | |
| Jul-22 | |
| Jul-20 | |
| Jun-16 | |
| Jun-03 | |
| May-18 | |
| May-07 | |
| Apr-20 | |
| Feb-26 |
