Joby's Blade-Driven Beat And Third Guidance Raise Collide With Widening Burn And Slipping Certification Milestones
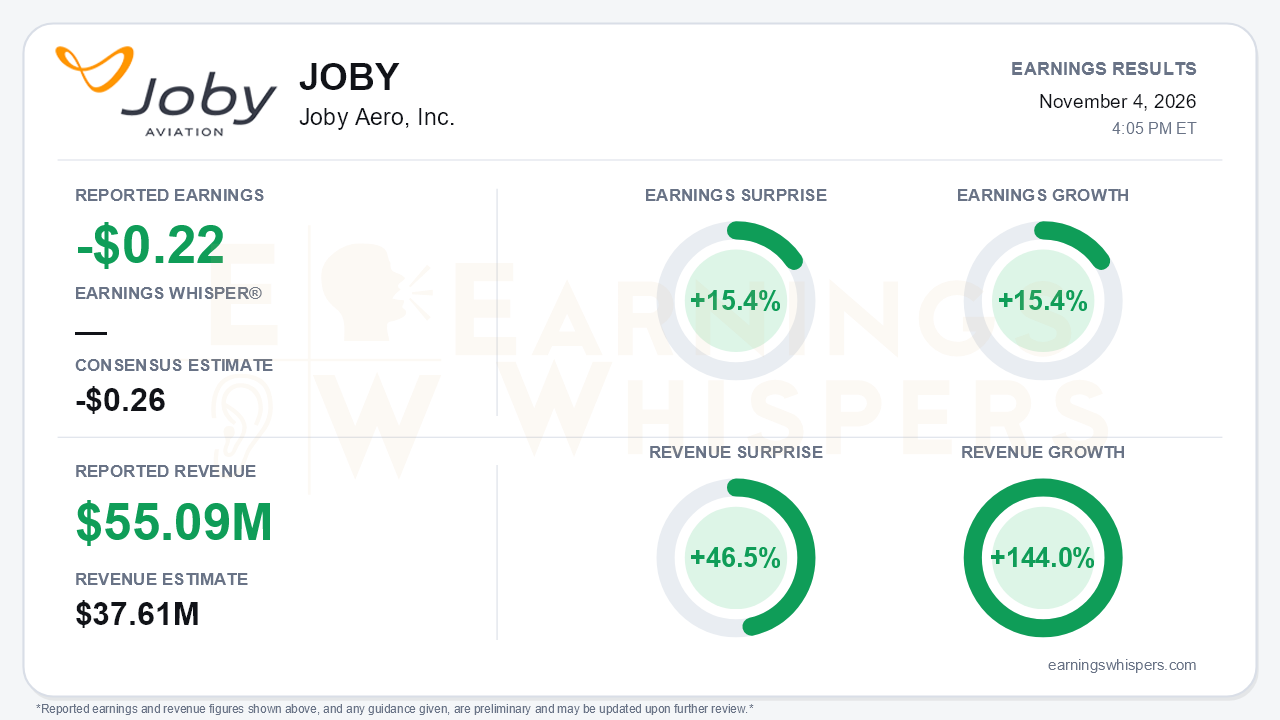
Joby Aviation delivered the cleanest headline quarter in its short history as a revenue-generating company. Revenue of $55.09 million beat the $37.61 million consensus by 46.5% and grew 144.0% year over year. The loss of $0.22 per share was narrower than the -$0.26 consensus, a 15.4% surprise, and improved 15.4% from the prior-year period. Management also raised full-year 2026 revenue guidance for the third straight time, to $135 million to $140 million. That compares with $115 million to $125 million last quarter and $105 million to $115 million earlier in the year.
The central tension is that the numbers beating expectations are not the numbers that determine Joby's value. The revenue line is almost entirely Blade, the passenger helicopter and urban air mobility business. Blade carried a record 44,000-plus passengers, and New York airport passengers rose 61% year over year. Sequential revenue progression of $24 million, $39 million and $55 million across the first three quarters is real, and management noted that all of it is organic, with Uber integration still ahead. But none of it comes from certified eVTOL service, and the cost base is moving the other way. Operating expenses climbed from $258 million to $300 million to $333 million over the three quarters. Adjusted EBITDA losses widened from $179 million to $197 million to $208 million. The narrower per-share loss should be read alongside continued at-the-market equity issuance, which expands the share base, rather than as evidence that losses are shrinking in absolute terms.
The operational story on the call was genuinely constructive in places. Manufacturing output rose 37% from the first quarter to the third while non-conformances fell 38%. The 18th Marina production aircraft has now been started, versus 12 in production last quarter. eIPP demonstration flights were completed in Dallas-area and Tampa/Orlando locations. Management also said the FAA clarified that eIPP flights can be commercial and may count toward function-and-reliability credit, which could make the pilot program more than a showcase. Cash use eased slightly to $195 million from $202 million, capex fell to $25 million, and second-half cash-use guidance of $385 million to $415 million was reaffirmed.
The timeline, however, keeps drifting. Earlier in the year, management said FAA pilots would fly later in 2026 and that first passengers would fly in Dubai this year. Now FAA pilot training and company flight testing under type inspection authorization are targeted for the first half of 2027. 2026 passenger activity in Dubai and under eIPP is framed as operational testing with a pilot aboard. The second $250 million Toyota tranche also slid from year-end or early next year to the first half of 2027. Each slip is modest on its own, but the pattern matters for a pre-revenue aircraft program.
The Resonant Sciences acquisition is the quarter's most consequential strategic shift. It adds an EBITDA-positive defense business with more than $100 million in trailing revenue growing roughly 40%. Alongside it, Air Force autonomy contracts expanded to about $37 million from roughly $20 million, and the J208 completed a coast-to-coast autonomous flight. Bulls get a second growth pillar and a nearer-term revenue stream. Bears get scope creep, integration risk and a roughly $450 million cash payment, expected at an early-2027 close. Cash has already fallen from about $2.5 billion to $2.2 billion despite $128 million of ATM proceeds, and some analysts estimate pro forma liquidity near $1.5 billion. With $620 million of ATM capacity remaining and no explicit runway disclosed, dilution remains a live concern.
The market has been treating these concerns seriously. Shares entered the report at $4.85, down 40.5% from the open after the August report and about 43% below the 200-day moving average of $8.56. The stock sits just 9.5% above the 52-week low of $4.43 set on October 15, after peaking at $9.08 in early August. Investor sentiment deteriorated from -0.10 to -0.24, a meaningful move deeper into negative territory heading into the print. Earnings Whispers trend signals are mostly negative on price and AVWAP, though momentum has turned positive.
The bottom line is that Joby beat decisively on revenue, raised guidance again and opened a credible defense avenue. However, the beat came from Blade, losses and spending are still widening, and the milestones that matter most for the air taxi thesis have shifted into 2027. With sentiment soured and the stock pinned near its lows, the report gives bulls tangible progress to point to. It also gives skeptics fresh ammunition on burn, dilution and execution timing.
Read our earnings preview for Joby Aero, Inc.: https://www.earningswhispers.com/article/JOBY/21856
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Oct-30 | |
| Oct-30 | |
| Oct-28 | |
| Oct-27 | |
| Oct-27 | |
| Oct-16 | |
| Oct-15 | |
| Oct-13 |
