EHealth Misses Badly As Medicare Revenue Collapses 64%; Brighter Carrier Backdrop Collides With An Approaching Preferred-Equity Deadline
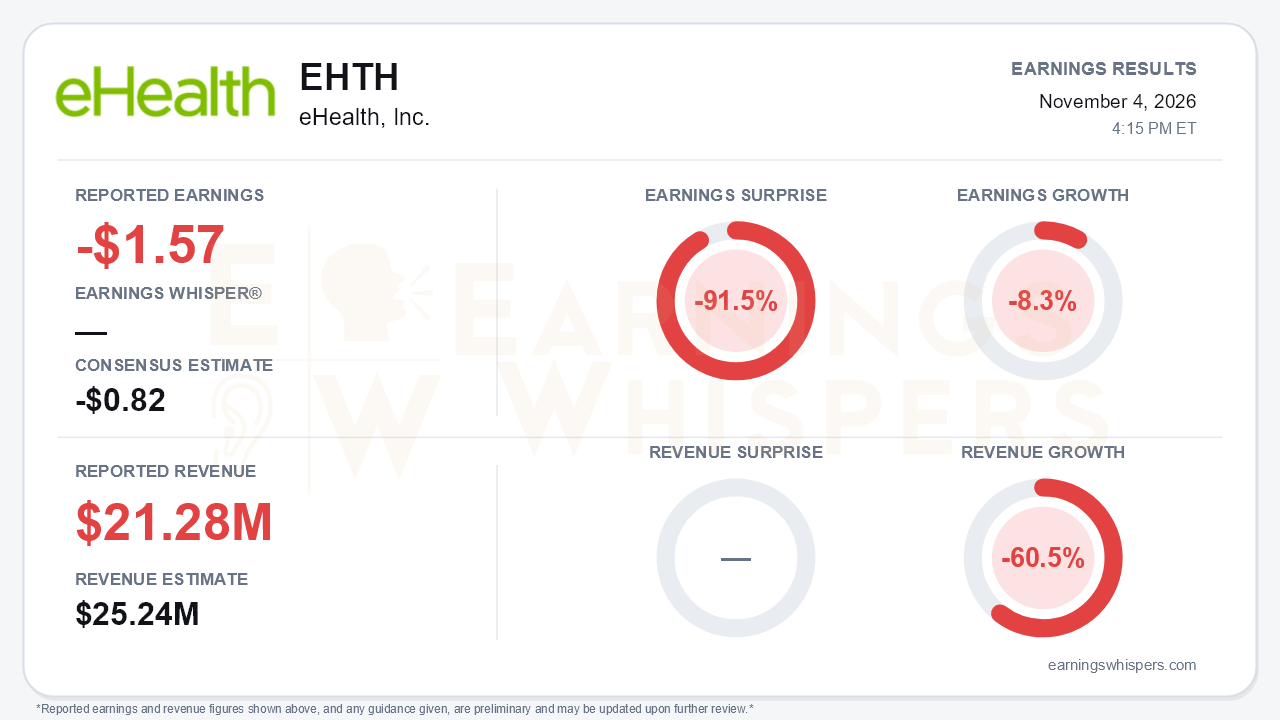
eHealth (NASDAQ: EHTH) posted a third-quarter loss of $1.57 per share. That was far worse than the $0.82 loss analysts expected, a 91.5% miss, and the loss widened 8.3% from a year ago. Revenue fell 60.5% to $21.28 million, 15.7% below the $25.24 million consensus. Management reaffirmed full-year guidance, which keeps the annual plan intact even though the quarter came in well short of the Street's numbers. That is the central tension. The industry and carrier backdrop improved this quarter, and management sounded more confident. Yet eHealth's own unit economics weakened, its cash kept falling, and the clock is now running on its capital structure.
The quality of the quarter deserves scrutiny because the deterioration is accelerating. Medicare segment revenue fell 64% to $18.1 million, a steeper decline than the 45% drop in the second quarter and 22% in the first. Medicare applications fell 55%, and Medicare Advantage applications fell 58%.
Tail revenue added to the damage. These are the net adjustments to previously booked commissions, and they fell to $1.5 million from $12.1 million a year earlier. That swing pushed the Medicare segment to a $12.7 million gross loss, compared with a $1.2 million loss last year. Adjusted EBITDA was a $39.9 million loss. The Employer & Individual segment's gross profit fell to essentially zero, $0.1 million versus $1.0 million.
Cost efficiency sent mixed signals. Revenue relative to variable marketing spend improved to 3.9x from 2.9x, so marketing dollars worked harder. But revenue relative to total variable acquisition cost fell to 0.6x from 1.0x, because call-center and enrollment costs did not shrink alongside the 55% drop in applications. The company is buying leads more cheaply but cannot yet scale its fixed service infrastructure to much lower volume.
The call preserved a credible story about the industry turning, and the tone shifted noticeably from August. In the second quarter, management said non-commission revenue showed no material change. Now it says:
- Sponsorship revenue is gradually returning this Annual Enrollment Period (AEP).
- eHealth signed a business-process outsourcing agreement with a top-three Medicare carrier to support that carrier's branded AEP enrollments. It will contribute revenue starting in the fourth quarter.
- Carriers are setting growth mandates by plan type and geography, and their medical loss ratios are improving. Management framed this as a setup for disciplined growth in 2027.
Several operating metrics also improved:
- **Cross-selling:** The ancillary cross-sell rate exceeded 40%, nearly double the year-ago level.
- **Retention:** Policies enrolled by advisors showed lower 90-day churn.
- **Cash flow:** Nine-month operating cash flow rose to $19.6 million from $10.6 million.
- **Costs:** Total operating expenses fell 29% and fixed costs fell 17%, with the $90 million cost-reduction program on track.
- **Tail revenue outlook:** The 2026 guide narrowed upward to $17–20 million, from $16–20 million in the second quarter and $8–20 million in the first.
The early read on AEP pointed to strong consumer demand and favorable cost per call and visit. Management also highlighted a BerniePortal partnership covering 5,000+ employers and 1,000 brokers for individual-coverage HRA products, and a new AI content tool.
Bears have legitimate ammunition, however, and some of it goes beyond the cyclical. Medicare Advantage lifetime value per policy has slid from +3% in the first quarter to -1% in the second and -2% in the third. Cash fell to $88.1 million from $101 million last quarter and $110.8 million in the first quarter. Commissions receivable dropped to $970.6 million from roughly $1 billion earlier in the year.
Most importantly, the earliest redemption date for the preferred equity held by HIG arrives at the end of April 2027. eHealth has engaged external financial advisors and renewed active talks with HIG on the capital structure. That is a notably more urgent framing than the 'nothing new to report' stance of the prior call, and the outcome is uncertain. Full-year guidance also depends on execution during the key AEP weeks that are still ahead.
The market had already priced in considerable distress before the report. Shares stood at $0.58 going into the release, down 58.8% from the $1.41 open after the August report and about 61% below the $1.48 200-day moving average. The stock set a 52-week low of $0.45 on November 2 and entered earnings only modestly above that level, near the bottom of its inter-earnings range and far below the $1.43 high reached in early August. Investor sentiment, already firmly negative, slipped modestly from -0.53 to -0.58. Earnings Whispers trend signals remain mostly negative, with price, sequential growth and AVWAP readings all pointing lower.
The bottom line is that eHealth delivered a deep miss and an accelerating revenue collapse. It paired them with the most constructive industry commentary it has offered in some time: a new top-three carrier contract, returning sponsorships, better cash generation and a firmer tail-revenue outlook. Those positives are real, but most of them pay off in the fourth quarter and 2027. Meanwhile, cash, MA lifetime values and in-period profitability continue to erode. The investment case now hinges less on this quarter's numbers than on two near-term tests: AEP execution and the outcome of the HIG preferred-equity negotiations before April.
Read our earnings preview for eHealth, Inc.: https://www.earningswhispers.com/article/EHTH/21830
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Oct-28 | |
| Oct-27 | |
| Oct-21 | |
| Oct-13 | |
| Oct-08 | |
| Oct-02 | |
| Sep-24 | |
| Sep-16 | |
| Sep-01 | |
| Aug-20 | |
| Aug-05 | |
| Aug-04 |
