Xperi Misses On Earnings As Ad Revenue Surges 280%, But A Cut To Its Media-Platform Target Undercuts The Raised Margin Outlook
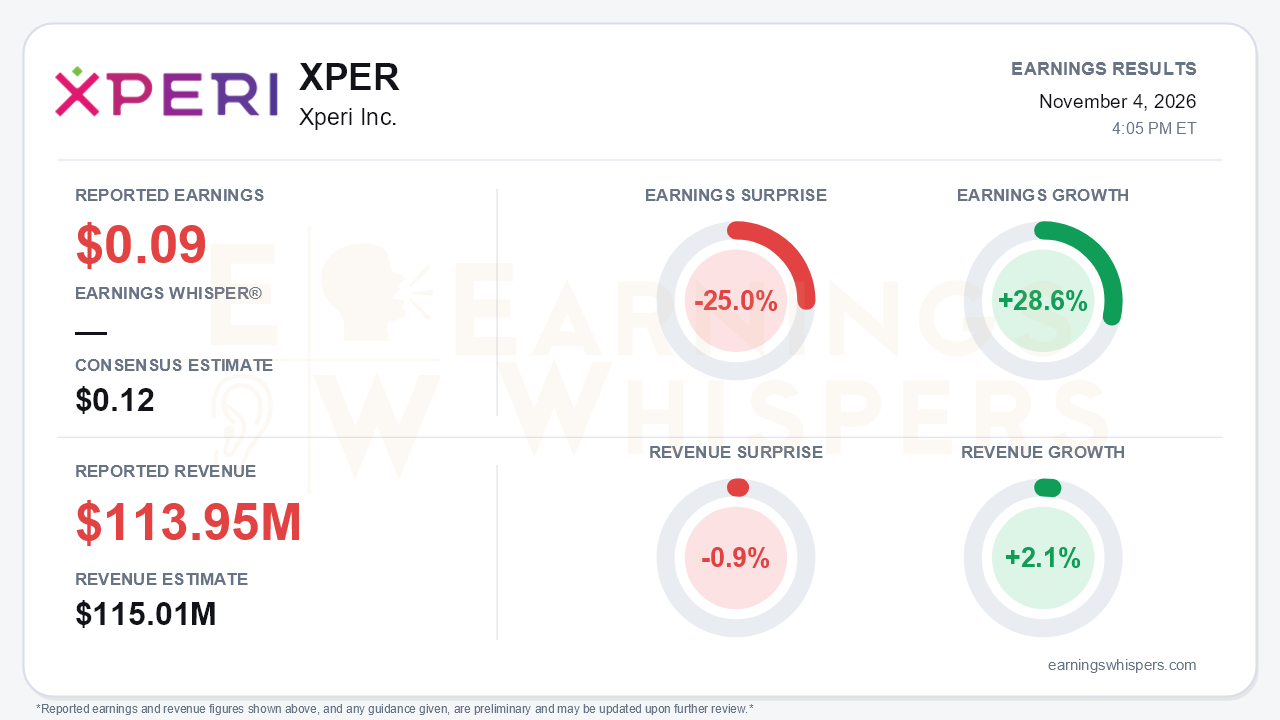
Xperi delivered a quarter whose headline beat and miss tell only half the story. Earnings Whispers' normalized EPS came in at $0.09, missing the $0.12 consensus by 25.0%, even as earnings grew 28.6% from a year ago. Revenue of $113.95 million rose 2.1% but fell 0.9% short of the $115.01 million consensus. That normalized figure differs from the company's own presentation. Xperi's non-GAAP EPS declined to $0.24 from $0.28. Its GAAP net loss narrowed to $0.11 per share from $0.13. Management raised its full-year adjusted EBITDA margin and operating cash flow outlook and highlighted a near-quadrupling of advertising revenue. Yet it also cut the media-platform growth and ARPU targets that underpin its monetization narrative. That is the central tension: profitability guidance went up while the growth thesis was quietly downsized.
The quality of the quarter deserves scrutiny. Advertising and related revenue jumped to $14.9 million from $3.9 million, roughly 280% growth, accelerating sharply from 54% in the second quarter. The segment reached a 31% gross margin, which pushed year-to-date advertising gross margin positive at 5%. But licensing and other revenue fell to $99.0 million from $107.7 million. Connected car revenue dropped 14% and consumer electronics fell 28% against tough minimum-guarantee comparisons. Total revenue barely grew because the legacy base shrank nearly as fast as the new business expanded. Below the line, much of the profit improvement came from cost cuts rather than revenue leverage. Research and development fell to $23.5 million from $29.9 million, and non-GAAP operating expenses declined 7%. Even so, adjusted EBITDA margin slipped to 20.2% from 20.7% as the mix shift toward lower-margin advertising lifted cost of revenue. A $7.4 million tax provision on just $2.1 million of pretax income kept GAAP results in the red.
The operating metrics were genuinely encouraging. TiVo One monthly active users reached 6.8 million, up 40% year over year and up from just over 6 million in the second quarter. Management raised its year-end target to more than 7.5 million from more than 7 million. ARPU rose 14% sequentially to $7.65. The DTS AutoStage footprint passed 18 million vehicles, and the broadcaster portal expanded to 550 U.S. metros with eight new data-licensing agreements. IPTV households climbed to 3.42 million. However, management now expects full-year media-platform growth of about 60%, down from the doubling to more than $80 million it had targeted since the fourth quarter. It attributed the shortfall to slower-than-planned ad growth and middleware declines. The year-end ARPU target was also cut to $8-10 from more than $10. Users are arriving faster than expected, but monetization per user is lagging the plan.
The catalyst list is substantive. MediaMarktSaturn, Europe's largest consumer electronics retailer, selected TiVo OS for its private-label PEAQ TVs, Xperi's 11th OEM design partnership and a retail-media opportunity. Management credited memory-footprint engineering with winning OEM share. The board is evaluating its existing buyback authorization, citing undervaluation. AI-driven cost initiatives will be detailed alongside 2027 guidance in February. Bears still have legitimate ammunition. Third-quarter operating cash flow fell to $4.1 million, and free cash flow was negative $3.4 million. Cash declined to $87 million, and unbilled receivables continue to swell. The full-year free cash flow framing of roughly -$5 million to +$5 million is softer than February's positive-at-midpoint view, despite the higher operating cash flow range. CFO Robert Andersen's planned 2027 retirement adds a transition in a hyper-competitive smart-TV OS market that is consolidating around Roku and Vizio.
Investors were already braced for disappointment. Earnings Whispers sentiment fell sharply ahead of the report, from -0.26 to -0.76, a genuinely meaningful deterioration into deeply negative territory. Shares closed at $5.39 on November 3, down 28.5% from the $7.54 open following the August report. That leaves the stock 16.3% below its $6.44 200-day moving average. The stock hit a 52-week low of $4.91 in mid-October and entered the report less than 10% above that level, near the bottom of its inter-earnings range. Price and AVWAP trend readings remain negative, although momentum has turned positive off the low.
The bottom line is that Xperi's quarter showed real traction in advertising, users, and OEM wins, along with credible margin discipline. However, the downgraded media-platform and ARPU targets weaken the monetization case that is supposed to offset a shrinking licensing base. With sentiment already washed out and shares near their lows, the raised profitability outlook and buyback talk may limit further damage. A durable re-rating likely requires evidence that ARPU can catch up to user growth and that cash conversion improves in 2027.
Read our earnings preview for Xperi Inc.: https://www.earningswhispers.com/article/XPER/21974
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Oct-27 | |
| Oct-20 | |
| Oct-14 | |
| Oct-05 | |
| Sep-22 | |
| Sep-17 | |
| Sep-11 | |
| Sep-03 | |
| Aug-06 | |
| Aug-05 | |
| Jul-22 | |
| Jul-20 |
