Veeco Misses As Margins Slip Again, But A 40% Growth Outlook For 2027 Makes Execution The Whole Story
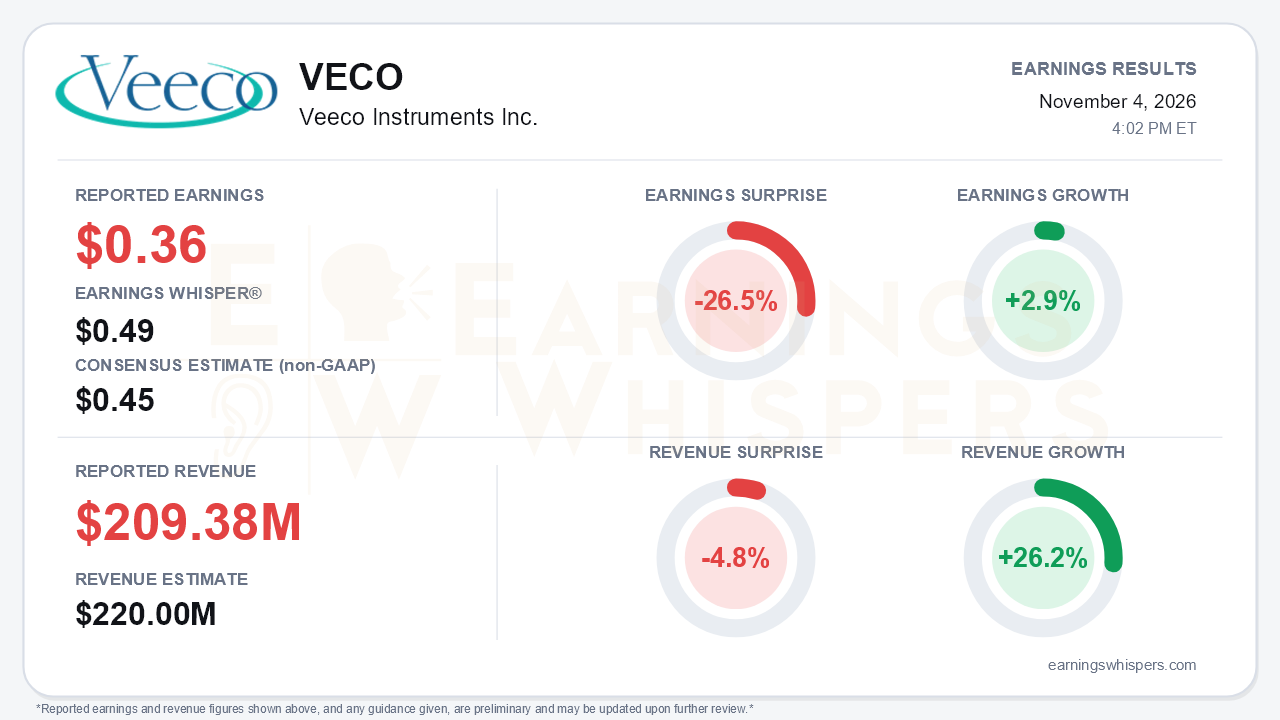
Veeco Instruments (NASDAQ: VECO) missed expectations in the third quarter, earning $0.36 per share on a non-GAAP basis. That was well short of the $0.45 consensus and the $0.49 Earnings Whisper number, a 26.5% shortfall. Revenue of $209.38 million also fell 4.8% short of the $220.0 million consensus. Yet revenue still grew 26.2% year over year while earnings grew only 2.9%, and that gap is the central tension in the quarter. Demand is clearly accelerating. Through the first nine months, revenue was $561.2 million versus $499.3 million a year earlier, so the third quarter ran well ahead of the year-to-date pace. The problem is that profitability is not keeping up. Management offered its most ambitious long-range framing yet just as near-term execution slipped for another quarter.
The quality of the miss deserves scrutiny because it was concentrated in margins rather than demand. Non-GAAP gross margin fell to 39.1% from 41.9% a year ago, and GAAP gross margin was 38.4%. Both missed management's own 41% to 42% guide. Management blamed supply-chain costs, mix and a laser spike annealing (LSA) system held in U.S. export review. Non-GAAP operating expenses climbed to $56.6 million from $46.3 million, with research and development spending up sharply. As a result, non-GAAP operating income rose only to $25.2 million from $23.1 million on roughly $43 million of added revenue. Dilution compounded the squeeze. The diluted share count rose to 66.2 million from 61.0 million, largely because of the 2029 convertible notes. That left per-share results essentially flat with last year's $0.36 even though non-GAAP net income rose to $24.1 million from $21.8 million. On a GAAP basis, EPS improved to $0.21 from $0.17. Results landed at the low end of the $0.35 to $0.49 guidance range, a step back from the prior quarter's beat.
The call nonetheless preserved, and arguably strengthened, a credible growth story. Management gave its first explicit view of 2027: roughly 40% growth, including supply constraints, and a path to more than $1 billion in revenue. The semiconductor segment is also expected to grow about 40%, led by advanced packaging, which is heading toward doubling. Compound semiconductor revenue nearly doubled sequentially to $40 million. The balance sheet backs up the demand claims. Customer deposits rose to $169 million from $114 million last quarter and $50 million at the end of 2025. Operating cash flow was $58 million, and cash and short-term investments reached $483 million. Pipeline wins are also broadening across products:
- A first Tier 1 logic revenue order for nanosecond annealing.
- A first NAND LSA shipment due by year-end.
- DRAM customers pulling in additional ion beam deposition tools.
- A high-volume GaN-on-silicon order for 2027.
- A panel-level tool shipped to a Tier 1 foundry.
Bears still have legitimate ammunition. Full-year revenue guidance rose again to $790 million to $820 million, but non-GAAP EPS guidance was cut to $1.32 to $1.52, the third consecutive reduction from an original $1.50 to $1.85. The 45% gross margin exit target for the second half has been abandoned. Fourth-quarter gross margin is now guided to 43% to 44%. Achieving the full-year range also requires a heavily back-end-loaded fourth quarter of $230 million to $260 million in revenue. New concerns emerged as well. Management cited industry-wide component shortages and longer lead times, and Veeco is now making advance payments to suppliers. The Axcelis merger close has slipped to the end of the first quarter of 2027 pending China regulatory clearance. Meanwhile, China revenue is expected to decline further, data storage softened to $20 million, and MOCVD share gains have been pushed to late 2027 or 2028. Management is also adding two contract manufacturers to more than double capacity. That should support the 2027 ramp, but it adds another execution variable.
The market setup is more complicated than the surprise implies. Investor sentiment improved meaningfully heading into the report, moving from modestly negative (-0.10) to positive (+0.27). The stock, however, told the opposite story. Shares fell 33.3% from the $56.04 open after the prior report to $37.39. They sit about 20% below the 200-day moving average and just 1.6% above the October 30 quarter low of $36.80, after peaking near $60 in early October. Earnings Whispers price and AVWAP trend readings are negative, while momentum is positive, reflecting a stock that has de-rated even as the operating outlook has improved.
The bottom line is that Veeco's demand story got bigger while its earnings story got smaller. Rising deposits, a higher revenue outlook and a 40% growth framework for 2027 point to genuine AI-driven momentum. However, a third consecutive EPS guidance cut, another gross margin miss and new supply constraints show that profitability has not kept pace with revenue. With the stock already down a third since the last report, the debate now centers on whether the fourth-quarter margin recovery to 43% to 44% actually materializes.
Read our earnings preview for Veeco Instruments Inc.: https://www.earningswhispers.com/article/VECO/21964
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Nov-02 | |
| Oct-27 | |
| Oct-21 | |
| Oct-14 | |
| Oct-13 | |
| Oct-08 | |
| Oct-05 | |
| Sep-30 | |
| Sep-21 | |
| Aug-17 | |
| Aug-12 | |
| Aug-06 |
