TKO's 22% EPS Beat Rides UFC's Skydance Step-Up, But Soft WWE Gates And A Debt-Funded Buyback Temper The Second Guidance Raise
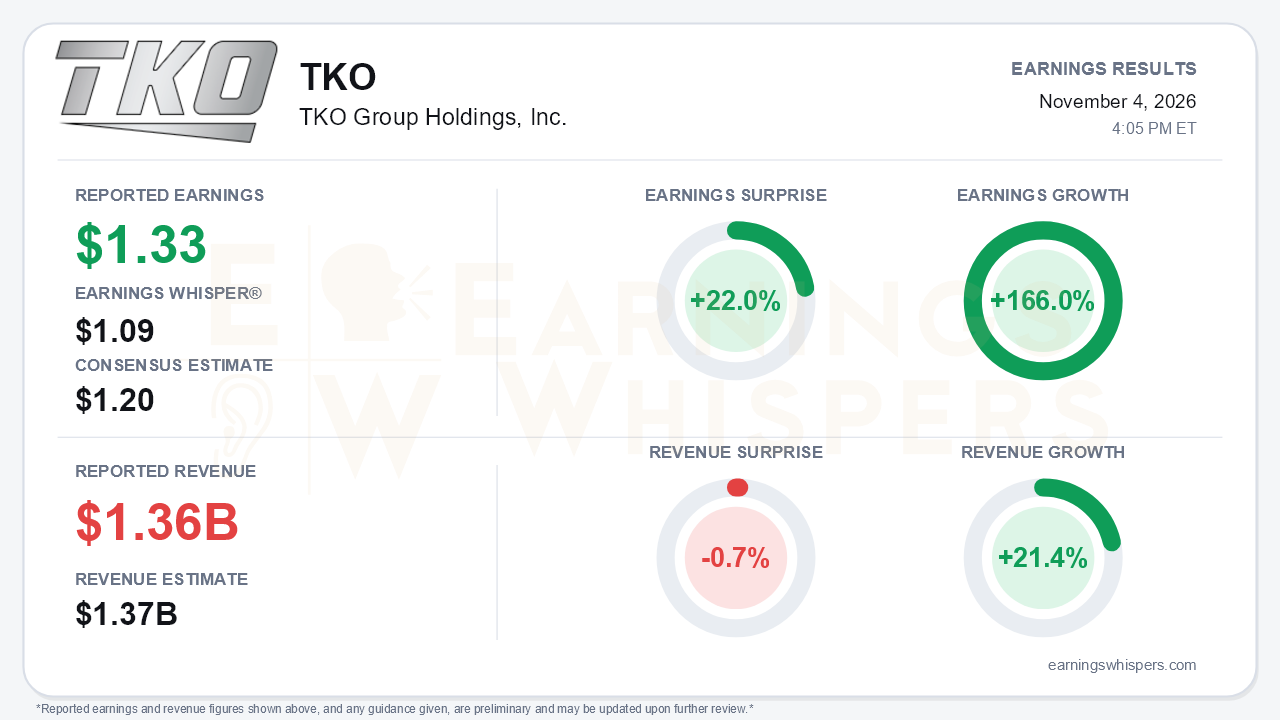
TKO Group Holdings delivered a decisive bottom-line beat for the third quarter. Diluted EPS of $1.33 topped the $1.20 consensus by 22.0% and cleared the more cautious $1.09 Earnings Whisper number. Earnings grew 166.0% year over year. Revenue rose 21.4% to $1.36 billion but slipped 0.7% below the $1.37 billion consensus. Management raised full-year guidance for the second time, lifting revenue to $5.790-$5.830 billion and Adjusted EBITDA to $2.295-$2.315 billion. The increases are modest, about $10 million and $15 million at the midpoints, and the raise landed in line with estimates rather than above them. The central tension is that TKO's profit engine is accelerating sharply while its top line is only keeping pace. Much of the earnings leverage comes from a single contractual step-up, financial engineering, and a once-every-four-years World Cup.
The quality of the beat deserves scrutiny. Adjusted EBITDA jumped 54% to $555.7 million, and margin expanded to 41% from 32%. That outpaced the nine-month EBITDA gain, which rose to $1.755 billion from $1.304 billion, so profitability clearly improved in Q3. GAAP net income nearly tripled to $277.9 million, helped by a $36.1 million drop in depreciation and amortization.
Per-share comparisons also benefit from an aggressive shrinking of the Class A share base. Basic weighted shares fell to about 73.1 million from 81.5 million, and the diluted count is not comparable year over year. Net income attributable to TKO rose to $98.7 million from $41.0 million, a strong gain but less dramatic than the EPS growth rate. Investors should also note $34.6 million of litigation costs excluded from Adjusted EBITDA.
The segment story is lopsided. UFC revenue surged 60% to $519.2 million and segment EBITDA climbed 72% to $285.3 million, with margin reaching 55%. Media rights revenue grew $132.3 million on the Skydance agreement that began in January, plus one extra Numbered Event and one extra Fight Night. The record UFC 329 gate added to the gains.
WWE was the soft spot. Revenue dipped 1% to $399.3 million as live events and hospitality fell 30% on three fewer Premium Live Events and weaker SummerSlam sales. Analysts pressed management on discounting, and management characterized the lower WrestleMania and SummerSlam gates as planned. WWE still expanded margin to 54% on lower event costs. Partnerships grew 28%, and management reaffirmed full-year partnership growth above 20%, which implies roughly 50% growth in Q4.
IMG was the swing factor. Segment EBITDA rose 89% to $115.9 million as margin jumped to 30% from 18%. Management said the FIFA World Cup produced about $90 million of full-year EBITDA versus a roughly $75 million plan, on $2.4 billion of hospitality sales. Bears have legitimate ammunition here: 2027 will lap those quadrennial On Location events while LA28 spending ramps.
The call preserved a credible growth story beyond the current year. The Paramount/Skydance combination with Warner Bros. Discovery adds TNT Sports and HBO alongside Paramount+ as outlets for UFC and Zuffa Boxing. Other new business includes:
- a WTA production deal and a Netflix production role for the 2027 Women's World Cup;
- WWE's launch on Netflix Japan;
- a Disney-partnered John Cena Classic;
- a December Fury-Joshua fight with rights sold to Netflix.
Management also floated a March Investor Day that could lift its global partnerships target. The guidance carries an explicit caveat, however. It assumes one WWE PLE and two UFC Fight Nights in the Middle East proceed despite regional conflict, and WrestleMania 2027 is slated for Saudi Arabia.
Capital allocation is turning more levered. TKO has returned over $1.6 billion year to date and intends to exhaust the remaining $936 million of its authorization, funded primarily by new debt and cash. Gross debt already stands at $4.647 billion, and net leverage is about 2.0x and set to rise. Cash flow is strong but flattered. Q3 free cash flow was $449.9 million at 81% conversion, but nine-month operating cash flow includes $604 million of World Cup prepayments held in escrow, which is not cash available for buybacks.
The market setup is more complicated than the surprise implies. Investor sentiment improved modestly, moving from slightly negative (-0.01) to mildly positive (0.09), a measured shift rather than enthusiasm. Shares closed at $187.20 heading into the report. That is 3.3% below the open after the August release, 3.1% under the 200-day moving average, and 7.8% off the August 20 high of $203.04. The stock set a 52-week low of $170.14 on October 28 and had rebounded 10% from it before earnings. Earnings Whispers trend signals for price, sequential growth, and AVWAP remain negative, consistent with a stock that has lagged its fundamentals.
The bottom line is that TKO's quarter showed real operating leverage, led by UFC's new media economics and an outsized World Cup contribution. However, the revenue miss, an in-line guidance raise, falling WWE gates, and a buyback increasingly financed with debt explain why investors have been slow to reward it. The durability case rests on contracted media revenue and the new distribution partners. The debate into 2027 is whether that growth can offset the loss of World Cup comparisons and Middle East event risk.
Read our earnings preview for TKO Group Holdings, Inc.: https://www.earningswhispers.com/article/TKO/21951
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| 5 hours | |
| 7 hours | |
| Oct-27 | |
| Oct-07 | |
| Sep-22 | |
| Sep-21 |
Silver Lake Takes On Carl Icahn and All of Merger Arbitrage in Endeavor Fight
TKO
The Wall Street Journal
|
| Sep-16 | |
| Sep-15 | |
| Sep-09 | |
| Sep-03 | |
| Sep-01 | |
| Aug-12 | |
| Aug-04 | |
| Aug-04 |
