TrueBlue's Growth Inflection Is Real, But Energy Mix And A Swelling Balance Sheet Test The Quality Of The Beat
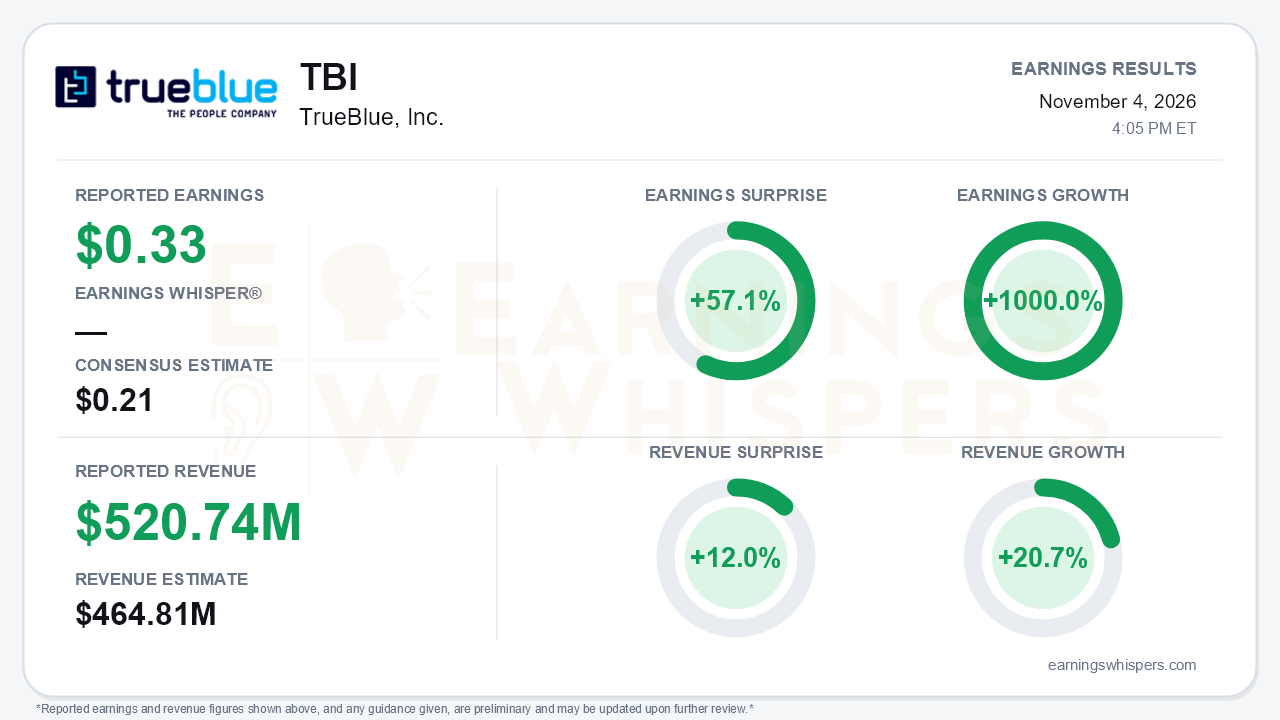
TrueBlue (NYSE: TBI) delivered its strongest quarter in years. Adjusted earnings of $0.33 per share beat the $0.21 consensus by 57.1%, and revenue of $520.74 million topped expectations of $464.81 million by 12.0%. Earnings grew 1000.0% from the year-ago $0.03, and revenue rose 20.7%. On a GAAP basis, the company swung to diluted earnings of $0.28 from a $0.06 loss. That ended a run of quarterly losses: management cited net losses of $32 million, $20 million and $3 million in the prior three quarters. The more important development is the trajectory. Revenue growth has stepped up from 8% to 8% to 12% and now 21%, well above the 7% to 11% guidance management set in August. Management then guided fourth-quarter growth to 20% to 24%, its highest outlook of the recovery.
The quality of the beat deserves scrutiny, because the growth is not coming from everywhere equally. PeopleReady did the heavy lifting. Segment revenue jumped 34% to $338 million, and segment profit more than doubled to $20.1 million from $8.1 million. The segment's exit rate accelerated to 42%, compared with 30% in the second quarter and 16% in the first. Energy revenue doubled again, its sixth straight quarter of growth. However, energy work carries pass-through travel costs, and that showed up in gross margin. Gross margin fell to 20.5% from 22.7% a year earlier and slipped from 20.7% in the second quarter. Operating leverage, not pricing, drove the profit inflection. Adjusted SG&A fell to 16.7% of revenue from 20.5%, and adjusted EBITDA nearly doubled to $20.7 million, a 4.0% margin versus 2.5%.
The call did preserve a credible broad-based recovery story beyond energy. All three segments grew, and every on-demand operating region expanded. PeopleManagement improved from a 6% decline in the first quarter to flat in the second and 2% growth now, with segment margin up 100 basis points. Its Onsite business won more than $50 million in annualized new business, up from $13 million in the first quarter. PeopleSolutions moved from a 7% organic decline in the first quarter to 1% growth and turned positive in September. New skilled-trades wins with a defense manufacturer and a steel products maker, plus a PeopleScout win with an energy company, broaden the pipeline. Management's tone shifted noticeably, from acknowledging "more work to do" earlier in the year to describing momentum "building as our strategy takes hold."
Bears have legitimate ammunition, however. Growth is consuming cash. Working capital absorbed $35 million in the quarter, after $22 million in the second quarter. Receivables have climbed to $327 million from $241 million at year-end, and year-to-date operating cash flow was negative $56 million. Debt rose to $102 million from $66 million at the end of 2025, while cash slipped to $20 million. Total liquidity did improve to $86 million. Management expects free cash flow to turn positive as working capital normalizes, but that remains a forecast, not a result. The cost-cutting tailwind is also fading. The year-over-year SG&A decline has narrowed from 11% to 3%, and fourth-quarter adjusted SG&A is guided up about 1% on incentive pay. Outside energy, pay rates rose 1.2% while bill rates rose only 0.4%, a 10-basis-point drag. Onsite client volumes and PeopleSolutions hiring remain soft. Management also flagged that lumpy third-quarter energy project volumes should normalize in the fourth quarter, with added holiday and weather effects. That makes the strong guide more dependent on the PeopleReady pipeline holding up.
Investor expectations had already shifted ahead of the report. Earnings Whispers sentiment swung from -0.19 after the August report to +0.16, a meaningful move from mildly negative to modestly positive. The stock closed at $9.59 on the day before the release. That is only 3.2% above the $9.29 open following the prior report, and 13.1% below the $11.03 52-week high set on August 19. Shares had given back much of that post-August spike before rebounding 18.9% off an October 19 low of $8.07. They remain about 40% above the 200-day moving average of $6.82, and the Earnings Whispers momentum and AVWAP trend readings are positive. The market has rewarded the turnaround, then hesitated over its durability.
The bottom line is that TrueBlue answered the biggest question turnaround skeptics were asking: whether growth could translate into profits. Accelerating revenue, a GAAP profit and a fourth-quarter outlook near 20% mark a genuine inflection. The next test is quality. Investors will want to see energy-driven growth that does not keep diluting gross margin, PeopleManagement and PeopleSolutions recovering beyond early gains, and working capital finally converting into the positive free cash flow management has promised.
Read our earnings preview for TrueBlue, Inc.: https://www.earningswhispers.com/article/TBI/21948
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Oct-27 | |
| Oct-26 | |
| Oct-21 | |
| Oct-15 | |
| Oct-14 | |
| Oct-14 | |
| Sep-30 | |
| Sep-02 | |
| Aug-27 | |
| Aug-19 | |
| Aug-05 | |
| Aug-04 |
