Caris Life Sciences Beats And Raises Again As Volume Accelerates, But Margins And Cash Flow Absorb The Cost Of Its Launch Cycle
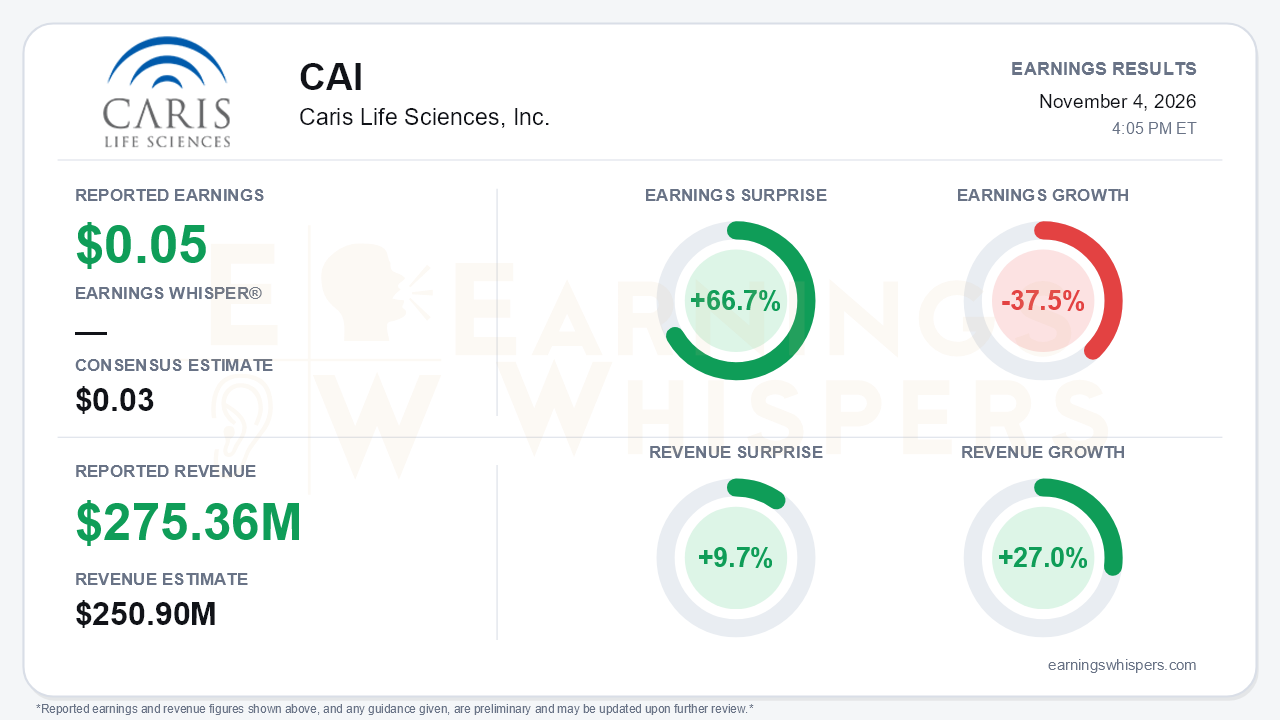
Caris Life Sciences delivered the kind of top-line quarter growth investors pay for. It also showed how expensive that growth has become. The company earned $0.05 per share against a $0.03 consensus, a 66.7% surprise. Revenue of $275.36 million topped the $250.9 million estimate by 9.7% and grew 27.0% year over year. Management raised full-year revenue guidance for the third time, to $1.04 billion to $1.05 billion, up from $1.03 billion to $1.04 billion after the second quarter and $1.00 billion to $1.02 billion originally. Beneath the beat, however, earnings fell 37.5% year over year, and nearly every profitability and cash metric stepped down. That is the central tension: demand is accelerating while Caris deliberately spends through its margin structure to fund four simultaneous product launches.
The volume story is the strongest part of the quarter. Clinical cases reached roughly 61,500, up 21%. That marks a third straight quarter of acceleration, following 18% growth in the second quarter and 15% in the first, and it cleared the 20% milestone management set on the prior call. Molecular profiling revenue grew 27% to $262.7 million on both volume and pricing. Base ASP rose 19% to about $3,990, up from more than $3,850 last quarter. Management also pointed to roughly 45% pro forma growth excluding prior-year true-ups, which suggests the reported 27% understates the underlying run rate. Fourth-quarter volume is guided to about 65,000 cases.
The quality of the earnings deserves scrutiny. Gross margin slipped to 66% from 68% both sequentially and year over year, and management guided to about 66% again in the fourth quarter on new-product mix. Operating expenses jumped 42% to $163.0 million, with selling and marketing up 45% and R&D up 56%. The full-year opex guide was raised again, to about $620 million from $595 million to $600 million. Adjusted EBITDA fell to $44.4 million, versus $55.7 million in the second quarter and $51.2 million a year ago. GAAP net income of $15.3 million put Caris back in the black after a slight first-half loss, but it trailed the $24.3 million earned in the prior-year quarter.
Cash flow is where bears have the most legitimate ammunition. Operating cash flow swung to a $22.2 million outflow from a $62.4 million inflow a year earlier. Free cash flow was negative $39.7 million, versus positive $55.3 million a year ago and $6.4 million last quarter. Management called the burn planned, and the balance sheet supports that explanation: supplies inventory has more than doubled since December, to $138.4 million, ahead of the launches. Still, year-to-date free cash flow is negative $10.8 million, so a positive full year now depends on a fourth-quarter rebound. Two other details also weigh on the picture. Pharma R&D revenue is tracking well below the original $75 million to $85 million guide on longer sales cycles. And the company dropped its tissue/blood volume and ASP breakouts while providing no Caris Detect volumes, which reduces visibility just as the mix grows more complex.
The catalyst slate explains why management sounded more confident and framed the quarter around the plan working. Caris Assure Therapy Response Monitoring launched, with a MolDX submission planned. Caris Confirm, a whole-genome, tumor-informed MRD assay, is slated for December. The preliminary 2027 Clinical Lab Fee Schedule raises the Caris Assure rate to $5,250 from $3,650, a meaningful pricing tailwind that should carry into contracted commercial rates. The ACHIEVE-2 interim readout is expected in the first quarter of 2027. Detect consumer campaigns are live, and the commercial team has grown to 325 reps with no stated stopping point. The caveat is that monitoring and MRD launch without reimbursement, and Detect capacity is still being built.
The market had already moved aggressively toward the bullish reading before the report. Shares rose 72.9% from the $19.00 open after the August report to $32.85, sit about 52% above the 200-day moving average, and set a 52-week high of $36.50 on October 28 before easing roughly 10%. Investor sentiment improved substantially, from -0.28 to +0.05, moving from clearly negative to roughly neutral. Momentum and AVWAP trend readings are positive. That run means the volume acceleration and guidance raise were at least partly anticipated, while the margin and cash-flow step-down was less likely priced in.
The bottom line is that Caris delivered accelerating demand, rising ASPs, a third guidance increase and a meaningful 2027 reimbursement tailwind. That is a credible growth story. The cost is falling gross margin, lower EBITDA, a cash burn and thinner disclosure. With the stock entering the report after a 73% run, the debate now shifts from whether demand is real to whether the launch spending converts into reimbursed revenue and renewed margin expansion in 2027.
Read our earnings preview for Caris Life Sciences, Inc.: https://www.earningswhispers.com/article/CAI/21798
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| 7 hours | |
| Oct-27 | |
| Oct-19 | |
| Oct-15 | |
| Oct-14 | |
| Oct-02 |
IPO Stock Of The Week: Caris Pulls Back After More Than Doubling In Just Two Months
CAI
Investor's Business Daily
|
| Sep-23 | |
| Sep-22 |
Caris Life Sciences Coasts Past A Buy Point; Why This Texas Biotech Researcher Deserves A Look
CAI
Investor's Business Daily
|
| Sep-18 | |
| Sep-08 | |
| Sep-02 | |
| Aug-27 | |
| Aug-06 | |
| Aug-05 |
