Essential Utilities Beats On Rate Relief And Lower Costs, But Stops Reaffirming Its Long-Term EPS Outlook Ahead Of The American Water Merger
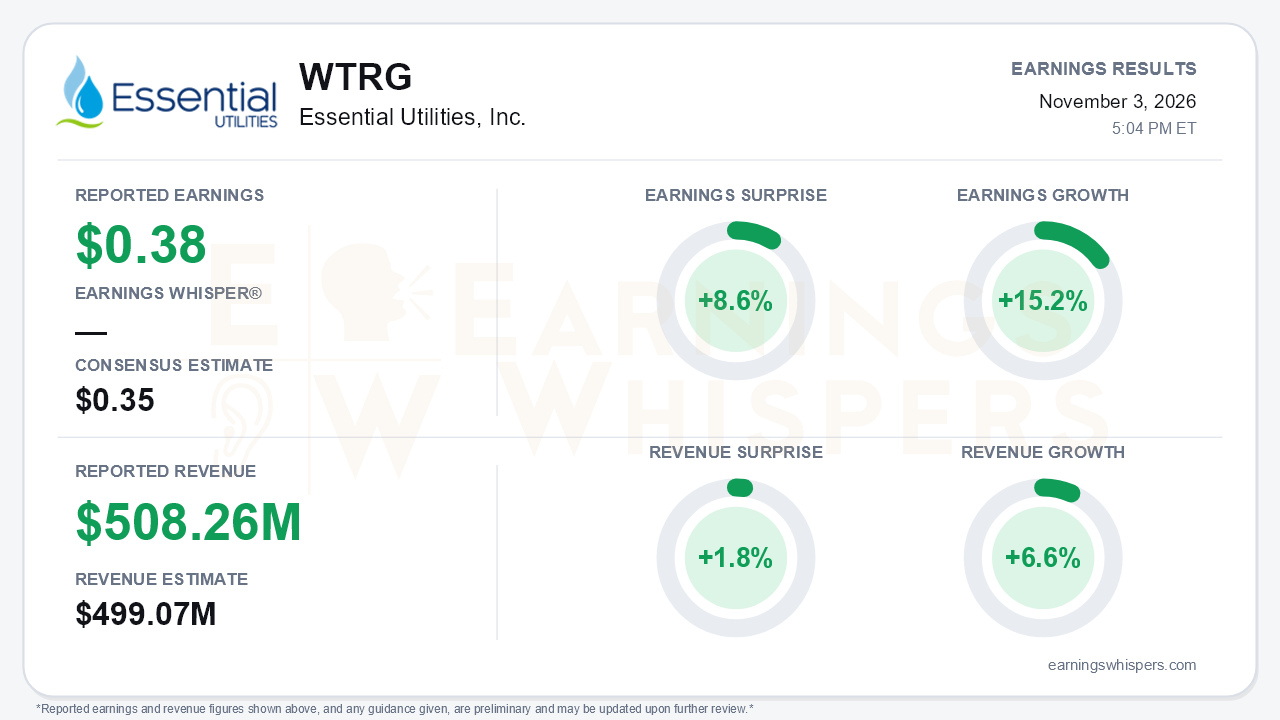
Essential Utilities delivered a clean third-quarter beat, but the more important development was what management stopped saying. Adjusted earnings of $0.38 per share topped the $0.35 consensus by 8.6% and grew 15.2% year over year. Revenue of $508.26 million beat expectations by 1.8% and rose 6.6%. GAAP EPS was $0.36, up from $0.33, with the gap to the adjusted figure reflecting $4.9 million of pre-tax costs tied to the pending American Water merger. The numbers were solid. However, the company's long-standing 5%-7% EPS growth target, off a $1.97 2024 base, was reaffirmed on the prior three calls and was left out this time. That is the central tension. The quarter beat expectations, but the standalone earnings story is being handed off to a combined company that has not yet issued its own outlook.
The quality of the beat deserves some scrutiny. Revenue growth came mostly from regulatory recoveries and higher purchased gas costs, which is the expected pattern for a regulated utility. The bigger swing factor was expenses. Total O&M slipped 0.6% to $152.2 million, and excluding merger costs it fell $5.9 million. Management attributed the decline to insurance recoveries and lower bad debt in the gas segment. Gas segment O&M dropped to $43.0 million from $47.5 million. Management itself said that, excluding one-time items and weather, full-year O&M should track historic norms, so investors should not extrapolate this quarter's cost relief. Below the operating line, conditions were less favorable:
- Interest expense rose to $91.3 million from $82.3 million.
- Depreciation climbed as the capital program expanded.
- Adjusted EPS was flat sequentially with Q2's $0.38.
- Year-to-date GAAP EPS of $1.53 still trails last year's $1.73, which benefited from an income tax benefit. Adjusted nine-month EPS was $1.58.
The operating drivers beneath the headline are steadily improving. Finalized 2026 rate recoveries reached $70.5 million, up from $56.6 million at the Q2 call and $15.1 million at Q1. On the call, management's year-over-year EPS bridge credited rate recoveries with $0.06 and water volumes with $0.01. Pending water and wastewater requests eased to $78.5 million from $79.7 million, mainly because cases converted into approved revenue rather than because the pipeline weakened. Capital spending reached about $1.1 billion year to date, keeping the company on track for a record $1.7 billion in 2026. Management framed five-year capex at at least $8.7 billion. The signed acquisition pipeline edged up to roughly $290 million and 208,000 customers, helped by four small October deals. About $276.5 million of that total is DELCORA, however, and that transaction remains stalled by a bankruptcy court stay.
The near-term catalysts are mostly regulatory:
- **Pennsylvania gas rate case:** an administrative law judge recommended roughly $105 million against the $163.2 million requested, with a final order expected in December. That would be a meaningful but partial win.
- **Merger approvals:** settlements in Pennsylvania, North Carolina and Texas now join approvals already secured in Kentucky, Ohio and Virginia. At the Q2 call, only Texas had reached agreement in principle. Management reiterated a first-quarter 2027 close.
- **Cost of capital:** the Pennsylvania PUC chairman's new ROE working group could prove constructive.
Bears have legitimate ammunition on the affordability front. The Pennsylvania governor's letter, new officials taking office after the election, and continued ROE pressure all weigh on the outlook for allowed returns. PFAS settlement implications went unaddressed on the call. The CEO's comment that EPS guidance "doesn't make a whole lot of sense" ahead of the close is understandable, but it leaves shareholders without a standalone earnings anchor.
The market setup is more complicated than the surprise implies. Shares have gained 10.9% since the open after the August report, reaching $44.04, and sit 11.6% above the 200-day moving average of $39.45. Price and AVWAP trend readings are positive, while sequential growth and momentum are neutral. Investor sentiment moved the other way, falling from -0.28 to -0.51. A rising stock alongside souring sentiment suggests the share price is increasingly trading on merger mechanics rather than enthusiasm for Essential's standalone fundamentals. The current portion of long-term debt also jumped to $670 million from $172 million at year-end, which points to refinancing needs in a period of higher interest costs.
The bottom line is that Essential delivered a better-than-expected quarter built on rate recoveries and record infrastructure investment, with an assist from non-recurring insurance and bad-debt benefits. The merger is clearly progressing, and the December Pennsylvania gas order is the next tangible test. With the 5%-7% growth target no longer reaffirmed, sentiment deteriorating and shares already well above their long-term average, the investment case now rests less on Essential's own earnings trajectory and more on regulatory approvals and what the combined American Water entity ultimately promises.
Read our earnings preview for Essential Utilities, Inc.: https://www.earningswhispers.com/article/WTRG/21646
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| Nov-03 | |
| Nov-03 | |
| Oct-26 | |
| Oct-21 | |
| Oct-16 | |
| Oct-14 | |
| Oct-14 | |
| Oct-12 | |
| Oct-08 | |
| Oct-05 | |
| Sep-30 | |
| Aug-17 | |
| Aug-10 | |
| Aug-05 |
