Remitly's Profit Surge And Fourth Guidance Raise Collide With Cooling User Growth And A Slower FY27 Outlook
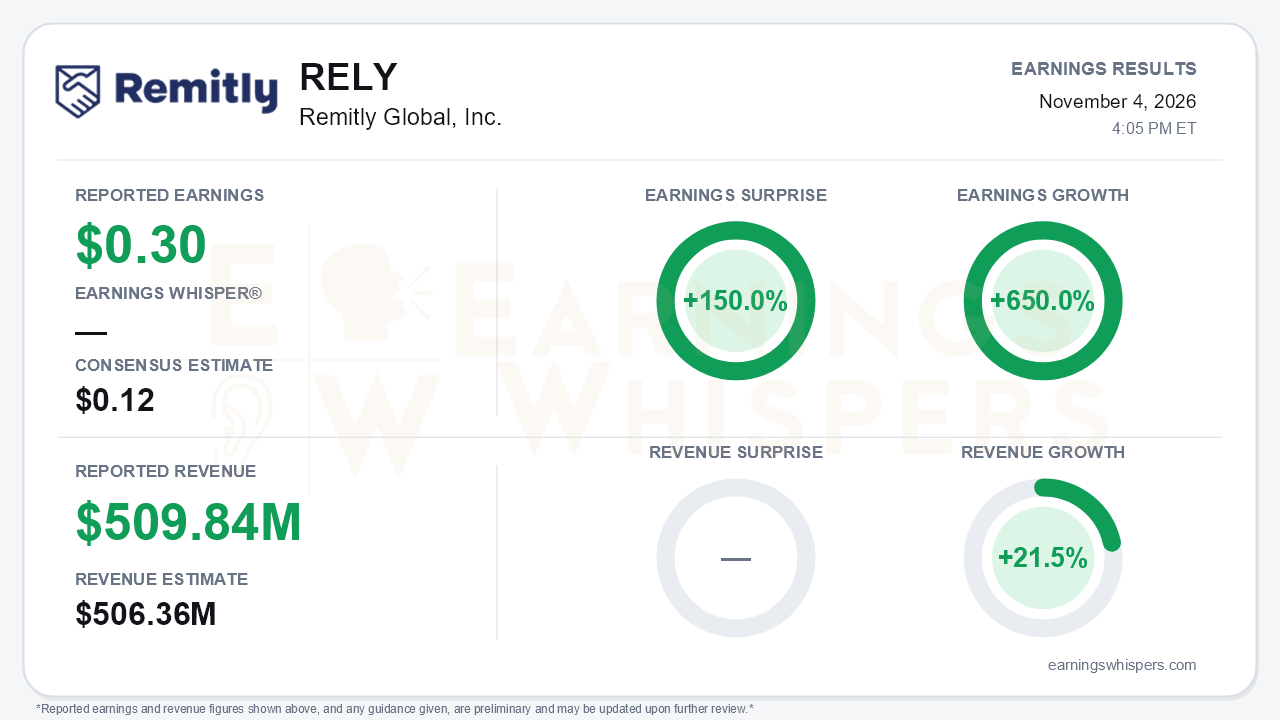
Remitly Global delivered a decisive bottom-line beat in the third quarter, but the more important story is what comes after it. The company earned $0.30 per diluted share, 150.0% above the $0.12 consensus estimate and up 650.0% from a year earlier. Revenue of $509.84 million rose 21.5% and topped consensus by 0.7%. Revenue growth also picked up from roughly 20% in the second quarter, the first sequential acceleration of the year. Management raised full-year guidance for the fourth consecutive time. Yet the same call introduced a preliminary 2027 view of slower growth and no further margin expansion. That is the central tension: Remitly's profitability inflection is real, but the engine behind it is visibly downshifting.
The earnings beat was driven mainly by operations, not accounting. Income from operations jumped to $69.4 million from $11.8 million. The two biggest contributors were wider transaction economics and expense discipline. Transaction expenses grew about 11% against 21.5% revenue growth, pushing transaction margin to 68% from 65%, a 312-basis-point improvement that exceeded the second quarter's 235-basis-point gain. Below that line, technology spending was essentially flat in dollars and non-GAAP G&A was unchanged year over year. Only marketing grew meaningfully. Adjusted EBITDA nearly doubled to a record $120.8 million, a 24% margin, and came in $28 million above the guidance midpoint. One caveat on the GAAP figure: the quarter's $2.2 million tax provision on $69.8 million of pretax income implies a very light effective rate, which flatters net income somewhat. The large deferred tax benefit that inflated year-to-date earnings was booked earlier in the year, not in this quarter.
Beneath the margin story, the growth indicators are cooling.
- **Active customers:** quarterly active users grew 17% to 10.3 million, down from 20% in each of the first two quarters. Analysts pressed management on this twice during the call.
- **Send volume:** growth slowed to 25%, from 27% in the second quarter and 37% in the first.
- **Large transfers:** growth fell to 25%, from 37% and 73% earlier in the year. Management attributed this to a Reserve Bank of India FX mobilization scheme and possible pull-forward.
- **Revenue beat:** the margin over guidance shrank to $4 million, from $11 million in the second quarter and $16 million in the first.
- **Free cash flow:** $87.8 million was modestly above last year but well below the second quarter's $130 million-plus.
There are offsets. Rest-of-world revenue growth improved to 23% from 18%, large transfers outside India grew 80%, and Remitly Business reached 30,000 users, up from 25,000 last quarter.
The forward guidance is where bears have legitimate ammunition. Fourth-quarter revenue guidance of $531 million to $533 million implies 20% to 21% growth, with an adjusted EBITDA margin near 20%. Management also expects transaction margin to moderate against a tough loss-rate comparison and marketing spend per active user to rise. For 2027, management previewed revenue growth at the lower end of the high teens, as the tailwind from the 1% U.S. cash remittance tax laps. Adjusted EBITDA margin is expected to be broadly flat with 2026 as investment normalizes after this year's cost reassessment. Management reaffirmed its rule-of-40-plus target through 2028, but the message is clear: the margin-expansion phase that powered 2026 is pausing.
The product pipeline gives the diversification thesis more substance:
- Sending launched from Brazil, the first market where customers can both send and receive in the app.
- The Remitly Global Card reached general availability across the U.S., adding domestic person-to-person transfers.
- Etsy signed as the first business-payments platform partner, covering sellers in 15 countries.
- New FX protection and guaranteed instant transfers target customers who regularly send more than $5,000.
The call also spent considerable time on competitive questions around pricing, stablecoins and zero-fee neobank transfers, a sign that investors see these as real long-term risks.
Capital allocation turned noticeably more shareholder-friendly. The buyback authorization rose to $500 million from $200 million. Long-term debt fell to zero from $155 million at year-end, cash climbed to $669 million, and the revolver was upsized to $1 billion. Stock-based compensation is now expected to decline modestly in 2026, and the adoption of diluted EPS as a key metric signals that management wants to be judged on per-share earnings.
Investors were not leaning bullish heading into the report. Earnings Whispers sentiment stayed negative and weakened modestly, slipping to -0.32 from -0.26. The stock's path has been volatile. Shares set a 52-week high of $27.48 on September 3, fell to $19.53 by September 23, then rebounded about 30%. At $25.38, the stock sat 2.3% below the open following the August report, 7.6% below that high and 23.4% above its 200-day moving average. Most Earnings Whispers trend readings are positive, with price trend neutral. Even so, net price progress since the last report has been minimal despite steadily rising guidance.
The bottom line is that Remitly posted a high-quality profit beat built on real margin gains, debt reduction and an expanded buyback. However, decelerating users, volume and large transfers, combined with a 2027 outlook for slower growth and flat margins, mean the next leg of the story depends on whether new products can reaccelerate customer growth rather than on further cost leverage.
Read our earnings preview for Remitly Global, Inc.: https://www.earningswhispers.com/article/RELY/21922
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 12 hours | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Oct-27 | |
| Oct-21 | |
| Oct-02 | |
| Sep-24 | |
| Sep-09 | |
| Aug-14 | |
| Aug-07 | |
| Aug-06 | |
| Aug-05 | |
| Aug-04 | |
| Jul-30 |
