Pursuit Beats On Accelerating Pricing, But Narrowed Guidance And A Construction-Heavy 2027 Temper A Rally Near Highs
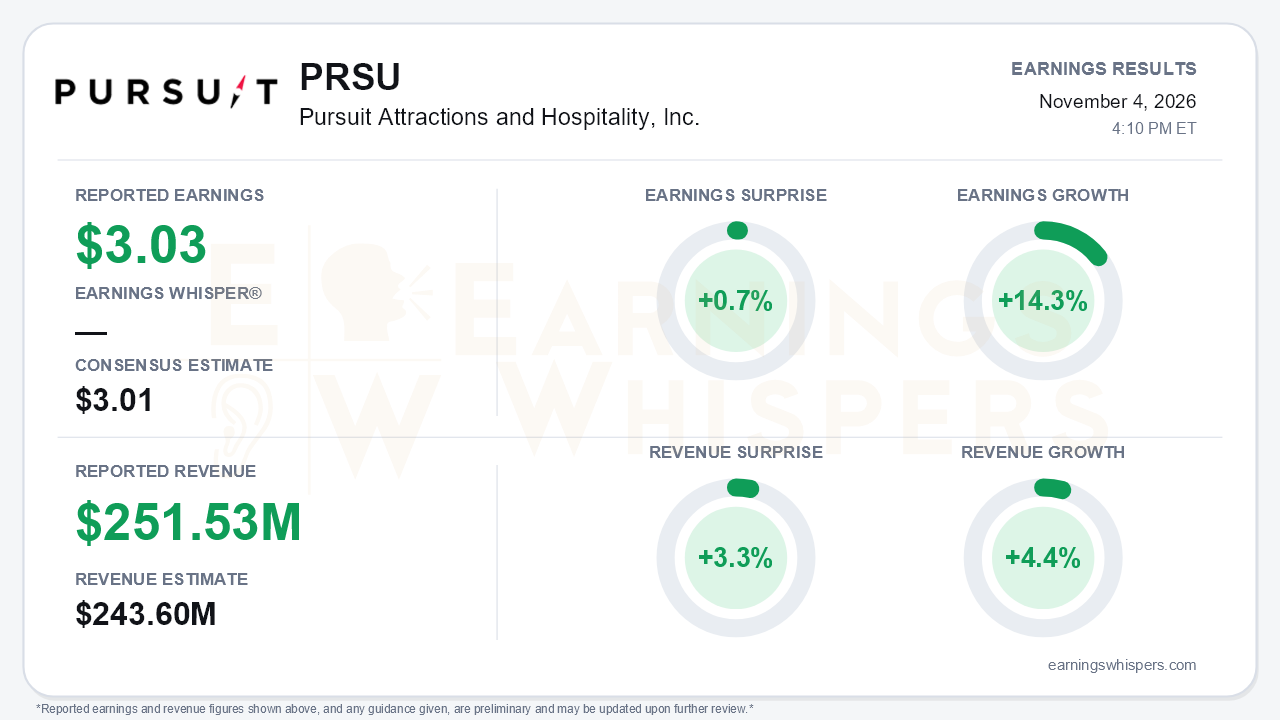
Pursuit Attractions and Hospitality delivered a record third quarter that was better on revenue than on earnings. Adjusted EPS of $3.03 edged past the $3.01 consensus by 0.7% and grew 14.3% year over year. Revenue of $251.53 million beat the $243.6 million estimate by a wider 3.3% margin. The central tension is that headline revenue growth slowed sharply, to 4.4% from 14% in the second quarter and 37% in the first, while the underlying pricing engine actually accelerated. Much of the headline slowdown is mechanical. Pursuit is now lapping the July 2025 Tabacón acquisition and absorbing the July sale of Flyover. Adjusting for Eagle Wing Tours and Flyover, revenue grew about 6%.
The quality of the beat deserves some scrutiny. Same-store attraction effective ticket prices rose 9%, up from 6% in the second quarter and 5% in the first. Lodging RevPAR also grew 9%, on a 7% ADR gain and a two-point occupancy improvement. Adjusted EBITDA rose 7% to $125.5 million, and margin expanded to 49.9% from 48.7%. That reverses the roughly 90 basis points of margin contraction in the second quarter, and management cited roughly 56% flow-through excluding Flyover. However, the 14% adjusted EPS growth leaned on more than operations:
- Depreciation fell 15%.
- Net interest expense dropped 29%.
- The noncontrolling-interest share of EBITDA shrank, so EBITDA attributable to Pursuit rose 13.2%, nearly double the consolidated gain.
- Diluted shares declined 1.5% on buybacks.
On a GAAP basis, diluted EPS rose to $2.95 from $2.60. That came despite a $2.8 million loss on the Flyover sale and a higher 19.7% tax rate, and without the $4.2 million wildfire insurance gain that flattered last year's quarter. Pricing outpacing total same-store growth also suggests volume remains modest. Management acknowledged that weather and smoke again hampered attraction visitation.
The call preserved a credible growth story. Management described no signs of demand weakening and pointed to a strong September and October. Early 2027 booking pace is running ahead of last year, with healthy tour-and-travel allocations and signs of recovery in China. Balance-sheet capacity improved meaningfully: liquidity reached about $293 million, versus roughly $220 million pro forma at the second quarter. Net leverage of 0.6x sits far below the company's 2.0x-3.5x target range, aided by the roughly $75 million Flyover sale.
Guidance was the less inspiring part of the report. Pursuit reaffirmed its $133 million full-year adjusted EBITDA midpoint, implying about 14% growth, and narrowed the range to $130-$136 million. The floor rose $2 million, but the ceiling fell by the same amount, so the core outlook is effectively unchanged. Revenue guidance sits at a $485 million midpoint, which Earnings Whispers notes is above estimates.
The forward story is increasingly about capital deployment, and the timing cuts both ways. The Jasper SkyTram lift has been ordered for construction in 2027 and an opening in 2029. The tram goes fully offline during that period, creating a temporary EBITDA drag. Several lodging properties also face construction disruption in 2027, growth capex is set to step up, and the roughly $7 million of Flyover EBITDA must be replaced. Management expects to more than offset Flyover through core growth, net project benefits and about $1 million from Eagle Wing. That is a management expectation, not a result.
The upside catalysts are tangible but long-dated:
- the proposed Glacier View Tram, submitted to the U.S. Forest Service and incremental to Vision 2030;
- a new Banff/Jasper lake cruise boat for 2028;
- a new Pursuit.com booking platform launching late this year;
- a new chief commercial officer from Ticketmaster.
Vision 2030 targets an effective EBITDA multiple below 7x on more than $300 million of organic investment. Bears have legitimate ammunition in the execution and disruption risk that sits between here and there.
The market setup is more complicated than the surprise implies. Investor sentiment moved from roughly neutral (-0.02) to modestly positive (0.20), a meaningful but not euphoric shift. Shares closed at $56.10 before the report. That is up 6.7% from the open after the August release and about 25% above the August 10 low of $44.82. It also leaves the stock 24.2% above its 200-day moving average and just 3% below the 52-week high of $57.84 set November 2. The Earnings Whispers trend readings are mostly positive on price and momentum, but sequential growth remains negative, consistent with the decelerating headline revenue line. Entering earnings near the top of its range, the stock needed more than a two-cent EPS beat and an unchanged midpoint to justify fresh upside.
The bottom line is that Pursuit's underlying business looks stronger than its 4.4% headline growth suggests. Pricing accelerated, margins expanded and the balance sheet is underlevered. However, guidance held rather than rose, and 2027 brings a construction-heavy transition with the SkyTram offline. With shares already near their highs, the report validates the recent rally more than it extends the investment case.
Read our earnings preview for Pursuit Attractions and Hospitality, Inc.: https://www.earningswhispers.com/article/PRSU/21913
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 6 hours | |
| Oct-27 | |
| Oct-13 | |
| Oct-01 | |
| Aug-06 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 | |
| Jul-31 | |
| Jul-15 | |
| Jul-15 | |
| Jun-09 | |
| May-06 | |
| Apr-21 |
