MercadoLibre Misses On EPS As Investment Spending Outruns 45% Revenue Growth And Margins Compress Again
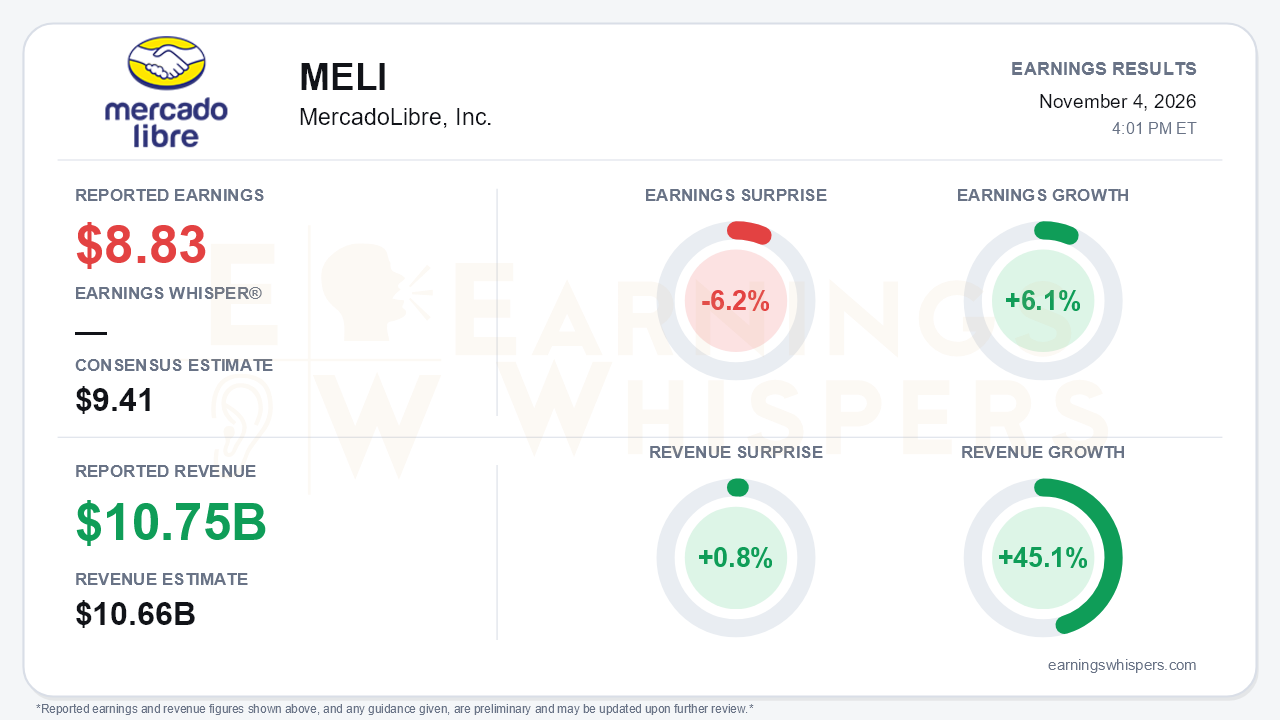
MercadoLibre delivered another quarter of strong top-line growth and a bottom line that fell short. Third-quarter earnings of $8.83 per share missed the $9.41 consensus by 6.2%. Revenue of $10.75 billion beat the $10.66 billion estimate by 0.8%. The gap between the two growth rates is the story. Revenue rose 45.1% year over year, while earnings grew only 6.1%. The company is still adding customers, items, and loans quickly, but almost none of that growth is reaching the income statement. Management is deliberately spending ahead of demand on logistics, affiliates, and AI. That is the central tension: engagement and unit economics are improving, but top-line growth is slowing and margin pressure is getting worse, not better.
The quality of the quarter deserves scrutiny on two fronts. First, the reported revenue figure overstates the underlying pace. On the call, management cited FX-neutral net revenue growth of 41%. That is down from 45% in Q4 FY25 and from 49% in Q1, which was a four-year high. The reported dollar growth rate therefore appears to include some currency help, and the currency-neutral trend shows deceleration for a second straight period. Second, EBIT margin fell to 6.3% from 6.7% in Q2. The call attributed roughly 60 basis points to shipping headwinds. Those included a 20% quarter-over-quarter build in fulfillment capacity, higher energy costs, smaller baskets, and temporary recruitment costs. Another 40 basis points came from higher sales and marketing, which rose to 11.6% of revenue. The formal press release offered no detail beyond pointing investors to the shareholder letter, so the operating picture comes almost entirely from the call.
The commerce engine looks healthier than the margin line suggests:
- **Brazil volume:** commerce GMV grew 36%, versus 35% in Q4 FY25. Items per buyer rose 16% even after lapping the free-shipping threshold cut.
- **Shipping costs:** FX-neutral cost per shipment in Brazil fell 5% year over year and is 14% below where it stood before the threshold change.
- **Free-shipping economics:** free shipments in the R$19–79 band turned variable-contribution positive for the first time in September. That is meaningful evidence that last year's shipping subsidy is maturing into a profitable driver of purchase frequency.
- **Affiliates:** affiliate orders jumped 240% and the network now exceeds 12 million members.
- **Product development:** spending gained 70 basis points of leverage despite heavy AI investment.
Growth in the higher-margin layers is cooling, however. Advertising grew 58%, down from 73% in Q2 and 67% in Q4 FY25. Fintech is moderating as well. The credit portfolio reached roughly $19 billion, up from $16.4 billion in Q2, but year-over-year growth slowed to 62% from 75%. Assets under management growth eased to 67% from 78%. Credit quality is holding: 15–90 day NPLs were stable at 7.0%, Argentina NPLs sit near historical lows, and card issuance set a record. Management is nonetheless tightening underwriting in riskier Brazil segments as system-wide credit weakens in Brazil and Argentina. Card mix and lower Argentine lending rates are pressuring net interest margin after losses, and a more upmarket mix lowered the acquiring take rate.
The forward cost picture gives bears legitimate ammunition. Management framed affiliate spending as ongoing and expects only a partial Q4 reversal of capacity costs. Other pressures are adding up:
- energy and fuel costs that are only partly passed through to customers;
- Brazil's constitutional workweek change, which may require more logistics headcount;
- memory-chip-driven cost increases on point-of-sale devices;
- Asian cross-border competition threatening Argentina's margin premium.
AI spending rose by about $30 million quarter over quarter. Elsewhere on the call it was described as roughly $100 million of incremental spend, so the figure depends on the comparison period. On the catalyst side, there are several items to watch:
- an in-house agentic shopping assistant now live for a small share of users in the three largest markets, with inventory withheld from third-party agents;
- expanded free shipping for loyalty members in Argentina;
- about 20% more fulfillment capacity added ahead of peak season, with automation investment tripled.
The market had already turned cautious before the report. Shares were trading at $1,662 going into the release, down 8.9% from the opening price after the August report and 8.3% below the 200-day moving average of about $1,812. The stock peaked at $2,066 on September 3 and slid to a $1,570.76 low on October 26. It entered earnings 19.5% below that high and just 5.8% above the low. Investor sentiment remained negative but improved, moving from -0.23 to -0.12. That suggests some pre-report capitulation had already occurred. The Earnings Whispers trend readings lean negative on price and AVWAP, though the sequential-growth reading is positive, consistent with the still-rising credit book and Brazil GMV.
The bottom line is that MercadoLibre's quarter rewards patience on unit economics and tests it on profitability. Free-shipping contribution, cost per shipment, items per buyer, and affiliate traction all argue that the investment cycle is working. But revenue growth is decelerating, advertising and credit growth are cooling, and management has given no clear signal that margins will stop compressing soon. Until operating margin stabilizes, the operational improvements will likely be weighed against an earnings line that keeps lagging the top line.
Read our earnings preview for MercadoLibre, Inc.: https://www.earningswhispers.com/article/MELI/21871
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 4 hours | |
| 4 hours | |
| 4 hours | |
| 6 hours | |
| Nov-02 | |
| Oct-30 | |
| Oct-29 | |
| Oct-28 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-26 | |
| Oct-26 | |
| Oct-26 |
