Lumen Beats On EPS As Debt Paydown Masks Wider Business Revenue Decline; Copper Exit Adds A New Lever
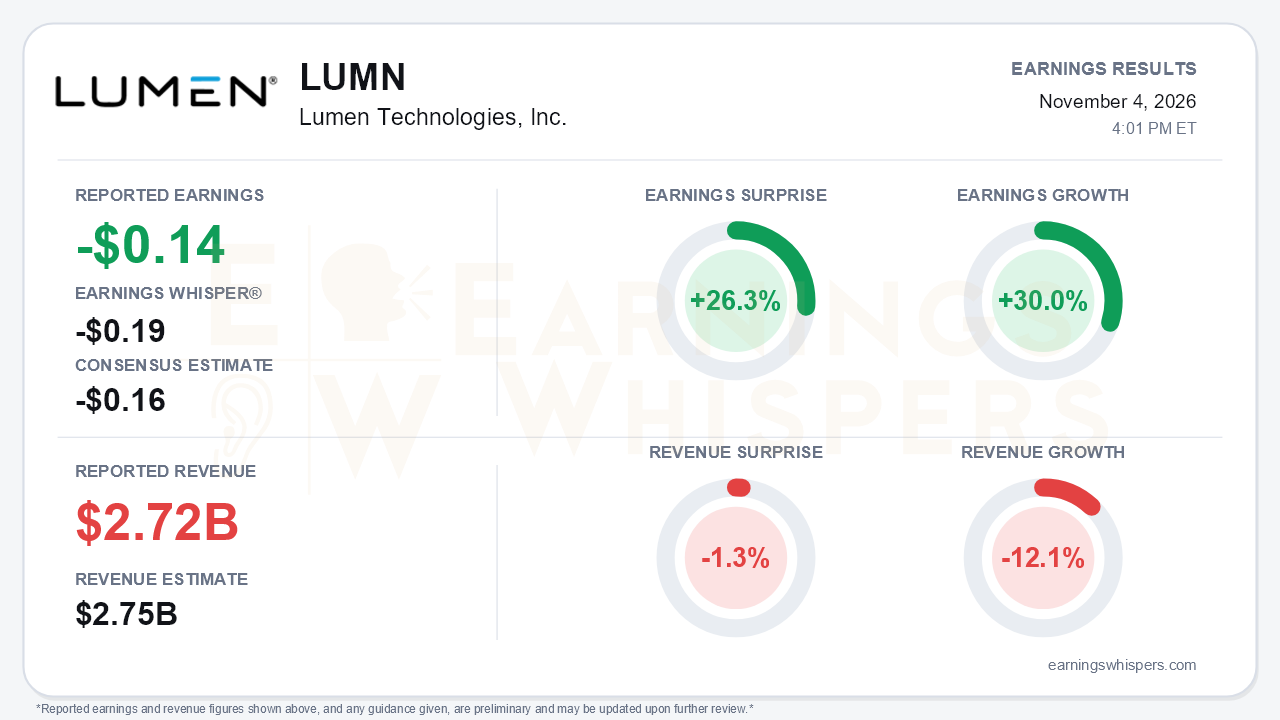
Lumen Technologies (NYSE: LUMN) reported an adjusted loss of $0.14 per share for the third quarter, ahead of the $0.16 consensus loss and well ahead of the more pessimistic -$0.19 Earnings Whisper number. That is a 26.3% surprise and 30.0% year-over-year earnings growth. Revenue of $2.715 billion missed the $2.75 billion consensus by 1.3% and fell 12.1% year over year, much of it from the divested Mass Markets fiber business. Management reaffirmed full-year guidance. That is the central tension. The quarter's leading indicators (bookings, mix and AI-driven wavelength demand) are clearly improving, while the reported business revenue line is moving the wrong way.
The quality of the beat deserves scrutiny. Adjusted EBITDA excluding special items fell to $715 million from $787 million a year ago. The narrower per-share loss came largely below the operating line, where interest expense dropped to $189 million from $319 million after the company used divestiture proceeds to cut long-term debt to $13.2 billion from $17.4 billion. Margin did improve, with adjusted EBITDA margin excluding special items rising to 26.3% from 25.5% as the revenue base shifted toward higher-value services. Lumen also stripped a $27 million Connect America Fund catch-up payment out of its adjusted figures, so the non-GAAP numbers were not flattered by that item. On a GAAP basis, the loss narrowed to $0.26 per share from $0.62, though modernization charges more than doubled to $156 million.
Beneath the headline, the mix story strengthened and the growth story softened. Strategic revenue rose 10% to $1.28 billion and reached 55% of business revenue, up from 53% last quarter and 48% a year ago. However, Strategic growth decelerated from 14% in the second quarter. Legacy revenue fell 17%, and total business revenue declined 4.5%, a wider drop than the 1.8% decline in Q2. North America enterprise revenue fell 3.1% versus just 0.2% a quarter earlier, and Public Sector dropped 12% sequentially. Forward indicators were stronger:
- Strategic sales rose 30% year over year, and Strategic wave sales grew 22% sequentially.
- Wavelength installs for AI companies are up more than fivefold over twelve months.
- Digital revenue jumped to $56 million from $39 million, helped by the Alkira acquisition, and management said growth excluding Alkira was still double-digit.
Management was notably more assertive, telling investors not to "get too wrapped up in total revenue" and disclosing Strategic direct margins above 80% versus roughly 65% for legacy. The biggest new lever is accelerated copper decommissioning in Florida, Iowa, Nevada and Utah, roughly a quarter of the copper footprint. Management pegged this at $1.0-1.5 billion of pre-tax value from mined copper plus $200-300 million a year of avoided maintenance capex over time. Bears have legitimate ammunition, though. The copper exit removes revenue before costs come out, it depends on regulatory approvals and copper prices, and it will likely pressure reported revenue further. Lumen also plans to stop disclosing NaaS adoption metrics just as that customer count passed 4,000. Other additions included an expanded Microsoft co-sell arrangement and $700 million of new PCF deals, which lifted the cumulative total above $13.5 billion.
Cash flow is the near-term pressure point. Free cash flow excluding special items was -$76 million, versus +$327 million in Q2, as PCF cash receipts fell to $117 million from $476 million. Year-to-date free cash flow stands at about $1.0 billion against a reaffirmed $1.9-2.1 billion target, and that target includes $729 million of divestiture proceeds already booked in Q1. Hitting the low end implies roughly $900 million in Q4. Similarly, year-to-date adjusted EBITDA of $2.37 billion requires a meaningful fourth-quarter step-up to reach the $3.1-3.3 billion range. Both depend heavily on the timing of PCF payments.
The market setup is more complicated than the surprise implies. Shares entered the report at $4.75, down 27.5% since the post-Q2 open and about 34% below the 200-day moving average of $7.23. The stock set a 52-week low of $4.25 on October 22 after peaking at $7.27 in September, and it now sits only modestly above that low. Investor sentiment nonetheless improved meaningfully, rising from essentially neutral (0.01) to modestly positive (0.29) heading into the print. Expectations were therefore warming even as the stock's trend readings stayed mostly negative.
The bottom line is that Lumen delivered a cleaner bottom-line beat than its revenue line deserved, and the beat was driven more by deleveraging than by operating growth. The call preserved a credible Strategic growth narrative and added a tangible copper-monetization catalyst. Still, widening business revenue declines, slowing Strategic growth, a negative cash quarter and a back-end-loaded guide leave Q4 execution as the real test of whether the transformation is reaching the income statement.
Read our earnings preview for Lumen Technologies, Inc.: https://www.earningswhispers.com/article/LUMN/21865
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-02 | |
| Oct-29 | |
| Oct-27 | |
| Oct-20 | |
| Oct-15 | |
| Oct-14 | |
| Oct-13 | |
| Oct-13 | |
| Oct-09 | |
| Oct-08 | |
| Oct-07 | |
| Oct-06 | |
| Sep-29 |
