FICO Tops Estimates And Software Accelerates, But Withheld Guidance And A Frozen Mortgage Price Cloud The Scores Engine
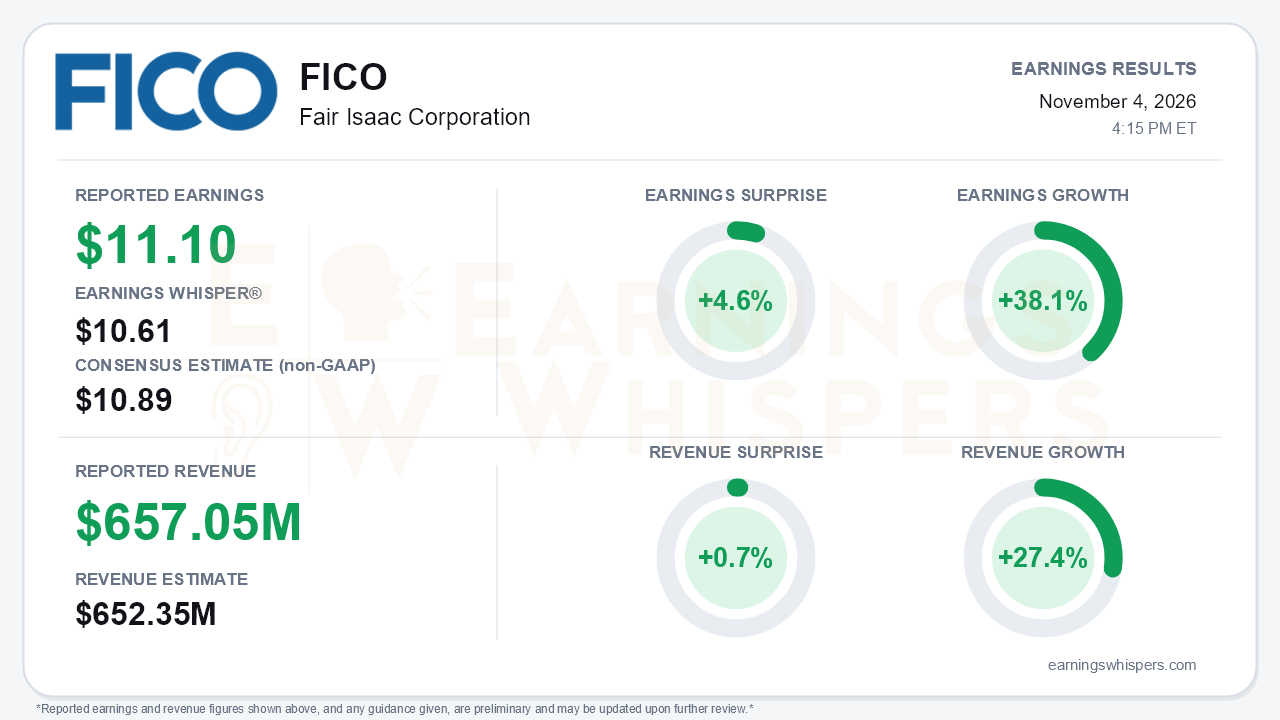
Fair Isaac delivered another clean beat for its fiscal fourth quarter, but the most consequential number in the report is one it declined to give. Non-GAAP EPS of $11.10 beat the $10.89 consensus by 4.6% and cleared the $10.61 Earnings Whisper number. Earnings grew 38.1% year over year. Revenue of $657.05 million rose 27.4% and edged past the $652.35 million consensus by 0.7%. Yet FICO withheld fiscal 2027 guidance entirely, citing a mid-stream transition to bespoke mortgage pricing and a weak origination market. That is a sharp break from a company that issued annual guidance and raised it on its Q2 and Q3 calls. That is the central tension: the quarter closed a record year, while the outlook for the profit engine that drove it became far less visible.
The quality of the beat holds up on an operating basis, but the GAAP line is noisier. GAAP EPS rose to $8.12 from $6.42. That figure absorbed a $65 million accrual for a proposed antitrust class-action settlement tied to the Scores business and a $27 million restructuring charge for workforce reductions. It also benefited from a $48 million gain on the sale of a minority equity investment. All three items were excluded from non-GAAP results. GAAP operating income rose only about 12%, to $266.6 million. Cash generation was unambiguous: quarterly free cash flow reached $284.3 million versus $210.8 million, and fiscal 2026 free cash flow of $1.034 billion rose 40%. The full year landed at $2.535 billion in revenue and $42.99 in non-GAAP EPS, ahead of the raised Q3 targets of $2.53 billion and $42.43.
Beneath the headline, the business mix is shifting in opposite directions.
**Software is accelerating.**
- Segment revenue grew 19%, versus just 2% in Q3.
- Platform ARR jumped 72% to $453 million, after 33%, 49% and 62% growth in the prior three quarters. Excluding migrations, growth was in the mid-40s.
- Platform net retention climbed to 156% from 148%.
- Trailing-twelve-month ACV bookings reached a record $140 million, and Q4 bookings were $45 million versus $29 million in Q3.
- Non-platform ARR fell 18%, with 82% retention, so part of the platform surge reflects migration rather than purely new demand.
**Scores is decelerating.**
- Scores revenue grew 33%, down from 41% in Q3 and 60% in Q2.
- Mortgage originations revenue slowed to 72% growth from 97% and 127%.
- Mortgage volumes fell high single digits, compared with low-single-digit growth in Q3.
- A shift toward HELOCs lowered the average price sequentially.
The forward picture in mortgage is where bears have legitimate ammunition. The FICO Preferred Program, launched in October through tri-merge resellers, carries no 2027 wholesale price increase and bundles the classic score with 10T. That reads as a competitive response to VantageScore and suggests the run of outsized price hikes is pausing. Management also said it will no longer disclose mortgage pricing terms and declined to say whether average pricing will rise, hold or fall.
There are offsetting catalysts:
- The FHA will accept FICO Score 10T from January 1, 2027.
- The 10T adopter program grew to 84 lenders from 70.
- Direct license agreements now cover roughly 73% of reseller volume, up from about 60%.
Still, VantageScore 4 also goes live at FHA on the same date, and GSE approval for 10T implementation and reseller score calculation remains pending, as it has been all year.
The balance sheet adds another layer. FICO repurchased about $3.05 billion of stock in fiscal 2026, and long-term debt rose to $4.92 billion from $2.66 billion. Buybacks are now paused to repay the term loan tied to the accelerated share repurchase. Leverage stands at 3.29 times net debt to EBITDA, and interest expense is rising. Professional services revenue, already down to $19.5 million in the quarter, is expected to decline significantly in fiscal 2027. That removes the share-count tailwind just as Scores pricing visibility fades.
The market had already priced in a good deal of this anxiety heading into the report. As of the pre-report snapshot, shares were at $724.38:
- down 37% from the $1,150 open after the July report;
- 35.1% below the 200-day moving average;
- 41.5% below the inter-earnings high of $1,238.60, set the day after that report;
- 23.6% above the September 30 low of $586.05, which was also a 52-week low.
Investor sentiment deteriorated meaningfully, from -0.17 to -0.48. Expectations are clearly skeptical rather than euphoric. Price and AVWAP trend readings remain negative, although momentum has turned positive off the September low.
The bottom line is that FICO beat on every headline measure and showed genuine acceleration in its software platform. However, the investment debate has moved from how much mortgage pricing can rise to whether it can hold. Withheld guidance, a frozen 2027 price, undisclosed pricing terms, decelerating Scores growth, a litigation accrual and paused buybacks all reduce visibility in the segment that generates most of the profit. The beat was real, but it does not resolve that uncertainty, and a heavily de-rated stock with souring sentiment suggests investors already understand the setup has changed.
Read our earnings preview for Fair Isaac Corporation: https://www.earningswhispers.com/article/FICO/21838
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| 6 hours |
FICO Declines to Share Guidance Amid Price Structure Change
FICO FICO -6.07% AH
The Wall Street Journal
|
| 6 hours | |
| 6 hours | |
| 8 hours | |
| 15 hours | |
| Nov-02 | |
| Oct-30 | |
| Oct-27 | |
| Oct-27 | |
| Oct-26 | |
| Oct-26 | |
| Oct-26 | |
| Oct-26 | |
| Oct-23 |
