Franklin Covey Beats On EPS As Revenue Misses, Leaning On Record Deferred Revenue To Support A Modest FY27 Growth Outlook
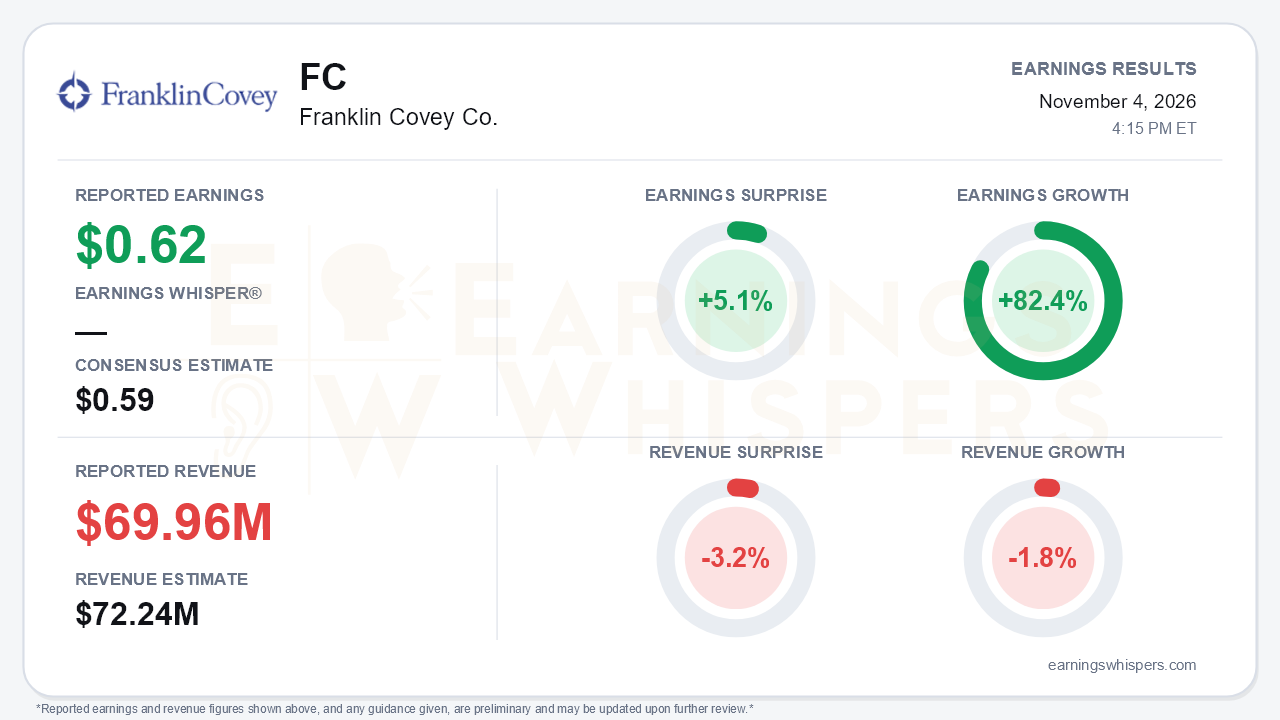
Franklin Covey (NYSE: FC) closed fiscal 2026 with a split result. Fiscal fourth-quarter earnings of $0.62 per share beat the $0.59 consensus by 5.1% and grew 82.4% year over year. Revenue of $69.96 million missed the $72.24 million consensus by 3.2% and fell 1.8%. Revenue has now declined for the full year, with FY26 sales of $261.5 million down 2% and landing at the bottom of a range that was already cut in the third quarter from an original $265-275 million. That is the central tension. Management says its rebuilt go-to-market model is working, and forward indicators such as deferred revenue support that claim. Reported revenue, however, has not followed, and the first FY27 guide still came in below Street revenue expectations.
The quality of the beat deserves scrutiny. Pretax income rose only about 8%, to $8.6 million from $8.0 million. The EPS jump came mostly from two other sources:
- The income tax provision fell to $1.5 million from $3.6 million.
- Diluted shares dropped roughly 10% after $28.1 million of buybacks during the year.
Operationally, the better story is cost discipline. Adjusted EBITDA rose 9% to $12.8 million and margin widened to 18.3% from 16.4%, even on lower revenue, as SG&A and amortization declined. Gross margin moved the other way. Full-year gross margin slipped to 75.0% from 76.2%, and Enterprise North America segment EBITDA fell to $25.5 million from $27.4 million. Cash generation also weakened. Free cash flow dropped to $9.2 million from $12.1 million, and cash fell to $13.3 million from $31.7 million. Management is pausing buybacks to rebuild cash.
The call preserved a credible growth narrative built on contracted commitments rather than recognized sales:
- **Deferred revenue:** Enterprise North America deferred revenue grew 17% to $59.2 million. That follows growth of 8%, 16% and 18% in the prior three quarters and is the strongest level in years.
- **Committed services:** Enterprise subscription and committed-services invoicing rose 18% to $117.7 million.
- **Sales productivity:** Invoiced amounts per new-client sales professional have more than doubled versus FY24.
- **International:** Adjusted EBITDA rose to $7.9 million from $5.1 million.
The near-term invoicing trend, however, is decelerating. North America invoiced growth went from 7% in each of the first two quarters to 4% in Q3 and flat in Q4. Management also expects Q1 FY27 invoicing to decline against a $5.6 million upfront committed-services comparison. Education was weaker beneath its full-year revenue gain:
- Invoiced amounts fell 10%.
- Deferred revenue declined 6%.
- A statewide deal and a roughly $3 million district renewal slipped into FY27.
Client logo retention also came in a couple of points below management's target.
FY27 guidance frames the bet. The press release calls for revenue of $263-273 million and adjusted EBITDA of $29-34 million. At the midpoint, that implies about 3.3% comparable revenue growth (2.5% reported) and 9% EBITDA growth, with roughly 80 basis points of margin expansion. One conflict is worth flagging. The call analysis cites a $253-273 million revenue range, while the release table shows a $263 million low end. Investors should treat the release figure as primary but confirm it. Either way, the range is wide, and its low end reflects execution and state-funding risk. The China conversion to a licensee model is expected to close by the end of Q2 FY27, shaving about $2 million from revenue with no material EBITDA effect. Other forward drivers include:
- Phase two of the go-to-market model, with hunter headcount up 20%, sales development reps rising from about 20 to about 28, and marketing spend up 25%.
- Extension of the model to Europe, Japan and Australia.
- AI-adoption engagements that open CIOs and CTOs as a new buyer.
- A new Education EVP.
- Management's signal that revenue growth should accelerate in FY28.
The market setup is more complicated than the EPS surprise implies. As of the pre-report snapshot, shares traded at $17.17, down 11% since the open after the July report. That left them 12.4% below the $19.60 200-day moving average and 26.5% below the $23.36 inter-earnings high set just days after that release. The stock was sitting only 4.9% above its late-September low of $16.37, so it entered earnings having surrendered the entire post-July pop. Investor sentiment of -0.09 is mildly negative rather than hostile. The Earnings Whispers price and AVWAP trend readings remain negative, while momentum and sequential growth are neutral.
Bears have legitimate ammunition:
- Revenue declined and finished at the bottom of a lowered range.
- North America invoicing is decelerating into a down Q1.
- Education deals keep slipping.
- Gross margin is eroding.
- The EPS beat was flattered by taxes and a shrinking share count.
Bulls can point to record contracted backlog, a leaner cost base and guidance that calls for EBITDA to outgrow revenue.
The bottom line is that Franklin Covey delivered a cosmetically strong earnings beat atop a still-shrinking top line, and the investment case now rests almost entirely on converting a 17% rise in North America deferred revenue into reported growth. The modest FY27 revenue guide, a soft Q1 invoicing setup and depleted cash leave little margin for error. With shares near the bottom of their post-July range, investors will likely need evidence of revenue inflection, not just EBITDA discipline, before the story regains credibility.
Read our earnings preview for Franklin Covey Co.: https://www.earningswhispers.com/article/FC/22017
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 3 hours | |
| 5 hours | |
| Oct-28 | |
| Oct-21 | |
| Oct-06 | |
| Jul-02 | |
| Jul-01 | |
| Jul-01 | |
| Jul-01 | |
| Jun-30 | |
| Jun-17 | |
| Jun-15 | |
| May-21 | |
| Apr-01 |
