Velocity Financial Posts Record Production And Wider Portfolio Margins, But Leverage, REO Losses And The TORAC Bet Raise The Stakes
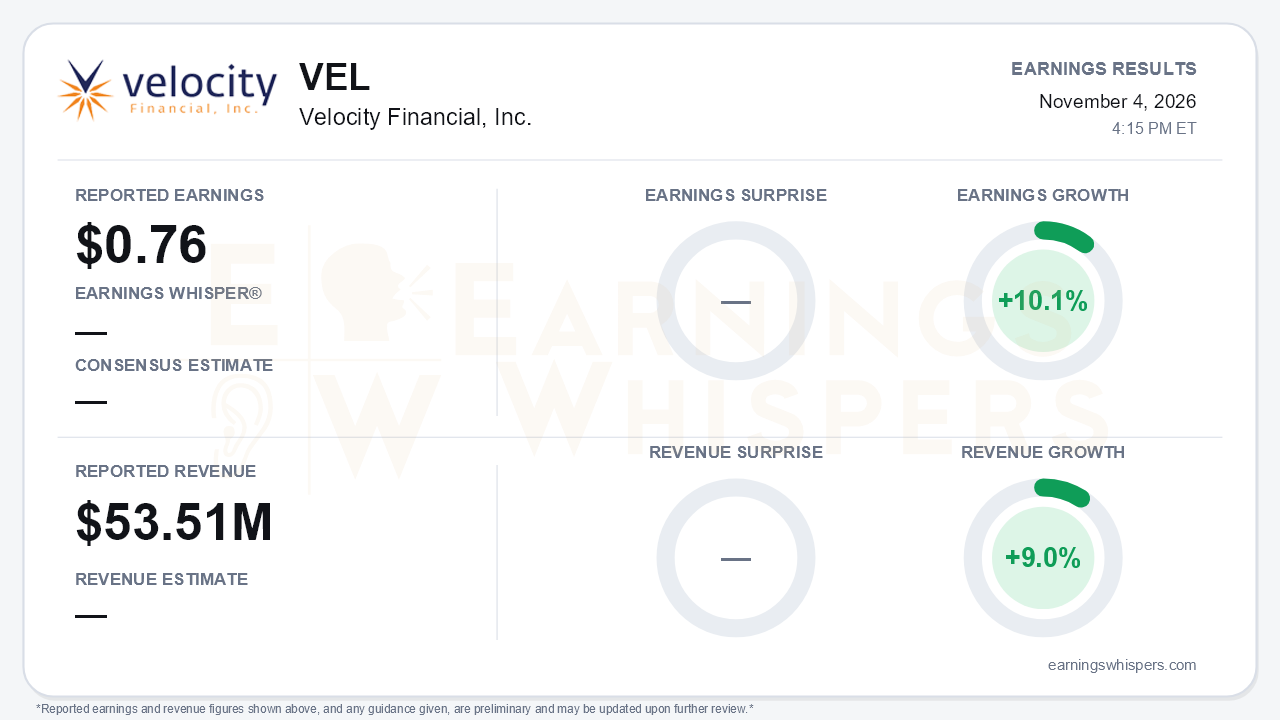
Velocity Financial (NYSE: VEL) reported core earnings of $0.76 per share for the September 2026 quarter, up 10.1% from a year ago. Revenue, measured as net interest income, rose 9.0% to $53.51 million. No consensus estimate or Earnings Whisper was available, so the quarter has to be judged on its own trajectory. On that basis it was a strong operating quarter that also used more of the balance sheet. Loan production reached a record $911.3 million, portfolio net interest margin widened for a third straight quarter, and management sounded markedly more bullish. Liquidity, leverage and credit-related losses all moved the wrong way. That trade-off between accelerating growth and a stretched funding base is the central tension.
The quality of the earnings deserves scrutiny. GAAP diluted EPS was $0.67, up only 3.1% from $0.65. The roughly $0.09 gap to core EPS reflects $2.4 million of M&A due diligence costs tied to the pending TORAC deal and stock-based compensation. Core net income growth of 11.5% is solid, but it has slowed sharply from the roughly 30% pace management cited for the first quarter. Two other measures look weaker than the headline:
- **Total-company margin.** Portfolio NIM improved to 3.78% from 3.65%, but total-company NIM fell to 2.97% from 3.25%. Corporate interest expense more than doubled to $14.5 million after $500 million of unsecured notes carrying a 9.97% rate.
- **Returns on equity.** Pre-tax return on average equity slipped to 20.5% from 22.7% as average equity grew 20%.
Operating expenses climbed 26.7%, with compensation up to $29.2 million as headcount was added ahead of planned growth. Fair-value accounting also produced large offsetting swings: a $64.8 million unrealized loss on loans against an $87.4 million gain on securitized debt.
The operating story is still encouraging. Production jumped about 35% from roughly $673 million in the second quarter. That delivers the second-half pickup management had flagged earlier in the year. The release puts year-over-year production growth at 23.3%, while the call cited about 25%. Several drivers stood out:
- **Century multifamily.** Government-insured multifamily volume rose to $154.9 million from $86.3 million in the second quarter and about $26 million a year ago. That business is capital-light, since the GNMA securities are sold shortly after closing, and it helped lift other income to $16.2 million from $6.4 million.
- **Funding costs.** Portfolio debt costs fell 23 basis points year over year to 6.04%. Securitization spreads have held at 185-205 basis points across the last four deals.
- **Securitization.** The October securitization of roughly $500 million was the largest in company history.
- **Pipeline.** Management cited record applications heading into the fourth quarter.
- **Rates.** Management now frames rising rates as a tailwind, arguing that brokers are replacing lost consumer mortgage revenue with business-purpose lending.
TORAC is the defining forward catalyst and the defining new risk. The acquisition is expected to close in the fourth quarter and has several effects:
- **Product mix.** Short-duration lending would rise from about 6% to over 40% of the mix.
- **Channels and geography.** It adds a direct retail channel and a UK platform.
- **Scale and fees.** Assets under management would reach roughly $10 billion. The existing $3 billion TORAC book was sold to a third party, with TORAC retaining management and servicing fees.
- **Earnings.** Management expects the deal to be accretive to 2027 GAAP earnings.
The CEO also acknowledged that short-duration lending is "different in many ways," so integration and credit execution are real risks. Management further flagged a likely borrower-affordability ceiling around an 11% weighted average coupon if rates keep rising. Third-quarter production carried a 10.12% coupon, down from 10.48% a year ago because of product mix.
Bears have legitimate ammunition on the balance sheet and credit. Liquidity has fallen to $193.4 million from $240 million in the second quarter and $329 million in the first. Recourse debt-to-equity has risen to 1.5x from 1.0x. Total debt-to-equity of roughly 9.6x sits near the ~10x ceiling management referenced last quarter, which suggests continued growth at this pace may eventually require new capital. Nonperforming loans rose to 10.1% of held-for-investment loans, up from 9.8% a year ago and 8.5% at year-end 2025, though the year-end figure was flattered by an NPL sale. REO activity swung to a net loss of about $4.0 million, versus gains of $2.4 million and $3.5 million in the prior two quarters, as valuation losses on existing properties grew. Offsetting factors include:
- an NPL recovery rate of 108.2%, in line with the trailing average;
- charge-offs of just $0.3 million;
- loan-to-value of 64.5%;
- diluted book value of $19.23, up nearly 18% year over year.
Market data are thin for this report. Shares opened at $18.00 after the August release, just above the 200-day moving average of $17.77. That suggests the market had been valuing VEL near book value rather than pricing in the step-up in growth management is now describing.
The bottom line is that Velocity delivered a quarter of real operating momentum, with record originations, expanding portfolio spreads, a growing capital-light multifamily engine and a transformative acquisition close to completion. The cost is a thinner liquidity cushion, leverage near management's own stated limit, rising nonperformers and REO drag. GAAP earnings growth has also lagged core results. The growth story is credible, but the next few quarters depend on executing TORAC and funding that growth without diluting the improving return profile.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Oct-22 | |
| Sep-01 | |
| Aug-27 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Aug-04 | |
| Jul-22 | |
| Jul-03 | |
| Jun-02 | |
| May-06 | |
| May-06 |
