News Corp Extends Profit Streak With A Modest Beat, But Growth Cools From Q4 And Housing Signals Weaken
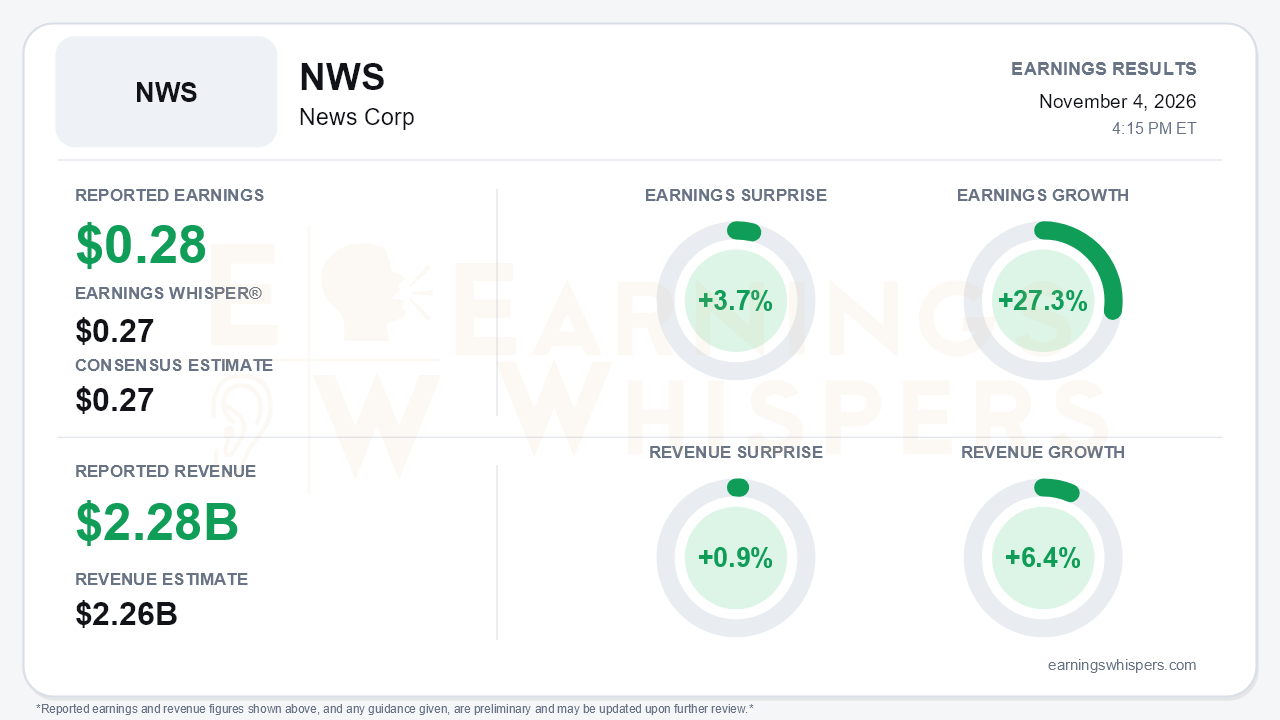
News Corp delivered its 14th consecutive quarter of year-over-year profitability growth, but the more important story is the deceleration beneath it. Adjusted EPS of $0.28 beat the $0.27 consensus and matched the $0.27 Earnings Whisper number with a 3.7% upside surprise. Earnings grew 27.3% year over year. Revenue of $2.281 billion topped the $2.26 billion consensus by 0.9% and grew 6.4%. Total Segment EBITDA rose 19% to $403 million, lifting the margin to 17.7% from 15.9%. That is a solid result. It is also a clear step down from an exceptional fiscal fourth quarter, when revenue grew 11% and EBITDA grew 31%.
The quality of the beat deserves some scrutiny.
- **Currency.** Foreign exchange contributed $43 million of revenue and $15 million of EBITDA, helped by a stronger Australian dollar. Stripping out currency, acquisitions and divestitures, Adjusted Revenues grew only 4% and Adjusted Total Segment EBITDA grew 13%.
- **GAAP earnings.** GAAP EPS of $0.29 was inflated by a gain on the divestiture of REA India's remaining business. That gain pushed Other, net to $38 million. The adjusted figure strips it out.
- **Buybacks.** Diluted shares fell to 542.7 million from 566.9 million, flattering per-share growth. The company spent $166 million on repurchases in the quarter.
- **Book Publishing.** HarperCollins' 29% EBITDA jump is partly an easy comparison, since the prior-year quarter absorbed a $13 million customer receivable write-off.
- **Cash flow.** Free cash flow swung to negative $89 million from positive $4 million. Management attributed this to working-capital timing, a HarperCollins inventory build, higher tax payments and $21 million of additional capex. Management said it remains confident in full-year free cash flow after fiscal 2026 free cash flow of $811 million.
Dow Jones remains the cleanest part of the story, though its profit growth slowed.
- **Revenue.** Segment revenue rose 8%.
- **Energy.** Dow Jones Energy reaccelerated to 8% growth from 4% in Q4, as management had flagged. It also posted its best first-quarter net new bookings since the 2022 acquisition.
- **Risk & Compliance.** Growth held at 11%.
- **Subscriptions.** Digital-only subscriptions reached nearly 6.5 million, with roughly 219,000 sequential net adds, the most in almost three years.
- **Advertising.** Ad revenue rose 9%, with digital up 12%.
- **Profitability.** Dow Jones EBITDA growth halved to 11% from 20%, and margin expansion narrowed to about 80 basis points from 310. Employee costs and marketing timing absorbed much of the revenue upside.
Management reaffirmed its target of $1 billion in Dow Jones EBITDA by fiscal 2030.
The housing-linked businesses are where bears have legitimate ammunition. Digital Real Estate Services EBITDA rose 34% to $212 million, and REA's controllable buy yield grew double digits. The volume picture has turned, however. Australian national new-buy listings fell 2% in the quarter, with Sydney and Melbourne down 16%, after rising 11% in Q4. October listings were down 13%, or 8% adjusted for working days. In the U.S., Realtor.com revenue growth slowed to 5% from 13% as mortgage rates hovered above 7%. Unique users fell 8% and lead volumes fell 11%. Pricing power is carrying REA for now, but that leaves the segment more exposed if listings stay weak. News Media is also deteriorating:
- EBITDA fell 40% to $18 million amid a tough advertising market and California Post costs.
- Audiences shrank sharply at The Sun (57 million monthly uniques versus 77 million) and the New York Post (84 million versus 94 million).
Management also leaned harder on macro caveats, citing tariffs, interest rates and Middle East conflict.
Offsetting those pressures is a growing set of catalysts:
- **Distilled.** REA agreed to take a 35% stake in Distilled, owner of Ireland's Daft.ie, for about US$290 million.
- **REA India.** The exit has closed and will drop out of results starting in fiscal Q2.
- **Anthropic settlement.** The first tranche of the $1.5 billion Anthropic book settlement is expected near term.
- **AI licensing.** Management described active licensing talks with horizontal platforms and specialist verticals, alongside new litigation against Brave and buyers of allegedly purloined content. Chief Executive Robert Thomson summarized the posture as "we will woo and we will sue."
These are real optionality points, but the call offered no change to the outlook and no update on buybacks.
Investor sentiment shifted meaningfully into the report. It moved from modestly negative (-0.16) after the August release to moderately positive (+0.26), a sizable swing for this scale. The share price tells a less enthusiastic story. As of the pre-report snapshot, shares at $32.06 were down 7.6% since the open following the prior report and about 10% below the 52-week high of $35.76 set in late August. They sat only about 3% above the early-October inter-earnings low. The stock remains roughly 5% above its 200-day moving average, so the longer-term trend has not broken. Internal trend readings are mixed, with momentum positive while AVWAP remains negative, consistent with a stock that has drifted lower despite steady earnings delivery.
The bottom line is that News Corp delivered another quarter of margin expansion and a modest beat, but the headline growth rates owe a measurable debt to currency, buybacks and an easy publishing comparison. Organic revenue grew 4%, and growth decelerated across most major lines from Q4. Dow Jones subscription momentum and the AI-licensing and settlement pipeline give the call a credible growth narrative. Against that, softening Australian listings, a slowing Realtor.com and a weakening News Media segment are the trends to watch. Improved sentiment raises the bar for the next quarter, particularly if housing volumes keep deteriorating.
Read our earnings preview for News Corp: https://www.earningswhispers.com/article/NWS/21894
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Oct-29 | |
| Oct-29 | |
| Oct-27 | |
| Oct-27 | |
| Oct-26 | |
| Oct-22 | |
| Oct-22 | |
| Oct-21 | |
| Oct-19 | |
| Oct-15 | |
| Oct-14 | |
| Oct-08 |
