Clipper Realty Beats On Record Revenue And A Third Straight AFFO Gain, But Cooling Leasing Spreads And 2027 Refinancing Put The Dividend In Focus
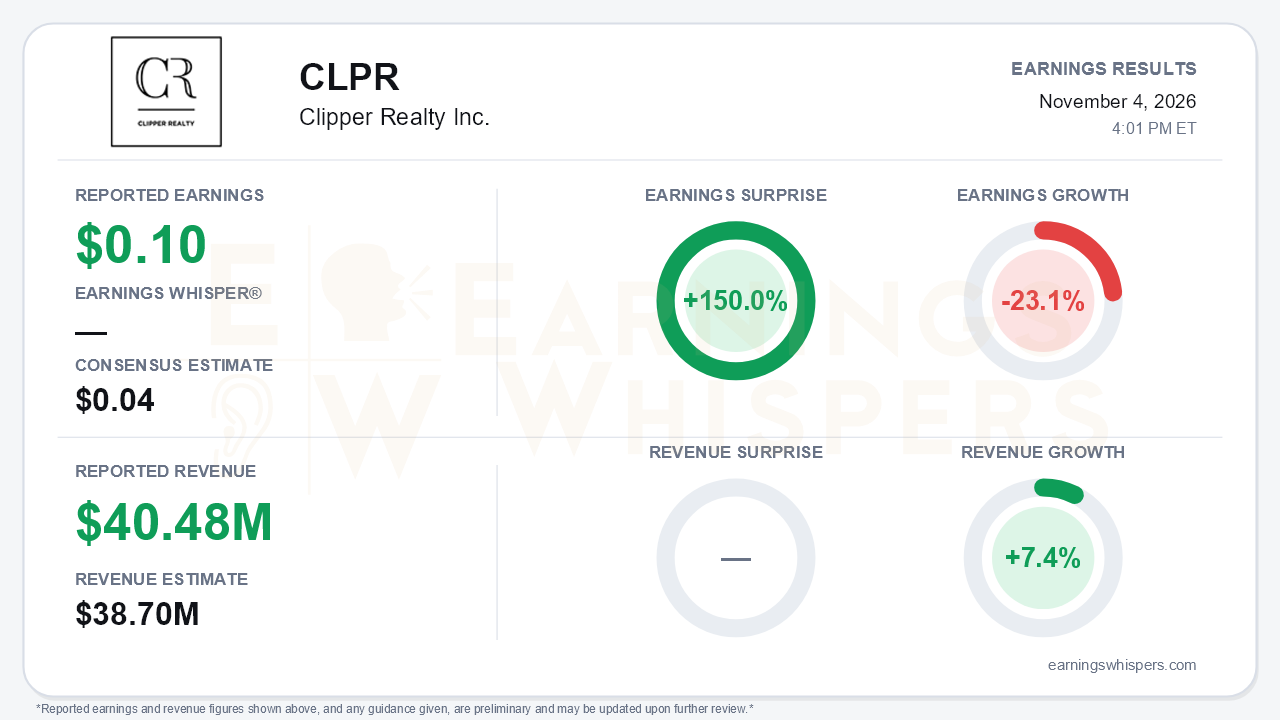
Clipper Realty (NYSE: CLPR) delivered a clean headline beat for the third quarter. Adjusted earnings of $0.10 per share, which equal the company's AFFO per share, topped the $0.04 consensus by 150.0%. Revenue of $40.48 million beat the $38.7 million estimate by 4.6% and grew 7.4% year over year to a record. Earnings still fell 23.1% from a year ago, and on a GAAP basis the company lost $0.18 per share, wider than the $0.14 loss a year earlier. That gap captures the quarter. The operating recovery is real and sequentially improving, but the balance-sheet and dividend questions that hang over this highly levered owner have moved from background to foreground.
The quality of the beat holds up better than the year-over-year comparisons suggest. Residential revenue rose 14.1% to $34.0 million. The gain came from strong rents, high occupancy, and the first full quarter of Prospect House at 953 Dean Street operating at full occupancy. NOI climbed to $22.3 million from $20.8 million, and income from operations rose to $9.9 million. The drag is concentrated almost entirely at 250 Livingston Street. There, the loss of the New York City lease cut commercial revenue by $2.2 million and accounted for $4.0 million of the AFFO decline, which the company describes as substantially non-cash because the lender is funding the property. That hit shrank from $5.8 million in the second quarter. AFFO has now improved for three straight quarters, from $1.7 million in the fourth quarter of 2025 to $2.3 million, $3.8 million and now $4.1 million. Revenue followed a similar path, rising sequentially from $37.1 million to $40.5 million over the same span.
Beneath that improvement, several operating metrics softened. New free-market lease spreads slowed to roughly 8-9% from 13% in both the second quarter and the fourth quarter of 2025. Renewal spreads eased to 5% from 6% and 7%. More concerning, the residential collection rate slipped to about 93% from roughly 96% in the second quarter and 98% in the fourth quarter. Pricing power is still evident at the asset level. Prospect House new free-market rents are running near $84 per foot versus $78 earlier in the year, and Tribeca House new rents reached $105 per foot versus $97. The stabilized portfolio remains about 99% leased. The trajectory, however, has shifted from accelerating to merely positive, and demand commentary was steady rather than stronger.
The forward-looking debate now centers on financing. Management cited two recent refinancings and an average debt rate that fell to 3.68% from 3.87%. GAAP interest expense nonetheless rose to $15.8 million from $13.3 million a year ago, reflecting the end of capitalized interest at Dean Street and the burden of the 250 Livingston loan. Notes payable stand near $1.29 billion against an equity deficit of $114.9 million, and debt duration has shortened to 3.0 years from 3.7 years three quarters ago. Two near-term events matter most:
- **Flatbush Gardens:** the mortgage rate resets and amortization begins in May 2027. When pressed on a possible dividend cut, management said it was "a bit early to tell." Management expects rent increases under the 610/Article 11 programs to support a refinancing without new equity.
- **Dean Street:** the construction loan still needs refinancing, though management says it can be extended to 2028.
The dividend was held at $0.095. That compares with $0.10 of quarterly AFFO and only $0.24 of AFFO through nine months, against $0.285 declared over three quarters. Unrestricted cash fell to $30.6 million from $37.7 million in the second quarter. A delayed supplemental filing and a corrected record date added minor execution noise.
Investors had already moved ahead of the report. Earnings Whispers sentiment swung sharply from negative (-0.23) to clearly positive (+0.50), a substantial shift in expectations. Shares rose 23.5% from the $2.72 open after the August report, which marked the inter-earnings low, to $3.36 heading into the release. That put the stock about 5.7% above its 200-day moving average of $3.18 but 5.4% below the $3.55 high reached in late August, so part of the early rally had already faded. The sequential-growth trend reading is positive, consistent with the AFFO progression, while the AVWAP trend remains negative.
The bottom line is that Clipper delivered the operating proof the bulls wanted: record revenue, a shrinking 250 Livingston drag, and a third consecutive AFFO improvement that easily cleared a low bar. Bears have legitimate ammunition, though. Leasing spreads and collections are cooling just as the company approaches 2027 refinancing milestones, and dividend coverage leaves little margin for error. With sentiment and the share price having already re-rated, the next leg likely depends less on residential demand than on how cleanly management refinances Flatbush Gardens and Dean Street.
Read our earnings preview for Clipper Realty Inc.: https://www.earningswhispers.com/article/CLPR/22015
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Oct-28 | |
| Oct-12 | |
| Aug-06 | |
| Jul-15 | |
| May-21 | |
| May-14 | |
| Apr-22 | |
| Mar-02 | |
| Mar-02 | |
| Feb-27 | |
| Feb-26 | |
| Feb-26 | |
| Feb-24 |
