FatPipe Doubles Consensus EPS, But Slowing Growth, Margin Slippage And A Slow Contract Ramp Temper The Beat
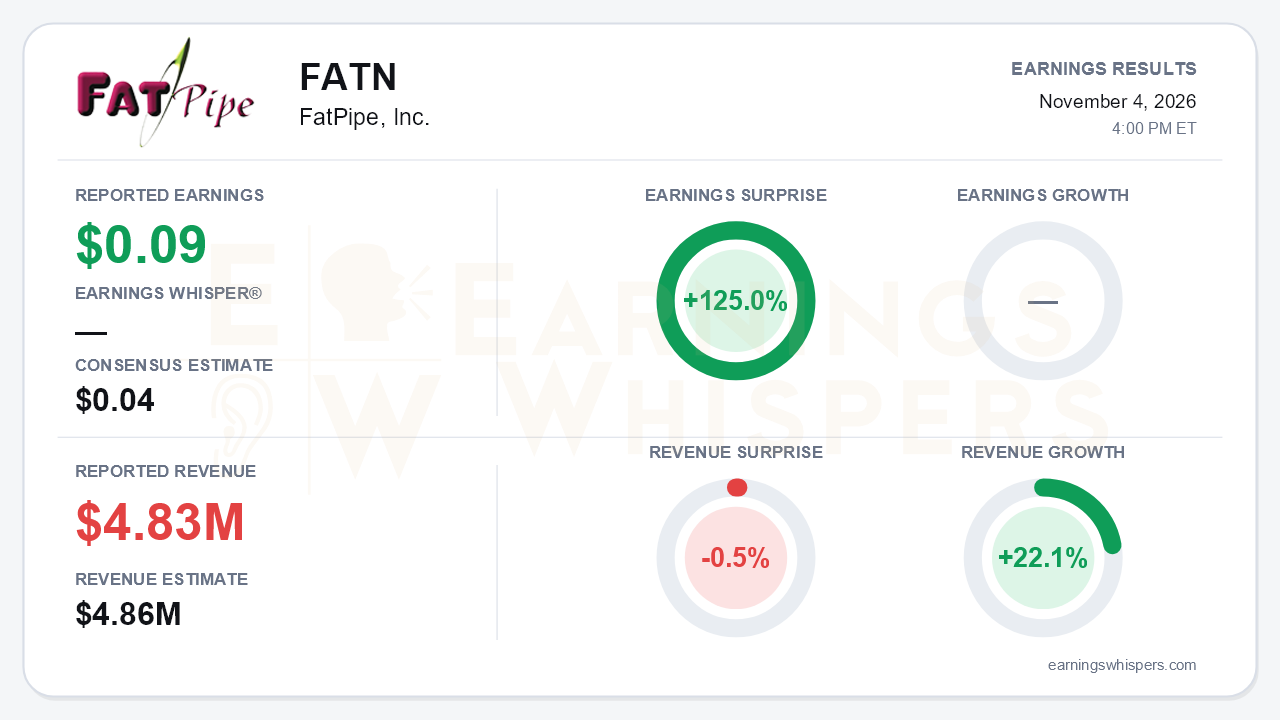
FatPipe (NASDAQ: FATN) delivered a clear bottom-line beat in its fiscal second quarter, earning $0.09 per share against a $0.04 consensus, a 125.0% surprise. Net income reached $1.2 million, compared with a roughly breakeven $0.04 million loss a year earlier. Revenue rose 22.0% year over year to $4.83 million but missed the $4.86 million consensus by 0.6%. That split is the central tension of the quarter. Profitability and recurring billings are strengthening, while the top line is decelerating and several items management promoted last quarter are arriving more slowly than suggested.
The quality of the beat deserves scrutiny. Adjusted EBITDA rose to $1.2 million, a 24.1% margin, from $0.7 million a year ago. That is a genuine improvement in operating leverage. However, net income roughly matched adjusted EBITDA, and the release does not explain what bridged the two, so investors should not assume the EPS upside came entirely from core operations. The revenue picture is softer than the 22% headline suggests. Growth slowed from about 27% in the first quarter. First-half revenue of $9.9 million implies second-quarter revenue fell sequentially from roughly $5.1 million. Gross margin also eased to 90% from the 92%-93% cited in the prior quarter.
The call offered a more constructive view of the recurring engine. Recurring billings rose to $2.9 million from $2.4 million sequentially, up 55% year over year. Management attributed the gain to large-deal deployments and renewals. Demand commentary was upbeat. Management cited:
- additional public-sector wins following the $7 million contract;
- growing traction with TD Synnex, Carahsoft and an Ohio partner;
- continued wins replacing VeloCloud.
Other metrics undercut that momentum. Product remaining performance obligations were flat sequentially as legacy term-license billing rolls off. The $7 million contract is contributing only about $100,000 per month, against a full run rate of about $118,000. That pace is behind the first-quarter suggestion that 30%-35% would be booked in the September quarter.
Management also walked back some of its earlier enthusiasm. SatBoost has not taken off as hoped, a notable retreat from the 'game-changer' framing used last quarter, although management noted a recent uptick in interest tied to Starlink as primary transport. Net sales headcount was flat at about 30. The target of 36 by March is unchanged, and management added a goal of 48 salespeople for next year.
The forward-looking developments lean positive but remain early. The newly launched Constellation WAN/LAN monitoring product is priced per monitored device and can be sold standalone or bundled. It is already drawing orders from a Tennessee city and a bank. FatPipe also:
- completed a small, internally funded software and services acquisition in October;
- refinanced its SBA loan, cutting the rate by about 1.885 percentage points;
- added a $1.5 million credit line;
- reached cash-flow breakeven in October after heavy first-quarter inventory and marketing spending.
Those steps improve financial flexibility. Guidance, however, remains a generic floor of at least 18% revenue growth and an 18% EBITDA margin, below the current run rate and unchanged despite the stronger profitability.
Investor expectations had already cooled before the report. Earnings Whispers sentiment swung from essentially neutral (0.0162) to decidedly negative (-0.4004) heading into the release, a meaningful deterioration. The price action helps explain why. Shares opened at $4.52 after the July report, briefly spiked to an inter-earnings high of $7.13 on August 6, and have since given back much of that move. At $5.16 entering the report, the stock is up 14.2% since the post-report open. It sits 22.5% above its $4.21 200-day moving average but 27.6% below the quarter high. The negative AVWAP reading fits that pattern of a post-report surge that faded.
The skeptics have legitimate ammunition. Revenue slowed and declined sequentially, gross margin slipped, backlog stalled, and two Q1 talking points, the $7 million ramp and SatBoost, underdelivered. At the same time, sharply higher recurring billings, a new product with early orders and cash-flow breakeven are not the signs of a business losing its footing. The quarter looks more like uneven execution in a small, lumpy company than a broken story.
The bottom line is that FatPipe's profit beat was real but narrower in quality than the 125% surprise implies. The sustainability of the recurring-billings growth and the pace of the public-sector contract ramp will matter more than this quarter's EPS. With sentiment already negative and the stock well off its summer high, the next leg depends on whether revenue growth stabilizes above the conservative 18% floor and whether Constellation and the expanded sales force convert early interest into visible top-line reacceleration.
Read our earnings preview for FatPipe, Inc.: https://www.earningswhispers.com/article/FATN/21837
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Oct-27 | |
| Oct-16 | |
| Oct-07 | |
| Oct-06 | |
| Sep-29 | |
| Sep-11 | |
| Sep-11 | |
| Sep-09 | |
| Aug-18 | |
| Jul-30 | |
| Jul-23 | |
| Jul-21 | |
| Jul-16 |
