L.B. Foster Beats And Raises Sales Outlook, But Lower-Margin Rail Growth And A Flat EBITDA Midpoint Temper The Upside
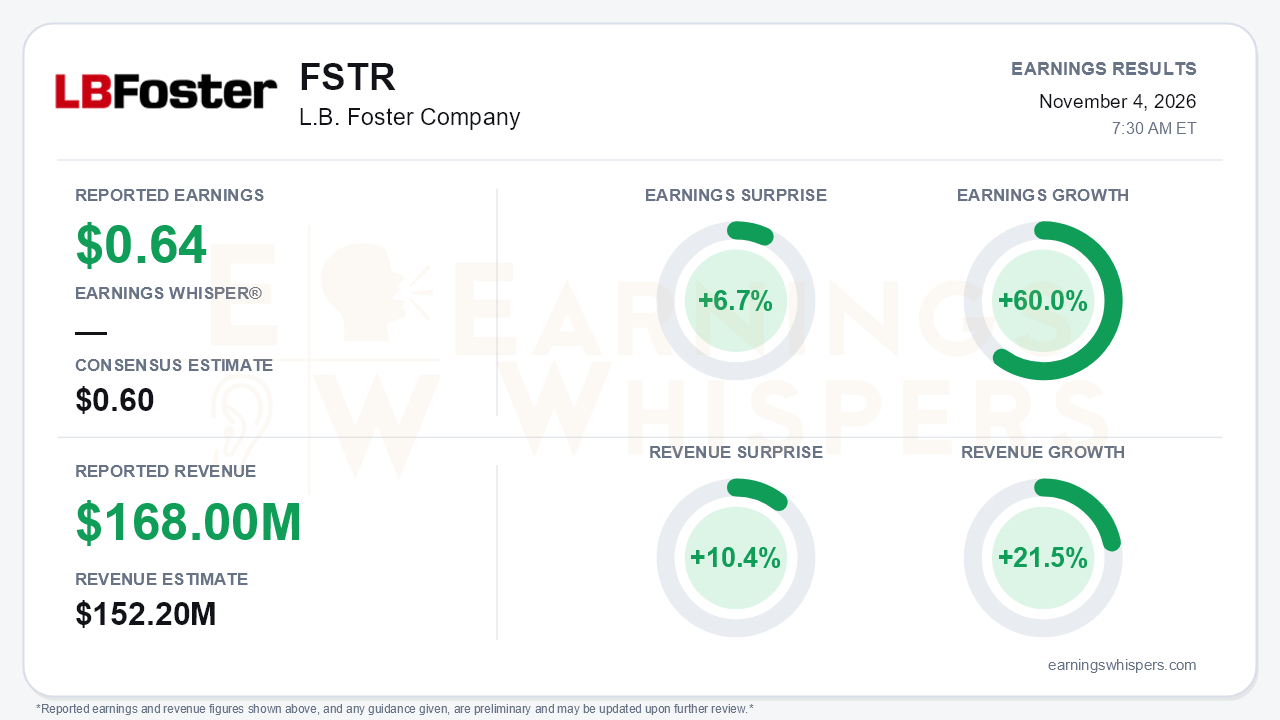
L.B. Foster (NASDAQ: FSTR) delivered the volume rebound it had been missing. Third-quarter EPS of $0.64 beat the $0.60 consensus by 6.7% and grew 60.0% year over year. Revenue of $168.0 million topped the $152.2 million estimate by 10.4% and rose 21.5%. That is a sharp reversal from the second quarter, when sales fell 3.5%. Management responded with its first sales guidance raise of the year, lifting the full-year range to $570–590 million from roughly $540–580 million. The central tension is that the extra revenue is arriving at lower margins. Full-year adjusted EBITDA guidance was only narrowed to $42–45 million, leaving the midpoint essentially unchanged at about $43.5 million and trimming the high end by roughly $1 million. More sales for the same profit is the defining feature of this report.
The quality of the beat deserves scrutiny.
- **Margins compressed on mix.** Gross margin fell 200 basis points to 20.5%, down from 22.5% a year ago and 22.3% in the second quarter. Rail, Technologies and Services sales jumped 32.3%, led by a 54.6% surge in Rail Products, but the growth was concentrated in the lower-margin Rail Distribution and UK businesses. Rail gross margin dropped 320 basis points to 19.6%.
- **Expense leverage offset the gross margin hit.** Selling and administrative expense fell 190 basis points to 14.1% of sales, which kept operating income growing in line with revenue at 21.5%. The operating margin was essentially flat at about 6%.
- **Below-the-line items drove EPS growth.** The outsized earnings increase came largely from lower interest expense and a lower tax bill, not from improved operating profitability.
- **EBITDA lagged sales.** Adjusted EBITDA grew 15.1% to $13.1 million, slower than revenue, and EBITDA margin slipped to about 7.8%.
The call added real substance to the demand story.
- **Orders rebounded.** New orders rose 35.7%, or 16.7% excluding the $19 million cancellation that depressed the prior-year comparison. Infrastructure orders rose 45.7% on that adjusted basis, helped by strengthening energy-related protective coatings demand.
- **Book-to-bill is improving.** Trailing book-to-bill improved for a third straight quarter, from 0.95 to 0.96 to 0.98.
- **Backlog is still shrinking.** Backlog fell to $234.7 million, down from $246.1 million in the second quarter and 5.1% lower year over year. Rail backlog dropped 9.8% and precast backlog declined about $10 million.
- **A former growth engine stalled.** Friction management sales fell 9% in the quarter, a notable reversal after gains of 39.5% and 18.1% in the first two quarters, and orders there fell 10.2%. Management attributed the sales decline to project timing and pointed to Western European expansion that began contributing in the third quarter and should grow into 2027. Bears nonetheless have legitimate ammunition here.
- **The implied fourth quarter is unremarkable.** Guidance implies fourth-quarter sales of about $142–162 million and adjusted EBITDA of roughly $12–15 million.
Cash generation is the cleanest part of the story.
- **Operating cash flow is strong.** Third-quarter operating cash flow was $23.6 million, below last year's $29.2 million. Year-to-date operating cash flow reached $31.0 million, however, versus $13.4 million a year earlier.
- **Debt is at a decade low.** Total debt fell $19.3 million in the quarter to $28.7 million, the lowest level in more than ten years.
- **Free cash flow guidance went up.** The range rose to $20–28 million from $15–25 million, helped partly by a lower capex outlook of about 2.0–2.2% of sales versus 2.7% previously.
That balance-sheet capacity is now being deployed. The company closed a $52.2 million acquisition of a residential wastewater precast business and the Aeris aerobic treatment platform. The release spells the seller "Dulworth," while the call summary uses "Dalworth." Per the call, the business brings about $18 million of annual revenue and $6.5–7.5 million of EBITDA once mostly cost-based synergies are realized over 12–18 months. That margin profile would help offset the mix drag in Rail, but it is a future benefit, not a current one. Guidance assumes no material contribution, and gross leverage moves from 0.6x to about 1.5x, the top of management's target range. Integration execution is now part of the thesis.
The market setup is more complicated than the surprise implies. Investor sentiment swung meaningfully into negative territory heading into the report, falling from 0.08 to -0.27. Shares at $36.46 were down 12.9% from the $41.85 opening after the August report, which also marked the inter-earnings high. The stock bottomed at $34.03 in mid-October and entered the print just 1.4% above its 200-day moving average. Most Earnings Whispers trend readings, including price, sequential growth and AVWAP, remain negative. That reflects a stock that drifted lower even as fundamentals were turning. Skeptics were positioned for continued softness, not a 21.5% revenue jump and a guidance raise. The flat EBITDA midpoint, however, gives them a reason not to capitulate entirely.
The bottom line is that L.B. Foster's quarter was a genuine top-line and cash-flow turn, backed by improving orders, a raised sales and free cash flow outlook, and a debt load low enough to fund a margin-accretive acquisition. Three things limit the upside case: growth is coming through lower-margin channels, backlog is still shrinking, and the profit outlook did not rise with sales. Whether the Dulworth deal and a friction management recovery can restore margin expansion will matter more than the size of this beat.
Read our earnings preview for L.B. Foster Company: https://www.earningswhispers.com/article/FSTR/22423
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Nov-02 | |
| Oct-29 | |
| Oct-28 | |
| Oct-28 | |
| Sep-16 | |
| Sep-14 | |
| Aug-20 | |
| Aug-10 | |
| Aug-10 | |
| Aug-03 | |
| Jul-30 | |
| Jun-16 |
